

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.32% CAGR for Worldwide Oral Clinical Nutrition Supplements Market Through 2032

Worldwide Oral Clinical Nutrition Supplements Market — Strategic Imperatives for 2026: PW Consulting Intelligence Brief
PW Consulting today releases a strategic intelligence brief accompanying our full report on the Worldwide Oral Clinical Nutrition Supplements Market. Built from a rigorous review of market flows, regulatory shifts, payer dynamics, and competitive moves between 2020–2025 and forward-looking scenario modelling for 2026–2032, this brief distils the most actionable findings that should inform executive decisions in the coming 12–18 months.
Worldwide Oral Clinical Nutrition Supplements Market
Headline market context
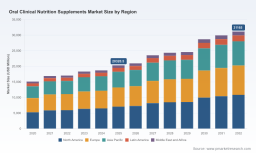
Oral clinical nutrition supplements represent a resilient and steadily expanding segment of medical nutrition. Our base-year assessment places total market value at USD 20.3 billion in 2025. With an expected compound annual growth rate (CAGR) of 6.32% through the 2026–2032 forecast window, the market is projected to approach the low‑to‑mid tens of billions by the end of the decade. Growth is underpinned by demographic tailwinds, rising clinical recognition of malnutrition across care settings, and expanding outpatient and home‑care use cases.
Worldwide Oral Clinical Nutrition Supplements Market
Why this report matters for 2026 decision making
- Prioritization under constrained capital: As companies refine portfolios and allocate capital for R&D, M&A, or geographic expansion, the report offers investment filters that emphasise clinical indication attrition risk, reimbursement exposure, and manufacturing scalability—enabling CFOs and strategy teams to rank options beyond headline growth rates.
- Channel and care‑setting strategies: The shift from inpatient-anchored volume to hybrid hospital–home consumption requires differentiated go‑to‑market approaches. Our frameworks help manufacturers decide where to deploy field forces, which distributors to partner with, and when to pursue direct‑to‑patient models.
- Regulatory and payer alignment: Navigating FSMP (Foods for Special Medical Purposes) designations, label requirements, and shifting reimbursement rules is now a board‑level consideration. The report maps regulatory friction points and payer levers that materially affect commercial viability in major healthcare systems.
- Supply resilience and raw material risk management: Post‑pandemic sourcing fragility remains a practical threat. The brief translates supply‑chain vulnerabilities into mitigation playbooks—dual sourcing, ingredient reformulation thresholds, and nearshoring scenarios—that procurement and operations leaders can operationalize in 2026 planning cycles.
What the full report delivers (practical, execution‑oriented)
- Proprietary market sizing and verified demand forecasts across 2026–2032, with scenario overlays tied to reimbursement policy shifts and clinical guideline adoption.
- Decision tools including a market‑entry scorecard, portfolio prioritization matrix, and unit economics calculator for new product SKUs.
- Reimbursement navigator that translates jurisdictional rules into payer impact scores and commercial action lists.
- Manufacturing and supply‑chain playbook with vendor concentration heatmaps, risk‑mitigation options, and CAPEX timing recommendations.
- M&A and partnership playbook: screening criteria for targets, integration checklists, and valuation adjustment levers specific to clinical nutrition assets.
- Commercial execution modules—channel decision trees, hospital vs home segmentation heuristics, and digital engagement blueprints for caregivers and oncology cohorts.
Competitive landscape — what incumbents and challengers signal for 2026
The oral clinical nutrition market demonstrates clear incumbency advantages: established healthcare players with hospital distribution, clinical trial experience, and payer relationships remain central to go‑to‑market success. Leading multinational manufacturers maintain broad portfolios that span disease‑specific formulas and general clinical support, while a wave of specialized and plant‑based entrants is nudging innovation at the margin.
Worldwide Oral Clinical Nutrition Supplements Market
- Abbott Laboratories (Abbott Park, Illinois): Robust brand equity in general and disease‑specific ONS positions Abbott as a scale player; competitive focus will be on defending institutional channels while expanding outpatient therapy bundles.
- Nestlé Health Science (Vevey, Switzerland): Deep hospital and home care penetration and an established clinical portfolio make Nestlé a natural partner for integrated care pathways and payor pilots.
- Danone Nutricia (Paris, France): Specialist positioning in medical nutrition supports fast follow‑up engagement with oncology and elderly care stakeholders; recent digital partnerships point to a strategy that blends product with care orchestration.
- Fresenius Kabi and B. Braun (Germany): Players with strong hospital ties and enteral capabilities; strategic emphasis is likely to remain on critical‑care and post‑acute channels where procedural procurement and formularies create defensive moats.
- Baxter, Otsuka, Meiji, Ajinomoto and others: These firms bring therapeutic and formulation expertise—critical where amino‑acid or disease‑specific formulations command premium positioning.
- Mead Johnson (Reckitt), Kate Farms and smaller challengers: Pediatric specialization and plant‑based value propositions are creating new product adjacencies and consumer pathways into clinical channels.
- Distributor and private‑label actors (e.g., Medline, Perrigo): These players will continue to apply pricing pressure and broaden access via retail and value channels, requiring brand‑owners to sharpen differentiation.
Recent M&A and partnership moves reinforce two concurrent market dynamics: geographic consolidation to access growth pockets, and digital partnerships to deepen clinical engagement. Examples include an acquisition expanding a European specialist into Latin America, and a cross‑sector partnership that embeds nutritional support into oncology care platforms. Both trends are diagnostic of market maturation—scale through inorganic growth, and value creation through integrated service models.
Regulation, reimbursement and clinical dynamics
Oral nutritional supplements are regulated in many jurisdictions as Foods for Special Medical Purposes (FSMP), which imposes composition and labeling standards distinct from consumer supplements. In major markets, payer policy—particularly outpatient payment rules—now materially influences uptake. For example, evolving Medicare/Medicaid payment frameworks and national reimbursement guidelines will affect where and how ONS is prescribed and reimbursed. The report translates regulatory language into contingency actions: regulatory timelines that trigger launch delays, labeling changes that alter packaging economics, and payer adjudications that change net realised price.
Supply chain and raw material considerations
Raw material exposures—specialized proteins, amino acids, and certain excipients—are non‑trivial. The OECD and industry monitoring have flagged supply concentration for key ingredients. Operational leaders must therefore embed supply resilience into 2026 playbooks through prioritized strategies: validated second sources, scalable contract manufacturing, and strategic inventory policies tuned to product criticality and margin sensitivity. Our report provides a prioritized ingredient‑risk index and actionable sourcing frameworks to implement within 6–12 months.
How to use these insights in your 2026 planning cycle
- Adopt a two‑track portfolio approach: defend institutional mainsails while incubating outpatient/home‑care offerings that leverage digital care pathways.
- Prioritise reimbursement engagement early: establish payer pilots in targeted geographies to convert clinical evidence into funded pathways before scaling manufacturing.
- Accelerate supply resilience investments for high‑risk ingredients and secure flexible contract manufacturing to support SKU proliferation without jeopardizing margins.
- Be selective with M&A: target assets that either fill a clinical‑indication gap or deliver immediate channel access—use our target screening criteria and 100+ company shortlists to triage opportunities.
- Leverage non‑traditional partners: digital oncology platforms, home‑care networks, and specialty distributors are high‑impact collaborators for patient adherence and long‑term revenue visibility.
Why PW Consulting’s analysis is different
Our report blends traditional market modelling with operational, regulatory, and payer overlays—producing not just where the market is going, but how to win within it. We combine primary interviews across hospital procurement, clinical nutritionists, payers and manufacturers, with granular supply‑chain mapping and scenario forecasting. The deliverable is a pragmatic set of tools: from GTM playbooks and reimbursement trackers to M&A playbooks and ingredient risk matrices practitioners can apply immediately in 2026 strategic planning.
Next steps and access to the full intelligence
This brief is a strategic preview intended to equip executives with the key decision levers for 2026. To preserve the competitive value of granular segmentation and scenario outputs, the full report contains the detailed regional and indication breakdowns, pricing and margin banding, and company‑level benchmarking tables that informed the conclusions summarized here. PW Consulting clients and report licensees can access the comprehensive dataset, downloadable tools, and bespoke advisory support via our digital portal.
For organizations preparing budgets, pursuing partnerships, or evaluating M&A in 2026, the summary above highlights where to focus—but the differentiated value lies in the granular, actionable appendices and decision support assets contained in the full report. Contact PW Consulting to schedule a briefing or to obtain access to the Worldwide Oral Clinical Nutrition Supplements Market report and its accompanying toolkits.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Clinical Nutrition Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com