

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Automotive Pinion Gear Market to Reach USD 6,845.2 Million by 2032

Worldwide Automotive Pinion Gear Market — Strategic Briefing for 2026: Actionable Insights from PW Consulting
As OEMs accelerate electrification, autonomy and tighter emissions mandates, the humble pinion gear has re-emerged as a strategic component in global driveline and steering architectures. PW Consulting’s new Worldwide Automotive Pinion Gear Market report (base year 2025) synthesizes market sizing, technology trajectories, regulatory headwinds and supplier dynamics into a decision-ready playbook for 2026. This briefing highlights the report’s most consequential, actionable conclusions while intentionally withholding granular subsegment tables to invite direct access to the full study.
Worldwide Automotive Pinion Gear Market
Market at a Glance — Macro Trajectory You Need to Know
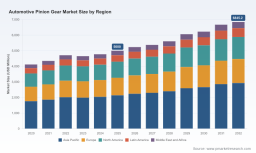
We model the global pinion gear market on a 2020–2025 historical series and a 2026–2032 forecast horizon. The market reached a meaningful milestone in the base year (2025), and our baseline path projects continued expansion through the forecast window at a steady compounded annual growth rate of 4.59%. Early in the forecast (2026) the industry continues to grow modestly from the 2025 base, with acceleration tied to electrified platforms, new steering architectures and incremental replacement demand tied to a larger installed base.
Worldwide Automotive Pinion Gear Market
For executives planning capital allocation or supplier strategy in 2026, this macro trajectory confirms two practical realities: (1) the market is sufficiently large and resilient to justify targeted investments in precision manufacturing and quality systems; and (2) returns will be increasingly driven by engineering-led differentiation (lightweighting, NVH, integration with electric power steering and ADAS) rather than volume expansion alone.
Worldwide Automotive Pinion Gear Market
Why This Report Matters for 2026 Decisions
-
Investment Prioritization — By combining time-series market sizing with technology adoption scenarios, the report shows where incremental volume will appear and where margins will compress. This enables CFOs and corporate development teams to prioritize capex for automation, heat-treatment capacity and advanced metrology where ROI windows are shortest.
-
Product Roadmapping — For R&D and product leaders, our engineering-validated assessment contrasts conventional machining/forging routes against newer powder and near-net-shape approaches, and maps the practical performance trade-offs relevant for high-torque EV drivetrains and steer-by-wire systems.
-
Procurement & Sourcing — Procurement teams receive scenario-based sourcing playbooks that account for evolving trade policy, carbon-cost pass-through and alloy availability, helping reduce single-supplier exposure in a landscape where a small set of manufacturers retain outsized share.
-
Regulatory & Compliance Planning — The study aligns product specifications with the latest standard updates and vehicle-level safety requirements, so suppliers and OEMs can pre-certify processes and minimize rework risk under tightening conformity regimes.
Core Drivers and Systemic Risks
Our analysis identifies five converging forces shaping 2026 decision-making:
-
Electrification and Architecture Change — Electric axles, integrated e-drive systems and electric power steering are changing material, geometry and surface-finishing requirements for pinions. Suppliers that couple metallurgical know-how with systems-level integration capture premium content share.
-
Supply-Side Volatility — Raw-material availability and processing capacity (especially specialty alloy feedstock and heat-treatment throughput) remain key constraints. Expect episodic cost volatility and lead-time pressure unless firms diversify upstream relationships or invest in in-house metallurgical capability.
-
Regulatory Tightening — Global safety and quality standards have been updated, converging toward stricter heat-treatment and process traceability requirements. Simultaneously, emerging carbon border mechanisms and lifecycle compliance are changing the landed cost calculus for imports.
-
Technology Bottlenecks — Novel manufacturing routes (e.g., powder metallurgy) promise cost and waste advantages, but practical fatigue and high-torque durability constraints keep adoption selective across vehicle segments. Incremental innovation in material science will determine winners.
-
Market Concentration — The market exhibits a moderate degree of concentration: a small group of global players capture a substantial share of OEM content, while a long tail of regional and specialized suppliers serves aftermarket and niche commercial segments. Competitive dynamics favor scale in precision production and breadth of OEM certifications.
Competitive Landscape — Who to Watch
Our benchmarking covers global Tier-1 and specialist suppliers and evaluates capability pillars: metallurgical expertise, integration with electronic steering controls, global manufacturing footprint and OEM relationships. Notable players include:
-
ZF Friedrichshafen AG — A global leader in driveline and steering modules. Recent product launches underline ZF’s push into electric steering pinions validated for next-gen safety standards, reinforcing their leadership in systems integration.
-
JTEKT Corporation — Strong in rack-and-pinion steering and a go-to supplier for major Japanese OEMs. Supplier nominations on hybrid vehicle programs demonstrate continued OEM trust.
-
Nexteer Automotive — Focused on electric power steering pinions and the growing intersection with ADAS. Their product set highlights the importance of electronics-mechanical co-design for future steering systems.
-
American Axle & Manufacturing (AAM), Dana, Bharat Forge, Meritor (Cummins) and Eaton — These firms dominate axle, differential and heavy-duty truck pinion supply. Strategic moves include lightweighting projects and collaborative R&D with OEMs on EV axle solutions.
-
NSK, Timken, GKN, Showa, Hyundai WIA — Each brings specialized strengths from precision steering pinions to tapered-bearing-integrated solutions and hybrid driveline components. Their role is increasingly modular: supplying engineered modules rather than commoditized gears.
Recent corporate developments validate the strategic currents above: a leading European supplier launched an electric steering pinion designed for automated driving platforms; a major Japanese supplier secured awardings on new hybrid platforms; and a North American axle manufacturer entered a joint development agreement for lightweight EV pinions. These moves underscore OEM preference for integrated suppliers that can co-develop systems-level solutions and compress development timelines.
What the Full Report Contains — Practical, Non-Academic Deliverables
PW Consulting’s full report is structured as an executive-ready toolkit for 2026 planning. Highlights include:
-
Transparent market sizing (2020–2025 historical series; 2026–2032 forecasts) and scenario runs that stress-test demand under alternative EV adoption and policy scenarios.
-
Supplier capability maps with audited manufacturing footprints, process certifications and OEM qualification status (useful for rapid supplier shortlisting and dual-sourcing design).
-
Cost-to-produce models and margin sensitivity tables that isolate alloy feedstock, heat-treatment, finishing and inspection as primary cost levers.
-
Technology adoption assessments covering conventional forging/machining, powder metallurgy, additive manufacturing pilots and surface engineering techniques — with practical limits and time-to-market implications highlighted.
-
Regulatory and compliance playbook tying the latest standard updates and vehicle-level safety mandates to factory-level process changes and testing regimes.
-
M&A and partnership intelligence: target screening, valuation norms, and integration checklists for buyers looking to buy scale, capability or geographic access.
-
Procurement playbooks for 2026, including a prioritized list of mitigation actions for alloy availability, supplier audit protocols, and contractual clauses for carbon-cost pass-through and lead-time protection.
Recommended 90-Day Actions for 2026 Executives
-
Supply Chain — Map alloy exposure and qualify a second heat-treatment partner for high-risk platforms within 90 days. Implement a short-term alloy hedging and supplier diversification plan.
-
Product Development — Launch a focused durability validation program that simulates EV torque/load profiles and ADAS integration scenarios. Prioritize solutions that reduce NVH while meeting tightened process traceability standards.
-
Commercial — Update bid models to include carbon-cost and lifecycle surcharges expected under new import policies; renegotiate frameworks with strategic OEMs to lock in multi-year design wins.
-
M&A/Partnership — Use the report’s screening matrix to identify small-to-mid cap gearmakers with complementary metallurgy capabilities as acquisition or JV targets to accelerate capability access.
Final Perspective — Where Value Will Be Captured
Through 2026 and beyond, value in the pinion gear market will shift from scale-driven commodity supply to capability-driven, systems-integrated solutions. Firms that combine metallurgical excellence, validated manufacturing processes, and the ability to co-develop with OEMs on electrified and autonomous platforms will command premium returns. Conversely, suppliers that treat pinions as a commodity without investment in process traceability, durability testing and low-carbon sourcing will face margin erosion and loss of OEM access.
PW Consulting’s Worldwide Automotive Pinion Gear Market report provides the empirical backbone and practical playbooks leaders need to act decisively in 2026. The summary above offers the strategic contours; the report contains the complete models, supplier dossiers and scenario tables necessary to operationalize these insights. Access the full study to obtain the granular appendices and validated data sets that will inform board-level capital allocations and procurement contracts for the coming planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Pinion Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com