

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Semiconductor Consumables Market to Grow at 6.99% CAGR, Reaching USD 124.58 Billion by 2032

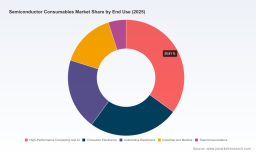
Worldwide Semiconductor Consumables Market — Strategic Intelligence for 2026 Decision-Makers
As global chipmakers accelerate capacity additions for AI, high-performance computing and advanced packaging, the consumables that enable every wafer pass, probe and package have moved from “operational input” to strategic lever. PW Consulting’s new Worldwide Semiconductor Consumables Market report (base year 2025) synthesizes five years of historical performance, near-term turbulence and a 2026–2032 forecast to help executives translate market dynamics into defensible procurement, supply-chain and investment decisions.
Worldwide Semiconductor Consumables Market
Market snapshot: trajectory and growth outlook
The consumables market has demonstrated both robust expansion and episodic volatility across the 2020–2025 period. After recovering from pandemic and cycle-related swings, global consumables revenue reached an estimated USD 77.6 billion in 2025. Our forecast models—which incorporate technology ramp schedules, memory and HPC-driven demand, and supply-chain friction—project a compound annual growth rate of approximately 7.0% through 2032, taking the market to the low hundreds of billions by the end of the decade. That mid-high single-digit CAGR masks shorter-term amplitude driven by raw-material shocks, memory pricing cycles and regional policy moves; yet it also highlights a durable secular tailwind as advanced nodes and heterogeneous integration raise consumable intensity per die.
Worldwide Semiconductor Consumables Market
Why 2026 is an inflection year for corporate strategy
-
Regulatory and trade re-mapping. Layered policy interventions—ranging from new U.S. procurement rules targeting certain foreign foundry customers to tariff adjustments on advanced compute imports—are reshaping where and how consumables are sourced and certified. These shifts create near-term compliance burdens and longer-term incentives for supply-chain onshoring or trusted-source partnerships.
Worldwide Semiconductor Consumables Market -
Raw-material and input volatility. Export controls and licensing measures on strategic minerals and elements have materially tightened upstream availability. Combined with extended logistics lead times and higher energy/chemical costs, margins on consumable manufacturing are under pressure and the operational flexibility of fabs is constrained by single-source exposures.
-
Demand-side concentration. The surge in AI-related memory demand and HBM/DDR configurations has produced abrupt memory-price spikes and tightened testing windows. Consumables tied to high-bandwidth memory production and test—probe cards, wafer carriers and cleaning chemistries—face volatile order patterns that challenge traditional procurement cadences.
-
Localized capability building. Public and private investments in regional infrastructure (for example, purpose-built demonstration and certification centers) signal a push toward near-shore validation of consumables and components. For product developers and buyers, proximity to qualification services is becoming a commercial differentiator.
What the report delivers — practical, decision-ready modules
PW Consulting’s report is deliberately structured to be operationally useful for 2026 planning cycles. Highlights include:
-
Integrated demand-supply models that reconcile fab buildouts, product mix shifts (node & packaging transitions) and scenario-driven memory cycles to project consumable demand under multiple macro-policy paths.
-
Supplier and capability maps that show manufacturing footprints, qualification timelines and bottleneck nodes—not as raw regional share tables, but as actionable maps for sourcing risk assessment and supplier selection.
-
Proprietary scorecards for supplier resilience and strategic fit—covering contamination control competence, test-parallelism capabilities, materials traceability and cleanroom logistics—that support make-vs-buy and dual-sourcing decisions.
-
Procurement playbooks and commercial templates: lead-time hedging structures, consignment arrangements, capacity reservation clauses, and performance-based pricing that help buyers stabilize unit economics through cyclical swings.
-
Regulatory scenario toolkits and compliance matrices that translate tariff, export-control and public-procurement rules into procurement triggers and contingency thresholds for contract renegotiation.
-
Investment and M&A frameworks highlighting high-leverage adjacencies—process equipment consumables, test consumables, and contaminated-control packaging—where consolidation or vertical integration can capture outsized value.
Competitive landscape — who matters and why
The consumables market features a mix of specialized niche players and broad-based materials companies. Market concentration metrics show that the top-three suppliers hold a meaningful but not dominant share of global demand, while the top-five expand that control noticeably—indicating room for both competitive differentiation and selective consolidation.
-
Entegris, Inc. (Billerica, MA) demonstrates a broad playbook across advanced materials handling, contamination control and fluid management. Its integrated technology stack—spanning FOUPs, cleaning chemistries and CMP consumables—positions it as a preferred partner for yield-sensitive fabs and sophisticated contamination regimes.
-
Shin-Etsu Polymer (Tokyo) and other precision-packaging specialists command strength in front-end wafer containers and clean transport solutions. Their engineering focus on contamination minimization and compatibility with high-volume automation remains a critical asset as wafer sizes and wafer-handling automation evolve.
-
For wafer probing and test consumables, suppliers such as FormFactor (Livermore), Technoprobe (Italy), and regional probe-card specialists bring differentiated IP in high-parallelism probing and MEMS/vertical probe architectures—capabilities that materially lower cost-of-test for advanced logic, memory and system-in-package devices.
-
Smaller, regionally concentrated players and precision plastic manufacturers continue to thrive by serving local qualification cycles and rapid turnaround needs, particularly where proximity to fabs reduces qualification latency and risk.
Recent investments that matter: the establishment of regional demonstration and certification centers (example: a new consumables demonstration center initiated in Gangwon Province) will shorten qualification cycles for 300mm mass-production consumable equipment. For suppliers, those facilities lower barriers to winning regional business; for buyers, they increase the pool of qualified alternatives—if suppliers choose to localize testing.
Actionable recommendations for 2026
-
Recast procurement from transactional buying to strategic capacity management. Shift a portion of spend into capacity reservation and performance-based contracts tied to qualification timelines and uptime obligations. This minimizes vulnerability to sudden lead-time extension or price spikes.
-
Prioritize dual-sourcing and validated alternates for high-risk consumables. For items where qualification time is long, invest upfront in parallel validation tracks; treat validation as insurance rather than a sunk cost.
-
Stress-test fabs and product roadmaps against raw-material disruption scenarios. Build scenario-specific mitigation plans for critical inputs and incorporate inventory financing or hedging where appropriate to smooth unit-cost volatility.
-
Leverage regional qualification centers strategically: accelerate time-to-qualified-supplier by partnering with local testing hubs, and use success in those facilities as a market-entry wedge for suppliers seeking to capture regional share.
-
Embed regulatory intelligence into sourcing governance. Create a compliance playbook that translates tariff and export-control changes into procurement triggers and supplier communication protocols to avoid last-minute disruptions.
-
Evaluate selective M&A or JV activity to internalize bottleneck consumables or to secure long-lead items in regions aligned with your manufacturing footprint and policy risk profile.
-
Invest in product design changes that reduce consumable intensity per die—such as test-time reductions, batch consolidation and packaging innovations that extend consumable lifetime—thereby lowering exposure to input-price swings.
Implications for investors and suppliers
For investors, the sector presents a differentiated risk-reward profile. The underlying secular growth drivers—AI, HPC, and heterogeneous integration—support durable top-line growth; yet episodic raw-material and policy shocks will create windows of performance dispersion across suppliers. Companies with demonstrated contamination-control breadth, rapid qualification pipelines, and regional certification footprints are positioned to outgrow the sector average.
For suppliers, the ability to convert innovation into shortened qualification cycles, to quantify and sell resilience (delivery certainty, traceability, compliance) and to structure flexible commercial models will be decisive. Those who can partner with fabs earlier in the product-development cycle and offer demonstrable TCO improvements will secure differentiated margins.
Accessing the full intelligence
This release is a strategic preview of the comprehensive Worldwide Semiconductor Consumables Market study. The full report contains detailed demand-supply matrices, supplier scorecards, scenario-run outputs, and proprietary commercial templates that we intentionally do not disclose here. For procurement leaders, supply-chain architects and investors preparing 2026 plans, the full dataset provides the granular segmentation, regional outlooks and price-impact tables required to operationalize the recommendations outlined above.
Visit the PW Consulting report page to download the executive summary, review methodology notes, and request tailored briefings that map our findings to your organization’s specific product lines, fab footprints and sourcing policies.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Consumables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com