

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Metallocene-Based Polyethylene Market to Expand at 7.45% CAGR, Reaching USD 20,670.65 Million by 2032

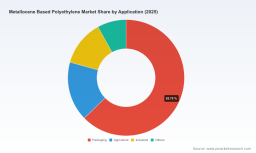
Worldwide Metallocene Based Polyethylene Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence on the Worldwide Metallocene Based Polyethylene market provides a concentrated briefing for corporate strategists, investors, and supply‑chain leaders planning their 2026 moves. Built on a 2020–2025 historical foundation and projecting through 2032, the study quantifies a resilient expansion path: the metallocene PE market is guided by a 7.45% CAGR and grows from a 2025 base year valuation of roughly USD 12.5 billion toward a materially larger global market by 2032. This release distills why that growth matters and how executive teams should reposition portfolios, operations, and commercial models to capture disproportionate value — while preserving the full, granular datasets and proprietary segmentation analysis on our report landing page for subscribers.
Worldwide Metallocene Based Polyethylene Market
Why this market matters to corporate strategy in 2026
- Durable demand drivers: Metallocene‑based PE grades continue to displace conventional polyethylenes in performance packaging, specialty films, and select industrial applications owing to superior mechanical properties, processability and formulation flexibility. These technical advantages underpin higher‑margin opportunities for manufacturers who can align grade portfolios with end‑market requirements.
- Macro tailwinds and headwinds: Feedstock dynamics, emerging regulation on catalyst residues and recycled content mandates, and recent trade measures are re‑shaping cost and access profiles. The combination of these forces means that 2026 will be a year for repositioning commercial contracts, re‑evaluating contract durations, and stress‑testing plant throughput against feedstock volatility.
- Investment timing: With the market trajectory pointing upward into the 2030s, capital allocation toward targeted capacity, debottlenecking, or specialty downstream assets (e.g., cast film lines, extrusion coating) can achieve accelerated payback — but only if paired with differentiated go‑to‑market strategies and feedstock risk mitigation.
What the PW Consulting report delivers (practical, actionable content)
This is not a volume of abstract forecasts. The report is designed as an operational playbook for 2026 decision windows. Key deliverables include:
Worldwide Metallocene Based Polyethylene Market
- Validated market size and trend decomposition (2020–2025 historical; 2026–2032 forecast) with scenario sensitivity to ethylene price swings and recycling uptake assumptions.
- Commercial impact models that translate grade‑level premiums and process yield improvements into P&L outcomes for typical producer archetypes (integrated majors, regional players, and specialty formulators).
- Feedstock exposure matrix mapping plants to ethylene sourcing routes, contract types, and counterparty concentration — enabling procurement teams to prioritize short‑term hedges and long‑term vertical integration options.
- Regulatory and sustainability playbooks that quantify the implications of evolving food‑contact restrictions, recycled content mandates and certification regimes on grade portfolios and labeling claims.
- A competitive benchmarking toolkit: capex timelines, technology partnerships, licensing footprints, and tailored M&A screening filters to identify attractive bolt‑on targets or JV partners.
- Commercial scenarios for customers (converters and brand owners) — including cost‑in use comparisons that support value‑based pricing negotiations for metallocene grades versus commodity PE.
Market dynamics shaping 2026 decisions
- Feedstock pressure and pricing. Recent spot ethylene moves have materially increased raw material cost volatility. Our modelling shows that sustained ethylene price excursions compress conventional margins faster than metallocene segments that carry a technical premium, but prolonged spikes will still force commercial renegotiation and elevated working capital needs.
- Regulatory friction and compliance cost. New controls on catalyst residues and evolving food‑contact requirements are prompting near‑term reformulation and certification costs for suppliers who serve packaging and food channels. Compliance timelines should be embedded into product roadmaps during 2026 procurement and R&D planning cycles.
- Trade and tariff considerations. Recent trade remedies and countervailing measures have altered arbitrage routes and created opportunities for regional suppliers — strategically, this incentivizes vertical proximity to demand hubs and may accelerate on‑shore capacity adjustments.
- Transport and logistics constraints. Operational plans that ignore modal and route‑specific surcharges risk underestimating landed cost impacts. Logistics sensitivity analysis is now a necessary part of any 2026 pricing and plant utilization plan.
- Sustainability imperatives. Mandated recycled content thresholds in key jurisdictions are forcing formulators to re‑engineer host polymers and compatibilizer strategies. For metallocene PE, this creates both a product development challenge and a marketable differentiation if sustainable blends preserve performance.
Competitive landscape — who matters and why
The market sits between specialization and scale. A handful of global petrochemical majors and regional champions dominate technology development, brand recognition and offtake relationships. PW Consulting’s competitive intelligence highlights strategic positioning across ten core players, including LyondellBasell Industries, Dow Inc., ExxonMobil Chemical, SABIC, Borealis AG, INEOS Olefins & Polymers, TotalEnergies Petrochemicals, Prime Polymer (Mitsui Chemicals), LG Chem and Reliance Industries.
Worldwide Metallocene Based Polyethylene Market
- LyondellBasell (Houston, TX) leverages well‑known metallocene brands and has signaled capacity commitment with large expansions in its European footprint, an action that will alter feedstock and logistics balances for competitors and converters in the region.
- Dow Inc. (Midland, MI) is advancing sustainability credentials through certifications and targeted grade developments aimed at circularity and elastic film applications — an important commercial lever for brands seeking verified recycled content and chain‑of‑custody assurances.
- ExxonMobil Chemical (Spring, TX) continues to focus on high‑strength film and blow molding grades, sustaining advantages in integrated feedstock access and scale manufacturing.
- SABIC (Riyadh) is expanding product offerings with new cast‑film‑friendly grades, reinforcing competitive tension in performance packaging segments.
- Borealis, INEOS, TotalEnergies, Prime Polymer, LG Chem and Reliance all occupy strategic niches (regional supply leadership, brand licensing, downstream partnerships) and are executing a mix of capacity, product and sustainability plays to protect or grow share.
Recent company moves in late 2025 and early 2026 — capacity additions, new grade launches, and sustainability certifications — are signals that the next 12–18 months will be active for repositioning. Our report correlates these corporate motions to likely pricing and utilization scenarios, enabling buyers and sellers to anticipate tightening or softening windows.
Strategic implications and recommended actions for 2026
- For producers: Prioritize portfolio segmentation into premium metallocene offerings that command process and performance premiums, while protecting margins with flexible contract terms tied to feedstock indices. Evaluate debottlenecking and selective greenfield investments where logistics and feedstock access are advantageous.
- For converters and brand owners: Run value‑in‑use pilots that quantify downgauge potential, shelf‑life impacts, and recycling compatibility. Enter into dual‑sourcing and volume‑flex contracts to shield margins from raw material shocks and tariff swings.
- For investors and M&A teams: Use our screening toolkit to identify targets with differentiated IP, high client concentration but underleveraged customer contracts, or regional assets that benefit from displaced imports due to tariffs.
- For procurement and supply‑chain leaders: Incorporate logistics surcharges and regulatory compliance costs into landed‑cost models and renegotiate lead times and flexibility into supply agreements to manage Q3–Q4 2026 risk windows.
Why PW Consulting’s analysis is the right basis for 2026 choices
Our study combines rigorous bottom‑up supply analyses, plant‑level economics, and converter demand modeling with scenario‑based forecasting that accounts for policy, trade, and feedstock shocks. Importantly, the report translates technical grade attributes into commercial terms — enabling decision makers to move beyond intuitive choices to quantified strategic tradeoffs.
We intentionally present this summary as a strategic “trailer”: it surfaces the directional conclusions, commercial implications and competitive context you need to evaluate priorities in 2026, while preserving the full segmentation tables, regional and application breakdowns, and plant‑level datasets for secure delivery on the report page. That granular layer contains the precise splits and monetary values that commercial teams rely on for contract negotiations, plant economics and M&A diligence.
Next steps
- Download the full report for immediate access to: detailed segmentation, regional and application forecasts, plant maps, supplier scorecards, and downloadable financial models.
- Commission a bespoke strategy session with PW Consulting to stress‑test your 2026 product roadmap, capital plan, or procurement strategy against alternate feedstock and regulatory scenarios.
- Subscribe to our downstream webinar series where we unpack scenario outcomes and run live sensitivity exercises using the report’s interactive models.
For access to the complete datasets and to arrange a 2026 strategic workshop, visit our report page. PW Consulting remains available to convert these insights into executable programs that protect margin, de‑risk supply exposure, and create premium market positions in the evolving metallocene PE landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Metallocene Based Polyethylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com