

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.5% CAGR for Worldwide Aspergillosis Drugs Market in New Insight Report

Worldwide Aspergillosis Drugs Market — Strategic Preview for 2026: What Leaders Must Know
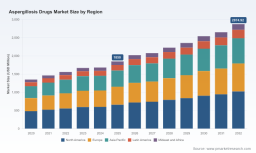
As the global healthcare landscape recalibrates around post‑pandemic priorities, antifungal therapeutics for aspergillosis have moved from niche specialty care into a strategic growth corridor. PW Consulting’s latest market study — anchored on a 2025 base year and a seven‑year forecast to 2032 — finds the worldwide aspergillosis drugs market expanding at a compound annual growth rate (CAGR) of 6.5%. Our topline modelling shows market value growing from a historic 1.35 billion USD in 2020 to roughly 1.85 billion USD in 2025, with an immediate uptick to around 2.02 billion USD in 2026 and a projected trajectory toward approximately 2.87 billion USD by 2032 (revenues expressed in USD Million). This is not a slow, episodic recovery — it is a structurally driven growth trend that will shape portfolio, M&A, supply and access decisions in 2026.
Worldwide Aspergillosis Drugs Market
Why this report matters for 2026 strategic decisions
-
Timing matters: 2026 will be a pivotal year for portfolio repositioning. With the market poised to exceed the 2.0 billion USD mark in 2026 and a sustained CAGR through 2032, biopharma executives must decide now whether to invest in incremental innovations (label expansions, formulation shifts, lifecycle management) or to pursue more disruptive entry via novel mechanisms.
Worldwide Aspergillosis Drugs Market -
Concentration dynamics create differentiated windows. The market exhibits meaningful concentration among the top players, with the leading three firms commanding a majority position and a top five dominance approaching three‑quarters of market share. For challengers, this means targeted, high‑impact strategies (niche indications, combination therapy, differentiated safety/tolerability) will be higher‑return than broad head‑to‑head plays.
Worldwide Aspergillosis Drugs Market -
Regulatory and reimbursement levers will disproportionately determine commercial upside. Recent label expansions, Medicare reimbursement updates, and evolving guideline placements all heighten the commercial value of near‑term regulatory wins and strategic evidence generation.
What we analyzed — and how the deliverables translate to action
PW Consulting’s report blends rigorous quantitative modelling with executable commercial playbooks. Core deliverables include:
-
Top‑down market forecast (2020–2032) with sensitivity scenarios that isolate the impact of: novel approvals, changes in guideline positioning, generics penetration, and episodic supply disruptions.
-
Practical TAM/SAM/SOM frameworks modeled for multiple commercialization strategies (standalone launch, licensing, co‑promotion), with break‑even and NPV analyses under conservative and aggressive uptake curves.
-
Clinical and regulatory roadmap mapping — prioritizing indications and label leverage opportunities (e.g., pediatric extensions, salvage therapy designations, and orphan pathways) for maximal near‑term value.
-
Go‑to‑market playbooks tailored to four commercial archetypes: incumbent market leader, specialty challenger, late‑stage entrant with a novel mechanism, and generics/volume supplier. Each playbook includes stakeholder maps (IDNs, transplant centers, hematology/oncology networks), pricing levers, and payer evidence templates.
-
Supply‑chain risk assessment and mitigation blueprints that quantify the commercial impact of drug shortages and propose contractual, geographic and manufacturing strategies to sustain continuity of care.
-
Competitive intelligence dossiers on the major incumbent and emerging players, including event‑driven trackers for label changes, late‑stage trial outcomes, and regulatory filings.
Competitive landscape — who’s shaping the market and why it matters
The competitive picture combines large, diversified pharmaceutical firms that own established first‑line assets, with smaller, innovation‑led companies advancing novel mechanisms. Leading multi‑national firms continue to secure market leadership through broad clinical portfolios, manufacturing scale and global distribution. Notable dynamics include:
-
Pfizer: The company markets a cornerstone azole antifungal that remains the standard first‑line therapy for many invasive presentations. Recent pediatric label expansion underscores the commercial and clinical value of lifecycle management and broad accessibility. For incumbents such as Pfizer, incremental indications and supply reliability translate directly into preserved volume and pricing leverage.
-
Merck & Co.: With an FDA‑approved broadened antifungal option in adults, Merck’s positioning highlights the premium for agents that can credibly claim efficacy across multiple severe fungal syndromes. Reimbursement pathways (including dedicated codes in some jurisdictions) further enhance uptake prospects for appropriately positioned agents.
-
Gilead Sciences: Amphotericin formulations remain essential for severe salvage therapy and complex cases. Gilead’s portfolio underscores the commercial importance of high‑value hospital‑administered therapies where margin and formulary placement can compensate for lower patient volumes.
-
Astellas Pharma: Echinocandin class agents are critical in prophylaxis and in immunocompromised populations. For biologics‑adjacent antifungal assets, the value comes from inpatient adoption and integration into transplantation and oncology care pathways.
-
United Therapeutics & Scynexis: Oral glucan synthase inhibitors and related novel oral agents introduce a new commercial axis — the possibility of earlier outpatient management and reduced hospital burden. Positive phase 3 outcomes reported mid‑2024 have materially improved the risk/reward profile for these entrants.
-
F2G: The development of novel mechanisms specifically targeting azole‑resistant Aspergillus represents the classic asymmetric opportunity — limited upfront patient numbers but disproportionately high value where resistance undermines standard therapies. The company’s recent regulatory filing activities position it as a potential disruptor if approvals are secured.
Industry dynamics shaping near‑term value
Several background forces are compressing both risk and opportunity into actionable timelines for 2026:
-
Guideline & regulatory positioning: International guidelines continue to endorse azole therapy as a first‑line approach for invasive disease. This entrenched guidance supports steady demand for recognized azoles but also raises the bar for entrants — they must demonstrate either superior efficacy, improved safety, or clear value to displace entrenched standards.
-
Intellectual property and generics: Patent expirations in the past decade created robust generic competition for older azoles, materially reducing cost of standard therapy and pressuring brand premium. For innovator companies, differentiation via formulation (IV-to-oral), pediatric indications, or combination therapy is increasingly the primary avenue to sustain margins.
-
Reimbursement architecture: Recent updates to reimbursement codes in major markets reduce barriers to access for newer agents that secure specific billing pathways. Proactively engaging payers with health economic dossiers will be decisive in capturing 2026 procurement cycles.
-
Supply fragility: Historic shortages of amphotericin formulations exposed the system’s vulnerability. Manufacturers and health systems that preemptively shore up supply lines, diversify sources, and adopt contingency inventories will protect both patient care and commercial continuity.
-
Resistance patterns: Rising environmental azole resistance in certain geographies elevates the clinical and commercial importance of novel mechanisms. Even modest increases in resistance prevalence can shift treatment algorithms toward second‑line or investigational agents, creating targeted commercialization windows.
Strategic imperatives for 2026 — recommended actions
-
Prioritize near‑term regulatory expansions and label lifecycle plays. Pediatric approvals, salvage therapy indications, and outpatient formulation approvals have high ROI within the 2026 decision horizon.
-
Lock in supply and capacity. Execute dual‑source agreements for critical hospital drugs, invest in contract manufacturing resiliency, and include shortage contingencies in commercial forecasts to avoid disruptive volume swings.
-
Invest selectively in late‑stage assets with differentiated mechanisms. For companies with capital, targeted acquisitions or licensing of agents addressing azole resistance or enabling oral outpatient care will pay off given the market growth profile and the premium assigned to differentiation.
-
Build payer evidence early. Secure real‑world evidence pilots and health economic models now so reimbursement conversations in 2026 are anchored in demonstrated value rather than theoretical benefit.
-
Adopt a nimble geographic commercialization stance. While global demand is growing, the interplay of resistance, reimbursement, and clinical practice varies by market — prioritize launches where clinical need, favorable reimbursement, and guideline receptivity align.
-
Map partnership ecosystems. For smaller innovators, co‑promotion, distribution alliances, or out‑licensing to incumbents with hospital reach can accelerate uptake while de‑risking capital exposure.
How PW Consulting’s report helps you execute
This research is designed as an execution primer for 2026: a quantitative forecast that delineates upside bands, a competitor and event tracker that identifies windows of vulnerability and opportunity, and modular playbooks that convert insights into board‑level decisions. We deliver both the numbers leaders need to justify investments and the tactical blueprints required to operationalize strategy — without diluting negotiating leverage by publishing raw segment‑level figures in this preview.
If your 2026 plan includes portfolio rationalization, in‑licensing, or bets on novel antifungal mechanisms, our report will show you where to allocate capital, which clinical proofs to prioritize, and how to structure commercial partnerships to capture disproportionate market value.
Next steps
-
Request the full report to access detailed regional and segment-level forecasts, scenario modelling outputs, and the complete competitive datasets that underpin our recommendations.
-
Engage with PW Consulting for a tailored workshop: we can overlay your product, pipeline and balance sheet to identify the highest‑value near‑term moves for 2026.
In a market growing at an annual clip of 6.5% and approaching multi‑billion‑dollar scale over the coming decade, the difference between leading and lagging organizations will be determined by strategic timing, supply resilience, and a focused evidence generation plan. PW Consulting’s Worldwide Aspergillosis Drugs Market report provides the foresight and the playbooks to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Aspergillosis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com