

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Coated Fabrics for Defense Market to Rise from USD 730 Million in 2025 to USD 1.11 Billion by 2032 at a 6.19% CAGR

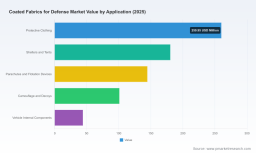
Worldwide Coated Fabrics for Defense Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Coated Fabrics for Defense synthesizes five years of historical data and a seven‑year forecast horizon to deliver an executive-grade roadmap for manufacturers, procurement leaders, and investors shaping defence textiles strategy in 2026. Built on a 2025 baseline and projecting through 2032 at a compound annual growth rate (CAGR) of 6.19%, the report combines a granular industry model, supplier‑level intelligence, and scenario playbooks designed to convert market insight into defensible action.
Worldwide Coated Fabrics for Defense Market
Why this report matters for 2026
- Strategic timing: defence procurement cycles, rising operational tempos in contested regions, and accelerated materiel modernization programs make 2026 a pivotal year to re‑position portfolios and supply chains.
- Market momentum: after a recovery and normalization period through 2024–2025, the coated fabrics market for defence is forecast to expand materially, creating runway for new entrants and premiumization moves by incumbents.
- Decision support: the report is explicitly structured to guide near‑term capital allocation, product roadmaps, and partnership choices without requiring clients to parse raw subsegment tables—enabling faster, higher‑confidence decisions.
What the report delivers — practical, executable intelligence
- Comprehensive market model: topline market sizing (2020–2025 history, 2026–2032 forecast), growth drivers, and sensitivity scenarios calibrated to commodity price pathways and geopolitical shocks.
- Actionable go‑to‑market playbooks: prioritized initiatives for OEMs, tier‑1 suppliers, and defence contractors (e.g., premium ballistic coatings, lightweight shelter systems, rapid‑deploy camouflaging textiles).
- Supplier and capability matrix: qualitative and quantitative profiling of the competitive set, technology roadmaps, and recommended procurement hedges tailored to defence certification cycles.
- Commercial and regulatory risk analysis: impact mapping for raw material volatility, MIL‑SPEC/Berry Amendment compliance, and export control regimes—plus mitigation options and timeline implications.
- M&A and partnership scoring: deal‑rationales, valuation sensitivities, and integration playbooks for bolt‑ons that accelerate access to protected markets or critical material technologies.
Market snapshot — growth and structure
Using 2025 as our base year, PW Consulting’s model anticipates steady expansion through the forecast period driven by modernization of personal protection, shelter systems, and multi‑functional platform interiors. The global market is expected to grow at a mid‑single digit pace (6.19% CAGR) over 2026–2032 — a trajectory that supports both volume plays (scale manufacturing, cost optimization) and differentiated premium plays (advanced polymers, multi‑functional laminates).
Worldwide Coated Fabrics for Defense Market
Concentration metrics indicate a market that is neither wholly consolidated nor atomized: the combined market share of the largest three and five suppliers points to meaningful competitive leaders alongside a sizeable mid‑tier and specialist supplier base. For commercial strategists, this dynamic creates space for specialist entrants and strategic consolidation, but also requires disciplined supplier selection and robust qualification programs.
Worldwide Coated Fabrics for Defense Market
Competitive landscape — what the leading names tell us
The competitive field in coated defence textiles reflects a mix of legacy manufacturers, polymer specialists, and technical textile innovators. Our report profiles a representative cross‑section of companies, assessing strengths and strategic intent across technology, certifications, and channels to market. Highlights include:
- The rubber specialists: Firms with deep expertise in rubber‑coated fabrics and high‑strength fibre integration continue to command premium positions in non‑metallic armour and equipment that demand high tear and ballistic performance.
- Polymer and vinyl leaders: Companies focused on synthetic rubber and vinyl coatings retain advantages in protective clothing and shelter materials through proven manufacturing scale and compliance with stringent defence standards.
- Technical textiles and composites houses: Providers that combine polymer science with advanced textile engineering are accelerating adoption in applications requiring multi‑functionality—camouflage, flame/chemical resistance, and reduced weight.
- Specialist shelter and marine fabric manufacturers: Longstanding producers of PVC‑coated woven fabrics and multi‑ply constructions remain critical to infrastructure and expeditionary logistics, often favored for reliability and lifecycle cost.
Each profile in the report includes strategic diagnostics: product differentiation, certification readiness (e.g., MIL‑SPEC, Berry compliance), export control posture, and recommended strategic moves for competitors seeking to compete or partner.
Key dynamics and risk vectors
- Raw material volatility: Petrochemical inputs (PVC, polyurethane, specialty additives) remain a primary cost driver. Our scenario analysis quantifies margin exposure to feedstock swings and outlines hedging and substitution strategies, including pathways to bio‑based and recycled chemistries where performance permits.
- Regulatory and procurement standards: Military specifications and national sourcing rules (including Berry Amendment consequences for U.S. procurement) materially shape supplier selection and time‑to‑market. The report provides a compliance checklist and a timeline‑aware certification playbook.
- Geopolitical demand elasticity: Elevated defence spending in contested regions is increasing demand for lighter, multi‑functional coated fabrics. We model demand upticks under a range of geopolitical intensification scenarios to help planners size surge capacity and reserve inventories.
- Technology substitution and performance creep: Advances in high‑strength fibres, PTFE and multi‑layer laminates are narrowing tradeoffs between protection and weight. The study outlines how R&D pacing, IP strategy, and collaborative testing regimes can secure first‑mover advantages.
Strategic implications — concrete moves for 2026
For executives planning 2026 budgets and roadmaps, the study identifies a prioritized set of actions designed for immediate implementation and measurable impact over 12–36 months:
- Supply chain resilience: Establish dual‑sourcing for critical polymer inputs, implement vendor scorecards tied to certification readiness, and invest in short‑term inventory buffers for key feedstocks where cost of disruption exceeds holding costs.
- Product portfolio triage: Re‑allocate R&D and production capacity toward high‑growth, high‑margin microsegments—those demanding multi‑functionality and certification—and sunset lower‑margin commoditized SKUs that tie up capacity.
- Certification and compliance acceleration: Fast‑track MIL‑SPEC and Berry Amendment pathways for products intended for U.S. procurement via dedicated test labs and partnered qualification projects to reduce bid timelines.
- Partnerships and M&A: Targeted acquisitions of niche technical textile houses or polymer coating specialists can close capability gaps faster than in‑house development. The report provides a prioritization framework and valuation sensitivities for likely bolt‑ons.
- Sustainability and cost pivot: Where performance permits, pilot recycled or bio‑based polymer blends to diversify raw material exposure and position offerings for lifecycle cost advantages in long‑term defence contracts.
Operational playbook — from insight to execution
PW Consulting equips clients with tactical instruments to convert the market intelligence into executable programs:
- Supplier heatmaps and risk dashboards to prioritize qualification and contingency planning.
- Scenario revenue models that link commodity price pathways and procurement lead times to margin outcomes for product portfolios.
- M&A screening templates and integration checklists tailored to textile manufacturing and coating operations.
- Regulatory compliance trackers aligned to major defence procurement authorities to minimize bid rejection risk.
Recent developments shaping 2026 strategy
Two sector signals underscore the near‑term opportunity and urgency. First, industry briefings hosted by defence logistics authorities in early 2026 underscore an active demand pipeline and accelerated clothing/textiles requirements that will shorten procurement horizons for qualified suppliers. Second, positioning by advanced textile and composite groups during 2025 and 2026 highlights an industry movement toward integrated solutions—combining polymer science, textile engineering, and system‑level comfort/protection tradeoffs.
How to use this report — executive checklists
- CEOs and boards: Use the market model and M&A scoring to validate growth or consolidation capital plans for 2026–2027.
- Heads of product and R&D: Prioritize development sprints that close the top three capability gaps identified for multi‑functional defence textiles.
- Procurement and supply chain leads: Implement the supplier heatmap and raw material stress‑test to set dual sourcing thresholds and inventory triggers.
- Business development and capture teams: Align certification timelines to bid calendars and use our compliance playbook to shorten qualification lead times.
Conclusion — the strategic window for 2026
As defence programmes recalibrate to evolving operational needs and procurement timelines compress, coated fabrics suppliers face both a commercial opportunity and an operational test. The market’s projected mid‑single digit CAGR and the competitive structure documented in our study create simultaneous incentives for investment in high‑performance materials and vigilance against input cost volatility and regulatory friction. For organisations that act deliberately in 2026—shoring up certified capacity, pivoting portfolios toward differentiated offerings, and using strategic partnerships to accelerate capability—the rewards include deeper share in expanding defence supply chains and improved contract win rates.
PW Consulting’s Worldwide Coated Fabrics for Defense Market report is designed as the decision‑grade toolset to make those moves with confidence. For a full breakdown of segment dynamics, supplier profiles, scenario models, and the proprietary data tables that underpin our conclusions, visit our report page to access the complete study and supporting downloads.
For detailed analysis of this topic, please visit the official page: Worldwide Coated Fabrics for Defense Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com