

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Universal Milling Machine Market Set for a 5% CAGR, Accelerating Global Manufacturing Growth

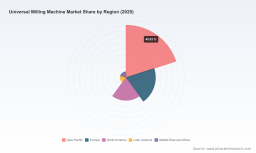
Worldwide Universal Milling Machine Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Universal Milling Machine Market delivers a pragmatic, decision-ready view for executives preparing capital and product strategies in 2026. Built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon, the report frames the market’s trajectory from a 2025 base year into a medium‑term growth path at a 5.0% compound annual growth rate (CAGR). Our modelling projects clear revenue expansion through 2032, providing the quantitative backbone leaders need to validate investment timing, portfolio prioritization, and service economics.
Worldwide Universal Milling Machine Market
Why this report matters for 2026 strategic planning
- Investment timing: Our 2026 baseline and multi‑year forecast let CFOs and CAPEX committees test scenarios for machine replacement cycles, capacity build‑outs, and automation projects against an evidence‑based demand curve.
- Product and R&D prioritization: Engineers and product teams gain insight into which technological envelopes — multi‑axis capability, high‑speed spindles, hydrostatic systems, or advanced controls — will materially influence market differentiation.
- Service and aftermarket monetization: The report quantifies the strategic upside of service models and parts businesses, guiding commercial teams to structure recurring‑revenue offers with precise unit economics.
- M&A and partnership screening: Corporates and PE firms can triage targets using our concentration metrics and capability heatmaps to identify consolidation plays and capability gaps.
Market trajectory and near‑term implications
The universal milling machine market is in a measured expansion phase. After solid base‑year activity, our forward view indicates a steady climb over the 2026–2032 forecast window consistent with the stated 5.0% CAGR. This growth is driven by a mix of new order generation in precision industries, continued modernization of legacy machine fleets, and incremental demand from reshoring and supply‑chain regionalization. The market’s competitive structure — with the top tier representing a meaningful, but not dominant, portion of industry revenues — points to both opportunity for scale players to accelerate share gains and room for niche specialists to defend profitable segments through technology differentiation.
Worldwide Universal Milling Machine Market
Key sector dynamics to monitor in 2026
- Material and mechanical fundamentals: High‑grade gray cast iron continues to anchor machine design because of its vibration damping and long‑term stability properties. This remains a critical specification vector when evaluating machine lifetime precision and service intervals.
- Control‑layer advancement: Adoption of modern CNC controls is a force multiplier for versatility. Recent product introductions featuring advanced control systems improve single‑part and small‑series economics and are shifting buyer expectations for flexibility and ease of programming.
- Heavy‑duty hydrostatic platforms: For large, precision, or continuous‑duty applications, hydrostatic guideways and bearing systems are increasingly presented as premium differentiators because of their thermal stability and negligible wear profiles.
- Industry 4.0 and connectivity: Machine builders that integrate diagnostics, remote service, and predictive maintenance data stacks create stronger service margins and higher switching costs.
- Trade‑show and product cadence: Major exhibitions continue to set the innovation calendar. Recent rollouts highlighted enhanced 5‑axis capabilities, ergonomics, and Industry 4.0 features — all signposts for where buyers will drive procurement decisions in 2026.
Competitive landscape — practical implications from our benchmarking
Our competitive assessment segments the market into several distinct strata: global premium OEMs with full technological stacks, regionally dominant and cost‑competitive suppliers, heavy‑duty specialists, and mid‑market OEMs focused on accessibility and service. Key representative players examined in the study include long‑established multinational OEMs known for high‑precision, 5‑axis systems; reputable regional manufacturers that offer value propositions for volume buyers; and specialist firms delivering hydrostatic, large‑component solutions.
Worldwide Universal Milling Machine Market
- Premium global OEMs: These firms lead on multi‑axis machining, high spindle speeds, and integrated automation. Their offerings target aerospace, premium automotive, and high‑precision industrial applications where uptime and accuracy command premium pricing.
- Regional and cost‑competitive suppliers: Companies in this group compete on configuration breadth and total acquisition cost for volume and general‑purpose manufacturing customers, enabling rapid fleet refresh programs in price‑sensitive markets.
- Heavy‑duty specialists: Makers of hydrostatic and large‑component machines focus on long life, low maintenance, and tight tolerancing for heavy industries — an attractive niche for buyers prioritizing lifecycle cost over initial capex.
- Service and aftermarket players: Firms able to deliver fast parts, remote diagnostics, and retrofit programs capture disproportionate lifetime value from installed bases.
Market concentration metrics evidence a market where the leading manufacturers hold sizable influence but do not preclude new entrants or consolidation. For decision makers this means that partnership, OEM channel design, and selective M&A remain viable strategies to gain capability or scale in 2026.
Recent product and event signals (what to watch)
- Major trade exhibitions in 2025 showcased the emphasis OEMs are placing on 5‑axis flexibility, ergonomic design, and integrated control systems — a clear directional signal for procurement roadmaps.
- Introductions of compact universal mills with advanced control suites illustrate a two‑front market: one for premium high‑performance machines and another for precision‑capable compact units optimized for workshop use.
- New hydrostatic heavy‑duty models brought to market reinforce the importance of material and design choices in defining total cost of ownership for large manufacturers.
Actionable recommendations for leaders in 2026
- OEMs (product strategy): Prioritize modular platforms that allow customers to pick spindle, control, and automation packages. This reduces time‑to‑market for variants and captures upsell opportunities.
- Service teams: Build subscription‑style maintenance offerings anchored on remote monitoring and predictive parts replenishment; small improvements in uptime translate to outsized aftermarket revenue.
- Corporate development: Use concentration metrics and capability heatmaps from the report to identify M&A targets that fill gaps in controls, hydrostatic expertise, or regional aftersales footprints.
- Procurement and operations: Reassess supplier contracts for cast‑component inputs and long‑lead assemblies, and qualify second‑source suppliers to mitigate single‑supplier risk for critical materials.
- Customer (end‑users): When planning fleet upgrades in 2026, adopt a two‑track approach: selectively invest in premium units for precision needs while deploying compact, high‑productivity machines for job‑shop and small‑series work.
What the report delivers — practical components
- Multi‑scenario demand forecast through 2032 (anchored to a 2025 base and a 5.0% CAGR assumption) to stress‑test CAPEX and service revenue planning.
- Executive decision frameworks and CAPEX modelling templates for prioritizing machine types and retrofit versus replace decisions.
- Competitive scorecards, capability heatmaps, and a regulatory/standards checklist to accelerate partner diligence.
- Go‑to‑market playbooks for aftermarket monetization, retrofit programs, and digital services rollout.
- Supply‑chain risk matrix and supplier qualification criteria focused on castings, precision components, and control‑system dependencies.
How to convert insight into action in the first 90 days
- 0–30 days: Validate internal assumptions against our baseline forecast and concentration indicators; prioritize candidate SKUs and aftermarket bundles for immediate commercial testing.
- 30–60 days: Run targeted supplier risk audits, accelerate integration pilots for advanced controls on a selected machine line, and prepare a short list of M&A/partnership targets informed by the report’s heatmaps.
- 60–90 days: Launch a service subscription pilot, commit to a retrofit roadmap for installed‑base monetization, and adjust 2026 CAPEX plans based on scenario outcomes from the forecast models.
PW Consulting’s study is expressly designed to be a working tool for 2026 — not just a descriptive document. Our combination of quantitative forecasting, event‑level intelligence, control‑layer analysis, and practical playbooks enables executives to move from insight to execution with confidence.
For full access to the proprietary segment breakdowns, exhaustive company profiles, and downloadable modelling templates that accompany this briefing, visit the report page to request the complete dataset and the executive workshop package.
For detailed analysis of this topic, please visit the official page: Worldwide Universal Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com