

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Semiconductor Memory IP Market to Grow at 14.0% CAGR, Forecast to Reach USD 3,917.49 Million by 2032

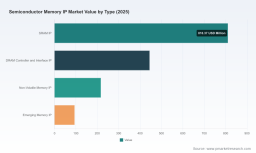
Worldwide Semiconductor Memory IP Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Semiconductor Memory IP market synthesizes hard data, near-term shocks, and strategic scenarios into a pragmatic playbook for executives making resource-allocation and M&A decisions in 2026. Our analysis covers a historical window (2020–2025), sets 2025 as the base year, and delivers a detailed forecast through 2032. At a macro level the market is expanding rapidly — driven by AI workloads, memory-interface complexity at advanced nodes, and a wave of product diversification — with an estimated compound annual growth rate (CAGR) of 14.0% across the 2026–2032 forecast horizon.
Worldwide Semiconductor Memory IP Market
Market snapshot: a high-growth, concentrated market
The Memory IP market has demonstrated sustained growth over the past half-decade and transitions into a structurally larger opportunity set in 2026. PW Consulting’s model captures a continued acceleration in total industry revenue through 2032, reflecting both higher average selling prices for advanced memory interface IP and expanded addressable demand from AI/data-center and new edge/automotive use cases. Market concentration metrics indicate meaningful leader advantage — the top three suppliers command a sizable portion of market share, and the top five further consolidate industry power — a dynamic that amplifies both competitive pressure and the strategic value of select partnerships or acquisitions.
Worldwide Semiconductor Memory IP Market
Why this matters for 2026 strategic planning
-
Accelerated investment calculus: At a double-digit CAGR, memory IP is no longer a defensive niche — it is an investment priority for SoC vendors, foundries, and IP houses aiming to capture AI-driven ASP expansion and to secure interface compatibility for next-generation memory (e.g., HBM and DDR7).
Worldwide Semiconductor Memory IP Market -
Supply-chain risk becomes strategy: Raw-material export controls and commodity price shocks observed in 2025 have elevated supply-chain risk into a board-level issue that intersects IP strategy (sourcing of embedded NVM, foundry readiness) and procurement policies.
-
Regulatory and procurement constraints are material: Proposed procurement rules and export-control policy moves create new compliance constraints that will reshape sourcing decisions, especially for companies with significant U.S. federal procurement exposure or China-dependent supply chains.
Key industry dynamics shaping 2026 outcomes
-
AI-driven memory demand: High-performance memory subsystems (HBM generations, upgraded DDR) for AI training and inference are placing asymmetric pressure on both interface IP and embedded memory stacks, producing scarcity in some consumer-oriented memory categories and lifting average selling prices in 2025–2026.
-
Critical-material supply shocks: Export control actions and licensing requirements among major raw-material suppliers have led to dramatic price moves for certain commodities used in semiconductor manufacturing, creating both cost inflation and geographic risk that must be hedged.
-
Consolidation & capability integration: Strategic M&A and selective, capability-focused acquisitions (notably in embedded memory compilers and foundation IP) are reshaping vendor roadmaps and raising the strategic premium on scale, foundry co-optimization, and PPA (power-performance-area) toolchains.
What our report contains — practical, transaction-ready deliverables
-
Proprietary market model: an audited top-down and bottom-up forecast through 2032, scenario variants for demand shock, regulatory restriction, and technology-opportunity pathways.
-
Vendor scorecards: capability, process-node coverage, foundry partnerships, licensing models, and a risk-adjusted view of commercial terms — designed to support vendor selection, sourcing negotiations, and M&A diligence.
-
Technology roadmap and IP migration playbook: guidance for migrating embedded memory implementations across nodes, incorporating non-volatile options, and aligning PHY/controller choices with SoC power and area targets.
-
Supply-chain & geopolitical stress tests: a matrix of supplier dependencies, critical-material exposures, and mitigations — from dual-sourcing and buffer stock strategies to localization and onshore manufacturing options.
-
Go-to-market & licensing frameworks: recommended contracting approaches (fixed-fee, royalty, hybrid), integration checklists, and timing guidance for licensing versus internal development decisions.
-
M&A playbook: valuation sensitivities, target screening criteria, and integration checklists tailored to capture embedded memory compilers, interface-IP suites, and specialty NVM assets.
Competitive landscape — practical implications for partners and rivals
Our competitive analysis synthesizes vendor capabilities, recent transactions, and strategic direction into actionable insights for acquirers, licensees, and ecosystem partners.
-
Synopsys — a leader in silicon-proven embedded memory IP and PPA optimization. Synopsys’s deep integration with advanced foundry process design kits and broad compiler portfolio make it a default partner for teams prioritizing node migration and performance validation. Strategic implication: prioritize engineering alliances for early access to silicon-proven compilers and negotiate cross-licensing terms that include co-optimization support.
-
Cadence — with its acquisition of a major foundation-IP business in 2025, Cadence has consolidated significant embedded memory compiler and foundation IP capabilities. This deal raises the bar on integrated toolchain offerings and puts pressure on mid-sized IP houses. Strategic implication: anticipate bundled offerings and consider counter-offers via partnerships or targeted acquisitions to preserve bargaining leverage.
-
Arm — continues to embed memory IP into broader processor/IP platforms with emphasis on power efficiency. Arm’s positioning matters most for partners pursuing differentiated, low-power edge devices and mass-market SoC designs. Strategic implication: evaluate joint-optimization licensing that pairs processor IP with embedded memory stacks to shorten time-to-market.
-
Rambus — specializes in high-speed memory interface IP and security for memory subsystems. For companies targeting HBM and next-gen DDR, Rambus’s end-to-end interface solutions reduce integration risk. Strategic implication: lock in PHY/PHY-controller roadmaps early for AI-centric designs where interface maturity is a gating factor.
-
Specialists and regional players (including NVM innovators and foundry-aligned IP firms) — these vendors provide differentiated technology (e.g., embedded NVM, MRAM), regional market access, or cost-competitive alternatives. Strategic implication: maintain a tiered supplier strategy that blends global leaders for critical high-performance IP and specialists where niche differentiation or local foundry alignment matters.
Recent market moves to monitor
-
Strategic acquisitions that consolidate foundation IP and embedded memory compilers have accelerated — expect continued deal activity as platform providers seek to offer stitched toolchains and locked-in eco-systems.
-
Awards and foundry recognition for specialty embedded memory providers highlight the value of being qualified inside advanced foundry OIP programs — a key commercial moat for smaller NVM innovators.
-
Regional licensing deals and IP agreements for automotive-grade platforms show that reliability- and process-certified IP is becoming table-stakes for critical verticals such as automotive and industrial.
Recommended actions for 2026 — prioritized and time-bound
-
Q1–Q2 2026: Conduct a vendor dependency audit. Map critical IP vendors to product roadmaps and procure legal-compliant clauses to address export-control risk and supply fallbacks.
-
Mid-2026: Define a two-track R&D vs. licensing decision framework. For capabilities core to differentiation (e.g., proprietary memory macros optimized for your IP portfolio), accelerate internal development; for commodity interface IP, favor licensing and fast integration.
-
H2 2026: Execute strategic hedge moves. Negotiate multi-year licenses with pricing collars for volatile components, secure foundry-aligned IP bundles, and explore minority investments or JV with specialized NVM providers to secure roadmap exposure.
-
Ongoing: Embed regulatory scenario planning into procurement. The evolving U.S. procurement rule proposals and export-control regimes require ongoing legal and sourcing oversight to avoid disruptive delists or procurement disqualifications.
How PW Consulting’s deliverables accelerate your decisions
Our report reduces execution risk by packaging data, vendor intelligence, and executable playbooks into a single decision-ready asset. Clients receive:
-
an editable financial model to run bespoke scenarios;
-
vendor negotiation templates tailored to common IP licensing models;
-
a prioritized investment map linking technology bets to revenue capture timelines;
-
a regulatory-impact heat map that ties procurement exposure to product roadmaps.
Final note — what’s in the public briefing vs. the full study
This briefing presents the high-level growth trajectory, concentration dynamics, and strategic recommendations you need to set 2026 priorities. To preserve the commercial value of our primary research and to support negotiated access to vendor-level scorecards, the full study includes detailed segment-level breakdowns, region-by-region models, and supplier contract intelligence. Those datasets — including granular splits by memory type, application, and region — are intentionally reserved for subscribers and licensed purchasers.
To access the full forecast models, interactive vendor scorecards, and the PW Consulting playbook for Memory IP strategy execution in 2026, visit our report page or contact PW Consulting’s semiconductor practice lead for a briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Memory IP Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com