

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ultra‑low Alpha Metal Market Set to Surge at a 13.52% CAGR, New Report Reveals

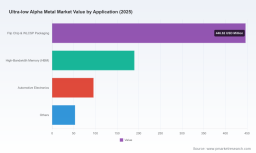
Worldwide Ultra-low Alpha Metal Market — Strategic Outlook for 2026 Decisions
Executive summary
PW Consulting’s new market study on the Worldwide Ultra-low Alpha Metal Market positions this specialty segment as a strategic raw-material frontier for semiconductor packaging and high-reliability electronics. The market has moved from a niche reliability play into a critical supply-chain consideration: global market value rose from USD 412.35 Million in 2020 to USD 785.4 Million in 2025, and our base-year analysis projects an immediate uplift to approximately USD 880.65 Million in 2026. Over the 2026–2032 forecast window the market expands at a compound annual growth rate (CAGR) of 13.52%, approaching USD 1.908 Billion by 2032. For executives planning 2026 capital, procurement, or technology strategies, these trajectories are not academic — they drive decisions on capacity, supplier partnerships, contamination control protocols, and R&D prioritization.
Worldwide Ultra-low Alpha Metal Market
Why this study matters for 2026 strategic decisions
-
Demand inflection: The convergence of 3D IC stacking, HBM-class memory, flip-chip/WLCSP packaging and automotive-grade electronics is shifting ultra-low alpha metal from a specialized procurement line-item to a strategic input that affects yield, warranty risk, and product differentiation. Buying managers should treat availability and emission performance as value drivers, not only cost variables.
Worldwide Ultra-low Alpha Metal Market -
Concentrated supply base: The market exhibits high concentration at the top — our analysis shows that the leading three and five suppliers collectively control a significant majority of accessible capacity. This concentration magnifies the commercial impact of single-facility outages, refinery incidents, or sudden shifts in purity specifications.
Worldwide Ultra-low Alpha Metal Market -
Regulatory and sustainability overlay: Compliance to RoHS and halogen-free mandates sits alongside customer-driven requirements for traceability and recycled content. Buyers in 2026 will increasingly evaluate suppliers on mine-to-product traceability, reclamation programs, and demonstrable contamination control rather than unit price alone.
What the report delivers — practical content for action in 2026
-
Integrated market model and scenario suite: A base-case, upside and downside demand model tied to packaging adoption curves and memory roadmap variants. Scenarios quantify the timing and size of potential supply gaps so teams can stress-test sourcing and inventory policies.
-
Supplier scorecards and procurement playbook: Vendor profiles mapped against reliability KPIs (alpha emission performance, process stability, product forms), commercial terms, geographic footprints and traceability credentials. Negotiation playbooks include contract language templates to secure capacity, agree on quality gates, and protect against contamination liabilities.
-
Operational protocols: Standardized sampling, lab verification methods and shelf-life handling guidelines that reduce soft-error exposure and ensure secular-equilibrium guarantees in long-lead ingots, anodes and powders.
-
Capex & investment guidance: A decision framework for build-versus-buy, including simple NPV sensitivity tables that model new low-alpha refining lines, reclamation units and dedicated production trains — critical input for 2026 budget cycles.
-
Risk heatmap and mitigation playbook: Scenario-based mitigation tactics for contamination events, logistics bottlenecks, and demand surges — from dual-sourcing templates to inventory stratification and molecule-level impurity controls.
Competitive landscape — what the supplier dynamics mean for buyers
Our executive-level supplier analysis synthesizes technical capability, market position, and recent commercial moves. Highlighted companies include well-established metallurgical groups, vertically integrated refiners and specialty chemical players. Strategic takeaways:
-
Pure Technologies (Tequesta, USA) — a technical leader in achieving sub-0.001 counts/hr/cm² emission rates with ultra-high-purity tin offerings. Their emphasis on guaranteed secular equilibrium and multiple product forms (ingots, anodes, powders) makes them an attractive partner for customers with stringent qualification windows and low tolerance for supply variance.
-
Teck Resources (Vancouver, Canada) — operates a dedicated low-alpha production facility and brings the traceability and scale of a primary miner-refiner. For manufacturers weighting mine-to-product transparency and long-term offtake security, vertically integrated suppliers like Teck reduce exposure to upstream contamination risk.
-
MacDermid Alpha Electronics Solutions (USA) — has doubled down on a locally-sourced, reclamation-enabled supply strategy and recently launched a new low-alpha tin portfolio with ultra-low emission specifications. Their geographically proximate model supports risk-averse procurement strategies that prioritize shorter lead times and domestic reclamation pathways.
-
Mitsubishi Materials, DUKSAN Hi-Metal, JX Advanced Metals, Honeywell and Indium Corporation — each contributes a mix of proprietary refining know-how, chemistry portfolios and product forms that address different reliability and commercial trade-offs. Buyers should map each supplier’s technical envelope (purity, impurity control, emission stability) to their device reliability thresholds rather than defaulting to price-based sourcing.
Key technical and sourcing considerations for 2026
-
Alpha-emission performance is a functional spec: Equivalent cost items are not fungible if emission rates affect soft-error budgets. Procurement must include alpha-emission metrics in acceptance criteria and plan for qualification lead times.
-
Traceability and contamination controls: The primary alpha source in tin is trace 210Pb contamination. Suppliers who can demonstrate Pb control to sub-ppm levels and provide mine-to-product traceability materially lower integration risk for high-density devices.
-
Local supply and reclamation: Vertical or regional supply chains that include reclamation loops reduce dependence on long-tail logistics and provide resilience against geopolitical and transport shocks — a factor that should be given weight in 2026 supplier scorecards.
-
Concentration risk: Given high market concentration among leading suppliers, companies should adopt a layered sourcing strategy — primary strategic partners plus vetted alternate suppliers and contractual first-rights for capacity expansion.
Regulatory, sustainability, and quality dynamics
Materials in this market are already produced to high-purity standards and must comply with RoHS and other semiconductor industry mandates. Beyond compliance, customers are increasing scrutiny of lifecycle environmental footprint and reclamation practices. In 2026, procurement teams will be judged not only on cost savings but on their ability to secure quality-compliant metals while meeting sustainability KPIs and reducing total cost of failure across product life cycles.
Recommended 2026 playbook for corporate leaders
-
Reclassify ultra-low alpha metals as strategic purchased components: Move them into the same governance as semiconductor die or advanced substrates. Establish cross-functional steering teams (procurement, reliability, packaging engineering) to fast-track qualifications.
-
Implement a three-tier sourcing strategy: secure a primary capacity partner with proven emission guarantees, maintain a validated secondary supplier for spot contingencies, and invest in an internal or consortium reclamation capability where feasible.
-
Shorten qualification cycles: partner with suppliers on joint qualification protocols, including shared lab access, audited sampling procedures, and pilot-quantity releases tied to production ramp milestones.
-
Model capex triggers: use the report’s scenario outputs to define explicit capex triggers for vertical investment or long-term offtake agreements based on demand thresholds and price-implied stress levels.
-
Embed sustainability and traceability in contracts: require mine-to-product reporting, reclamation commitments, and clear provisions for contamination remediation and liability coverage.
How PW Consulting’s report supports board-level and commercial execution
Our study is designed as a decision-useful tool for the 2026 planning cycle: it translates market dynamics into procurement contracts, capex tests, and quality controls. The report provides the commercial tables, supplier scorecards and scenario models that teams can drop into board packs and procurement RFPs. We deliberately structured the deliverables to close the gap between strategy and execution: from high-level investment thresholds to line-item inspection protocols.
Next step — where to get the data you need
This press release highlights the strategic implications and the types of operational playbooks contained in the full study. The complete report contains the detailed segmentation matrices, supplier-by-form price forecasts, regional demand modelling and downloadable scenario spreadsheets that organizations require to finalize 2026 strategies. For access to the full dataset, supplier appendices and procurement templates, please consult the PW Consulting report page or contact your PW Consulting advisor to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra-low Alpha Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com