

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Boiling Water Reactors Market Poised for 4.33% CAGR over 2026–2032, Report Finds

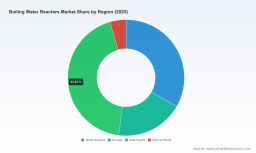
Worldwide Boiling Water Reactors Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive summary
PW Consulting's new market study on the Worldwide Boiling Water Reactors (BWR) market synthesizes five years of historical performance and a seven-year outlook to 2032, equipping corporate leaders and public-sector planners with the intelligence needed to make high-stakes decisions in 2026. The market is positioned for steady expansion from a 2025 base of approximately USD 3.34 billion (revenues expressed in USD million) at a compound annual growth rate (CAGR) of 4.33% through the forecast window. That trajectory reflects a convergence of technology maturity, renewed policy incentives in several markets, and early commercial traction for small modular and simplified BWR designs.
Worldwide Boiling Water Reactors Market
Why this matters for 2026 decisions
-
Capital allocation: With nuclear projects moving from feasibility to procurement in multiple jurisdictions, 2026 will be the year when capital commitments crystallize. Our report translates market growth assumptions into decision-ready capex timing and financing scenarios.
Worldwide Boiling Water Reactors Market -
Vendor strategy: The supplier base is highly concentrated and strategically shaped by a few global incumbents and JV structures. Choosing the right vendor architecture—licensed technology, EPC partnerships, or turnkey procurement—will materially affect schedule risk and lifecycle costs.
Worldwide Boiling Water Reactors Market -
Supply-chain resilience: Fuel, critical components and skilled labour are emerging as bottlenecks. Operational decisions in 2026 should prioritize contractual levers and dual-sourcing arrangements that our analysis shows materially mitigate delivery and price volatility.
-
Regulatory timing: Recent international and national regulatory developments are altering project timelines and technical specifications. Integrating those shifts into licensing and siting plans will be essential to avoid costly redesigns and delays.
Headline market dynamics driving the outlook
-
Policy tailwinds: Investment tax incentives and other direct support mechanisms in key markets are improving project economics for new nuclear capacity, making BWR deployments more bankable. These incentives change the risk-return calculus and accelerate procurement windows for early movers.
-
Technology evolution: Advances in simplified and small modular BWR designs are reducing upfront construction complexity and shortening project schedules. Early site selections and regulatory approvals for modular BWRs have moved the technology from concept to demonstrator and early commercial deployment stages.
-
Raw-material volatility: Uranium markets tightened in recent periods, causing spot-price spikes that directly influence fuel cost projections and long-term contracting strategies. Strategic procurement and inventory strategies are now essential inputs to any lifespan-cost model.
-
Regulatory and safety guidance: Updated international safety guidance and seismic design standards are reshaping engineering baselines for new projects, with implications for both capex and consenting timelines.
Competitive landscape — who matters and why
The BWR market is shaped by established reactor vendors and their integrated ecosystems. Industry-leading archetypes include global suppliers who combine design ownership, fuel supply relationships, and comprehensive aftermarket services. The competitive map shows a small set of firms capturing a dominant share of market activity; strategic differentiation rests on modularization, licensing footprint, and the ability to bundle engineering, procurement and long-term services into financing-friendly packages.
-
GE Hitachi Nuclear Energy (Wilmington, NC, USA): As a primary global supplier, GEH is advancing both simplified and small modular BWR variants. Recent program milestones — including regulatory design approvals and early construction activity — materially de-risk their small modular reactor pathway, improving availability and schedule predictability for adopters (e.g., approvals and first concrete milestones announced in 2024).
-
Hitachi-GE Nuclear Energy, Ltd. (Tokyo, Japan): The joint-venture structure positions it to deliver advanced BWR designs and life-cycle services across multiple national fleets. Their integrated engineering and outage-management capabilities make them a compelling partner for utilities prioritizing fleet-level performance and modernization.
-
Toshiba Energy Systems & Solutions Corporation (Tokyo, Japan): A long-standing developer and maintainer of ABWR technology, Toshiba remains relevant for operators pursuing established, large-unit ABWR platforms and modernization programs that emphasize continuity of fuel and operational practices.
Recent firm-level events signal a practical transition from design and approvals to site-level activity and procurement. Examples include regulatory design approvals, selection for potential multi-unit deployment sites, and first-concrete milestones at demonstrator projects. These events compress schedule risk for adopters in selected markets and create new windows for strategic procurement.
Key regulatory, market and supply considerations for 2026
-
Fuel security: Geopolitical shifts have prompted policy responses aimed at securing domestic or allied uranium supplies. For project sponsors this means that fuel sourcing strategies and long-term contracts will increasingly be evaluated for political as well as commercial risk metrics.
-
Incentive alignment: Public support mechanisms that recognize nuclear as a decarbonization technology materially affect the cost of capital and investor appetite. Where investment tax credits and similar incentives are available, they convert marginal projects into bankable opportunities.
-
Standards and resilience: International revisions to seismic and safety guidance require projects to revisit baseline assumptions. The implication for 2026 planning is a need to allocate contingency early in design and to validate compliance pathways with regulators before entering long-lead procurements.
-
Market concentration: A concentrated supplier landscape simplifies oversight but raises counterparty risk. Sponsors must weigh the benefits of working with incumbent vendors against potential pricing power and single-source exposures.
What our report delivers — practical intelligence for executives
PW Consulting's market study is built as an actionable toolkit. It does not merely describe trends; it prescribes decisions and operational actions for the 2026 horizon. Key deliverables include:
-
Quantified market trajectory and scenario-aligned forecasts to 2032, including base, accelerated deployment, and downside cases that map to policy and commodity contingencies.
-
Vendor scorecards and capability matrices that assess technology maturity, licensing footprint, and supply-chain integration (note: the public summary intentionally omits granular scorecard scores; full vendor profiles are available in the report).
-
Procurement playbooks covering contract structures, risk allocation, and schedule-acceleration levers tailored to different buyer archetypes (utility, government-led program, or merchant investor).
-
Supply-chain stress tests and fuel procurement models that translate uranium-price volatility and source-availability scenarios into cash-flow and operational risk outcomes.
-
Regulatory roadmaps that align international standard revisions with national permitting milestones, including a checklist to reduce rework exposure from updated seismic and safety guidance.
-
Financing and economic models that integrate investment incentives, tax credits, and potential revenue streams from grid services — enabling optimized project structures for 2026 bid windows.
-
Risk matrices and mitigation options covering technological, political, and market risks, with specific recommendations on insurance, guarantees, and contractual instruments.
Practical next steps for 2026 planning
-
Adopt a decision calendar: Convert development timelines into a 24–36 month decision calendar that aligns site preparation, long-lead procurement, and regulatory filings with prospective incentive expirations.
-
Lock-in critical long-lead items: Prioritize contracting for long-lead components and fuel frameworks in advance of final investment decisions to mitigate price and delivery risks.
-
Engage vendors earlier and in structured phases: Use staged procurements and conditional contracts to preserve competitive tension while shortening vendor selection timelines.
-
Stress-test financing models against incentive scenarios: Build alternative financing structures that capture available investment tax credits and public support mechanisms to lower capital costs and accelerate sponsor-level approvals.
-
Integrate regulatory-update triggers: Build explicit contingency triggers in project plans to accommodate updated safety and seismic standards without derailing schedules.
How to use the full PW Consulting study
This preview is intended to demonstrate the depth and practical orientation of our analysis while reserving the detailed segmentation tables, vendor ratings, and proprietary financial models for the full report. Executive teams preparing RFPs, finance committees evaluating bid packages, and government agencies designing support frameworks will find the full report particularly valuable.
Closing perspective
The BWR market is entering a more transactional phase: from strategic discussions to procurement and execution. For 2026, the primary strategic imperatives are timing, supplier engagement, fuel and component risk mitigation, and regulatory alignment. Sponsors who structure decisions around these imperatives and leverage scenario-based financial models will be best positioned to capture value as the market expands at a steady mid-single-digit CAGR and early modular deployments begin to deliver demonstrable outcomes.
To obtain the complete study — including the detailed segment tables, vendor scorecards, full scenario models and procurement templates — visit PW Consulting’s report page (full access required). Our analysts are available for briefings and bespoke workshops to translate the research into client-specific action plans for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Boiling Water Reactors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com