

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Copper‑Beryllium Alloys Market to Expand at a 5.6% CAGR Through 2032

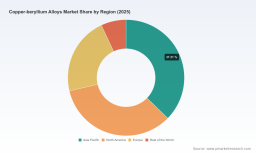
Worldwide Copper‑Beryllium Alloys Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on Worldwide Copper‑Beryllium Alloys delivers a focused, practice‑oriented intelligence package designed to inform capital allocation, sourcing, product development, and regulatory compliance decisions as companies plan for 2026 and beyond. The global copper‑beryllium alloys market has expanded materially over the 2020–2025 period, rising from approximately USD 1.05 billion in 2020 to roughly USD 1.44 billion in 2025, and our baseline forecasts project continued expansion to about USD 2.10 billion by 2032 at a compound annual growth rate (CAGR) of 5.6% across the 2026–2032 forecast window. Those topline trends frame an operating environment where demand drivers, supply bottlenecks, and regulatory pressures converge to create both risk and opportunity.
Worldwide Copper-beryllium Alloys Market
Why this study matters for 2026 decision makers
-
Actionable intelligence, not just description: the report translates macro growth into executable choices — what to hedge, where to localize, when to invest in alternative materials, and how to price for durability and regulatory compliance.
Worldwide Copper-beryllium Alloys Market -
Risk‑first supply planning: with beryllium supply concentrated at a small number of mines and subject to recent policy changes, procurement and manufacturing leaders need a nuanced, scenario‑based sourcing strategy for 2026 that balances security, cost, and compliance.
Worldwide Copper-beryllium Alloys Market -
Regulatory integration into product roadmaps: occupational exposure limits and chemical hazard classifications are shifting certification, processing, and worker‑safety requirements — impacting capex timing and operating margins.
What the report contains (practical modules)
-
Executive decision playbook: prioritized actions for OEMs, alloy producers, distributors, and component fabricators with a step‑by‑step 18‑month roadmap and 36‑month strategic options tailored to different risk appetites.
-
Demand and price scenario models: three rigorously stress‑tested scenarios (Baseline, Supply‑Constrained Upside, and Regulation‑Driven Substitution) calibrated to macro demand drivers and unit‑cost sensitivity, with downloadable model inputs for client customization.
-
Supply‑chain resilience matrix: supplier concentration, logistics chokepoints, and substitution thresholds — an operational matrix that ranks mitigation levers (dual sourcing, strategic stocks, near‑sourcing, toll processing) by CAPEX/OPEX tradeoffs.
-
Regulatory compliance playbook: practical checklists, process maps, and cost impact estimates to align manufacturing and occupational health systems with prevailing standards: for example, permanent occupational exposure limits and chemical authorization regimes that materially affect permitted uses and handling procedures.
-
Technology roadmap and substitution assessment: mapping of existing alloy grades, process windows (forming, welding, heat treatment), and credible non‑beryllium alternatives — including their performance, cost, and certification implications for high‑value end markets.
-
M&A and partnership diagnostic: an acquisition screening tool that overlays market concentration metrics, capability gaps, and integration risk to help acquirers prioritize targets and integration agendas.
Industry dynamics to watch in 2026
-
Regulatory tightening is a material operational variable. Occupational limits for airborne beryllium exposure implemented in previous years require investment in air controls, monitoring, and medical surveillance — factors that increase unit processing costs and raise barriers for new regional entrants.
-
Hazard classification regimes and authorization requirements in major jurisdictions constrain use cases and accelerate the timeline for substitution in certain applications. Manufacturers must reconcile product specifications with authorization timelines or face market access delays.
-
Supply concentration and geopolitical controls elevate strategic sourcing risk. Global beryllium production is modest in scale and geographically concentrated, and export restrictions enacted by key countries have the potential to distort spot supplies and premiums in sensitive years.
-
Market structure favors a small set of established producers. Measured by concentration ratios, the top three players capture a substantial portion of global supply and the top five an even larger share — a dynamic that reinforces pricing power, speeds technology diffusion for market leaders, and amplifies the strategic value of access to metal production and melt/refining capacity.
Competitive landscape and strategic positionings
-
Materion Corporation (Mayfield Heights, Ohio, USA) — established product leadership across high‑performance alloys and a broad grade portfolio marketed to aerospace, electronics, and oil & gas customers. Materion’s strengths include certified production lines for critical grades, established qualification pipelines with Tier‑1 OEMs, and experience in compliance‑intensive manufacturing. For 2026, Materion’s playbook is likely to emphasize value‑added processing, services around qualification, and selective capacity investments to deepen long‑term supply agreements.
-
NGK Metals Corporation (Reading, Pennsylvania, USA) — a specialist in precision forms (strip, wire, rod, plate) with strong presence in connector and spring markets. NGK’s competitive advantages are form-factor expertise and customer intimacy within electronics and telecom segments. Strategic moves that we expect are contracting for assured feedstock, accelerating downstream processing partnerships, and expanding technical services that lower customers’ qualification hurdles.
-
Ulba Metallurgical Plant JSC (Ust‑Kamenogorsk, Kazakhstan) — a major source of beryllium‑containing alloys and semi‑finished products for export. Ulba’s position offers geographic diversification for buyers but also exposes it to commodity and trade policy risk. In 2026, Ulba and similar producers will be focal points for buyers seeking alternative supply lines and for partners aiming to secure semi‑finished capacity outside the largest consuming regions.
Strategic plays — tailored guidance for 2026
-
For OEMs (electronics, aerospace, defense): treat qualification timelines as a strategic asset. Accelerate material co‑development with suppliers, fund parallel testing of non‑beryllium alternatives for secondary applications, and build contractual clauses to share regulatory cost burdens across the supply chain.
-
For alloy producers and fabricators: prioritize capital allocation to containment and monitoring systems that meet the latest occupational limits; invest in certification and traceability that shorten buyer qualification cycles; and evaluate partnerships with primary metal producers to secure feedstock at negotiated volumes.
-
For traders and distributors: reconfigure inventory strategy from lean to buffer‑optimized in response to episodic export controls and mine production variability. Opportunistic warehousing in friendly jurisdictions combined with contractual hedges can protect margins while preserving service levels to critical customers.
-
For private equity and strategic investors: the sector’s high concentration and regulatory complexity favor buy‑and‑build strategies that combine process expertise with geographic diversification. Value creation is most likely from operational improvements in compliance, downstream integration, and platform consolidation of specialty forms.
Operational checklist for immediate implementation
-
Run a 90‑day sourcing stress test: identify single‑point failures, calculate cost to dual‑source, and quantify working capital required to hold critical months of coverage.
-
Audit compliance posture: confirm that ventilation, monitoring, worker training, and recordkeeping meet current jurisdictional limits and prepare authorization dossiers where required.
-
Initiate a substitution feasibility study for lower‑risk product lines: map performance delta, certification path, and customer acceptance thresholds.
-
Stress‑test pricing: model the pass‑through of increased handling and compliance costs under different contract types (fixed, index‑linked, and cost‑plus).
Why our methodology matters
PW Consulting combines primary supply‑chain interviews, confidential buyer surveys, plant‑level technical assessments, and reconciled trade and production data to deliver a market view calibrated to near‑term operational decisions. Our forecasts incorporate a layered approach: macro demand drivers, application‑level adoption dynamics, regulatory adoption timing, and supply disruptions. The result is a forecast path that is granular enough to inform procurement and product engineering choices while retaining the scenario flexibility needed under regulatory and geopolitical uncertainty.
Next steps & how to access the full study
This article highlights the report’s strategic value without disclosing the detailed segment and regional breakout analysis that clients rely on for execution. PW Consulting’s full Worldwide Copper‑Beryllium Alloys Market report includes interactive models, proprietary segmentation analytics, supplier scorecards, and a downloadable executable toolkit designed for integration into 2026 operating plans.
To obtain the complete report, the downloadable scenario models, and client‑only briefing sessions that translate these insights into a tailored 18‑month action plan, please visit PW Consulting’s reports page or contact our industry team directly. Our analysts will provide a confidential walkthrough that maps our findings to your specific exposure and strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Copper-beryllium Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com