

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hormonal Implants Market Poised to Grow at a 6.22% CAGR Through 2032, Led by Progestogen Implants

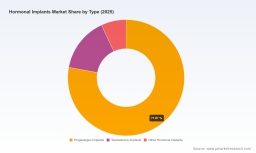
Worldwide Hormonal Implants Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market intelligence on the Worldwide Hormonal Implants market offers an operational playbook designed to inform executive decisions in 2026. The market is no longer a niche within reproductive and endocrine therapeutics; it is a growing, concentrated, and regulation-sensitive segment where clinical evidence, procurement models, and procedural logistics now determine winners and losers. Our preview highlights why boardrooms, corporate development teams, and market-access leaders should treat this report as a must-read planning input for the year ahead.
Worldwide Hormonal Implants Market
Market trajectory and what it means for strategic planning
Using a robust base year of 2025, PW Consulting estimates the global hormonal implants market at USD 1,152.4 Million (Revenue Unit: Million, Currency: USD). The market has expanded robustly from the early 2020s — growing from approximately USD 854 Million in 2020 to USD 1,152.4 Million in 2025 — and is forecast to continue on an upward path to reach USD 1,758.11 Million by 2032. That trajectory represents a compound annual growth rate (CAGR) of 6.22% across the 2026–2032 forecast horizon.
Worldwide Hormonal Implants Market
Two strategic implications are immediately apparent. First, the absolute growth rate signals sustained demand that supports both organic investment (clinical studies, lifecycle extensions, service models) and inorganic plays (bolt-on acquisitions, partnerships). Second, the moderate but consistent CAGR suggests that market share gains are achievable through differentiated non-price levers — quality of evidence, clinician enablement, and supply reliability — rather than pure price competition alone.
Worldwide Hormonal Implants Market
Market structure and competitive dynamics
Concentration metrics underline the strategic landscape. PW Consulting’s analysis shows a high degree of market concentration among the leading manufacturers, with the top three players controlling the large majority of the market and the top five firms further consolidating dominance. High concentration elevates the importance of product stewardship, regulatory strategy, and reputation management while leaving room for targeted challengers in specific procurement channels.
- Organon & Co.: As the primary manufacturer of the leading single-rod etonogestrel implant, recent regulatory developments have materially altered Organon’s strategic runway. A January 2026 label update extended the approved duration of use for their product to five years, underpinned by clinical evidence showing continued high effectiveness. This extension both increases lifetime value per patient and pressures competitors on clinical data generation.
- Bayer AG: With an established presence in public sector and donor-funded channels, Bayer’s multi-rod levonorgestrel system remains a backbone for large-scale procurement programs. Their strength is institutional pricing and distribution arrangements in low- and middle-income country (LMIC) tenders.
- Shanghai Dahua Pharmaceutical: Cost-focused two-rod alternatives are targeted at emerging markets and procurement tenders. Competitive entrants like Dahua demonstrate that pricing and supply predictability can open market access even when incumbent clinical brands dominate premium channels.
Between the three archetypes — high-evidence premium brands, procurement-oriented value players, and regionally focused low-cost manufacturers — the market is evolving into stratified value pools. Understanding which pool a product competes in is the first step to a defensible 2026 strategy.
Regulatory and procedural factors reshaping near-term dynamics
Recent regulatory actions in 2026 are reshaping the operating model for market participants and health systems alike. The U.S. Food and Drug Administration’s label revision extending approved duration for a leading etonogestrel implant materially changes the lifetime device economics and clinical counseling. Conversely, the introduction of a new Risk Evaluation and Mitigation Strategy (REMS) certification requirement for clinicians inserting or removing that implant — with a completion deadline in August 2026 — introduces an operational compliance burden that will affect provider adoption curves, training budgets, and procedural throughput.
These twin regulatory moves create a nuanced strategic calculus:
- Extended on-label duration increases product value-per-patient and reduces replacement procedures, benefiting brand loyalty and long-term retention metrics.
- New REMS training and certification creates a short-term barrier to clinic-level adoption; it will favor manufacturers and distributors with established clinician training infrastructure and those able to underwrite or subsidize certification programs.
- Payers and procurement bodies will reassess cost-effectiveness models in light of longer on-label durations, which may lead to revised reimbursement rules and tender specifications.
Reimbursement and coding realities
Operational reimbursement mechanics are increasingly strategic assets. In the United States, established billing pathways and HCPCS/CPT codes for implant devices and associated procedures create both an entry barrier and a lever for commercialization teams. Effective capture of correct codes and billing guidance, combined with provider education, materially affects time-to-revenue after launch or label changes.
What PW Consulting’s report delivers (practical, actionable content)
Our full report is intentionally constructed as an executable toolkit for 2026 decision-makers. It provides:
- Validated market sizing and seven-year forecasts (2026–2032) with scenario modeling that isolates the impacts of regulatory shifts, procurement cycles, and price pressure.
- Competitive benchmarking and company-level strategic profiles that include portfolio positioning, channel strengths, and recent clinical and regulatory milestones.
- Regulatory tracker and clinician workflow impact assessments — including compliance cost estimates tied to REMS-like requirements and training burdens.
- Reimbursement playbook: coding capture strategies, payer negotiation templates, and tender-response blueprints for both commercial and donor-funded programs.
- Go-to-market modules: segmented value propositions, KOL engagement plans, and digital enablement solutions to support insertion/removal workflows and patient follow-up.
- Supply chain and manufacturing risk heatmaps, including recommended mitigation actions for channel shortages and capacity constraints.
- An investor-focused annex with M&A thesis options, valuation sensitivities, and a shortlist of potential targets or acquirers aligned to specific strategic plays.
We deliberately designed the report for cross-functional use: corporate development teams, market-access leads, commercial operations, clinical affairs, and country-level business units can all extract operational next steps without re-working the analytics.
Strategic recommendations for 2026
Drawing from our analysis, PW Consulting recommends five prioritized actions for organizations operating in or entering the hormonal implants market in 2026:
- Prioritize lifecycle and evidence strategies: Invest in label-extension studies, real-world evidence initiatives, and patient-reported outcome research to maximize on-label duration benefits and defend price points.
- Operationalize clinician enablement: Launch REMS-compliant training programs, certification subsidies, and scalable digital training platforms to reduce adoption friction at the point of care.
- Segment commercialization by procurement channel: Differentiate pricing, packaging, and service bundles for public-sector tenders versus private-clinic channels; secure long-term supply agreements to win trust in tenders.
- Build integrated service propositions: Combine device supply with insertion/removal services, follow-up digital tools, and bundled reimbursement support to create stickier customer relationships and capture downstream value.
- Scan and act on consolidation opportunities: Use the market’s high concentration to pursue bolt-on acquisitions that add clinical capabilities, regional distribution, or cost-effective manufacturing to broaden addressable segments quickly.
Where PW Consulting adds unique value
Our report combines quantitative rigor with operational pragmatism. The market sizing and forecasts are driven by a blended methodology that triangulates primary interviews with clinicians, procurement officers, and payers; bottom-up shipment and procurement data; and scenario-based sensitivity testing to reflect regulatory permutations such as label extensions and REMS-type requirements.
Critically, we avoid overreliance on headline volumes alone; our proprietary framework converts clinical duration, insertion/removal rates, and device replacement intervals into actionable revenue and resource models. This allows commercial teams to simulate outcomes under different reimbursement and regulatory scenarios and to test price–volume trade-offs with confidence.
Limitations and how to access the full intelligence
The purpose of this preview is to outline the strategic value of the full study while preserving the proprietary granularity that supports commercial decision-making. Detailed segment-by-segment tables, regional and application splits, company revenue breakdowns, and tender-level pricing benchmarks are intentionally reserved for the full report and accompanying data workbook. These granular datasets are the core deliverables that enable transaction-level modeling and country-specific launch plans.
For organizations committed to winning in 2026, accessing the full dataset and playbooks is essential — the macro trends are directional but the competitive battlegrounds will be decided by granular tender dynamics, reimbursement rules, and clinician workflow adoption at the local level.
Next steps
Executives who need an immediate, operational briefing can request a tailored executive summary workshop with our industry team. The workshop will map report findings to your specific product portfolio and market presence, producing a 90-day action plan that aligns resources to priority plays identified in the report.
To obtain the complete Worldwide Hormonal Implants Market report, detailed datasets, and to schedule a strategy workshop, please visit the PW Consulting website or contact our industry practice lead. Our team stands ready to translate the forecast and playbook into executable steps that protect revenue, accelerate adoption, and reduce regulatory and operational risk across 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Hormonal Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com