

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Epoxy Resin for PCB Market to Expand at 5.88% CAGR — Asia-Pacific Commands USD 2,677.3 Million in 2025

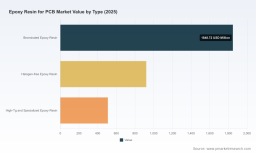
Worldwide Epoxy Resin for PCB Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our newest market research: Worldwide Epoxy Resin for PCB Market. This briefing highlights why the report is indispensable for executives shaping strategic moves in 2026 — from procurement and manufacturing leaders to corporate development, private equity investors, and policy teams. The intent here is to demonstrate the analytical depth and immediate applicability of our findings while preserving the proprietary, segment-level intelligence contained in the full report.
Worldwide Epoxy Resin for PCB Market
Market at a Glance: Macro Trajectory and What It Means
The epoxy-resin value chain serving printed circuit boards (PCBs) has moved from steady recovery into a structurally higher-growth phase. Our historical base (2020–2025) shows the market expanding from USD 2,450.5 million in 2020 to USD 3,280.5 million in 2025. Looking forward, we model a continuation of this momentum: the market is projected to reach approximately USD 4,896.8 million by 2032, underpinned by a compound annual growth rate (CAGR) of 5.88% over the forecast window (2026–2032).
Worldwide Epoxy Resin for PCB Market
Why does this matter for 2026 planning? A near-6% CAGR across a market that already exceeds USD 3.2 billion in annual revenue creates both scale-based opportunities and margin challenges. Companies that translate volume growth into higher-margin differentiated formulations, or that execute industrial-scale cost down and localization plays, will capture disproportionate value. Conversely, players exposed to commodity-grade, undifferentiated resin will face intensified price pressure and trade-policy risk.
Worldwide Epoxy Resin for PCB Market
Report Deliverables — Practical, Transaction-Ready Insights
Our report is structured to drive action. Key deliverables include:
- Proprietary market model covering 2020–2032 with base year 2025; topline and demand-driver scenarios for 2026–2032.
- Supply-side mapping and capacity intelligence, including commissioned projects, planned expansions, and likely project timelines.
- Cost-benchmarking templates that isolate raw material, conversion and logistics contributors to unit economics.
- Regulatory and trade-impact matrix assessing tariffs, anti-dumping outcomes, and regional import dependencies to quantify exposure by strategy.
- Strategic playbooks: procurement hedging, manufacturing footprint optimization, premium-product roadmaps, and merger & acquisition (M&A) prioritization criteria.
- Vendor dossiers and competitive heatmaps with qualitative capability scoring to support partner selection and diligence.
Note: This release intentionally teases our depth of analysis while preserving the full segmentation tables, granular region/application splits, and firm-level financial estimates for the full report.
Competitive Landscape: Who Matters and Why
The PCB-focused epoxy resin market is characterized by a mix of global chemical majors, regional champions, and emerging scale players. Our analysis highlights several companies that shape technology, supply reliability, and price dynamics. Below are summaries that capture strategic positioning rather than divulging proprietary share estimates.
- Nan Ya Plastics Corporation (Taipei, Taiwan) — Vertically integrated producer with strong upstream and downstream linkage into CCL, prepregs and PCB inks. Their portfolio of high-Tg FR-4 and electronic-grade formulations makes them a reference supplier for multilayer, high-reliability boards.
- Olin Corporation (Clayton, Missouri, USA) — Focused on high-purity bisphenol-A based grades and low-hydrolysable-chloride products for electrical laminates. Their product reliability is often selected for demanding insulation and encapsulation applications.
- Hexion Inc. (Westlake Epoxy) — Supplies advanced systems and novolac technologies targeted at FR-4 and higher-performance substrates, emphasizing thermal and chemical resistance.
- Kukdo Chemical (Seoul, South Korea) — Notable for low Dk/Df and halogen-free grades tuned for 5G/high-frequency and automotive radar PCBs, a fast-evolving demand pocket.
- DIC Corporation and Mitsubishi Gas Chemical (Tokyo, Japan) — Both bring deep product engineering capabilities for low-dielectric-loss systems and high-layer PWBs, with particular focus on server, base station and IC substrate applications.
- Resonac, Ajinomoto, Hongchang Electronics and Shengyi Technology — These players demonstrate a mix of advanced-chemistry specialization (e.g., polyphenylene ethers, thermosetting blends) and rapid capacity scaling in electronic-grade resins for regional markets.
Our competitive analysis evaluates technology differentiation, scale economics, downstream customer access, and geographic resilience. For 2026 moves — whether pricing, co-development, or bolt-on acquisition — the key is to pair technical offering with secure supply and compliance readiness.
Recent Industry Dynamics — Supply, Price, and Policy
Several developments altered the strategic backdrop going into 2026:
- Capacity Infill: A material ramp-up in liquid epoxy resin capacity from leading Chinese producers has shifted global supply dynamics. Notably, a Phase II expansion commissioning in 2025 significantly reduced unit costs for one large producer and was followed by plans for further high-end electronic-material projects.
- Trade Remedies: Major jurisdictions have issued definitive trade measures targeting epoxy-resin imports from select Asian suppliers. These rulings are re-shaping global flows, prompting import substitution and creating near-term arbitrage opportunities — but also adding compliance and operational complexity for global buyers and exporters.
- Raw Material Movements: Bisphenol A and other feedstock pricing showed regional volatility in late 2025. In North America, BPA pricing declined notably in Q4 2025 due to Asian offers and softer downstream demand. Meanwhile, epoxy resin prices in parts of Asia trended weak amid ample inventories in H2 2025. These inputs are key levers in our cost-model scenarios.
- Commercial Repricing: In April 2026, a major Japanese materials company announced a substantial across-the-board price adjustment for electronic-material products, citing rising upstream input costs — an example of how upstream commodity variance and component shortages can rapidly alter finished-goods price baselines.
Strategic Implications for 2026 Planning
Based on our synthesis of market momentum, competitive moves and policy shifts, the following priorities should underpin 2026 strategies:
- Supply-Chain Resilience and Diversification — Stress-test supplier networks against trade interventions and regional capacity swings. Shortlist alternate qualified suppliers and build staged inventory buffers for critical grades used in multilayer and high-frequency substrates.
- Segmentation-Based Product Strategy — Invest selectively in differentiated chemistries (e.g., low Dk/Df, high-Tg, halogen-free, low-moisture uptake formulations) where customers reward reliability and performance. Commodity portfolios should pursue scale and cost-leadership or exit to contract manufacturers.
- Price & Contracting Playbook — Adopt dynamic contracting (indexed to feedstock baskets, CPI clauses, or quarterly repricing) to protect margins. Where feasible, pursue long-term offtake with key OEMs in exchange for co-development or capacity reservation fees.
- M&A & Capacity Options — Identify targets that close capability gaps (e.g., high-frequency formulations, localized electronic-grade capacity) and evaluate bolt-on vs greenfield on a total-cost-of-ownership basis — including tariffs and logistics costs introduced by recent trade measures.
- Regulatory & Trade Readiness — Update import/export compliance playbooks and scenario models to quantify duty exposure across likely dispute outcomes. Rapidly engage customs and trade counsel where supply chains are dependent on affected origins.
- Commercial and Technical Partnerships — Prioritize alliances with PCB manufacturers and OEMs on co-development to accelerate qualification cycles; this is increasingly important for high-frequency and automotive radar applications where time-to-qualified-sample is a barrier to entry.
Who Should Read the Full Report
If your 2026 mandate includes any of the following, the full PW Consulting report will be mission-critical:
- Corporate strategy and business-unit leaders defining 3–5 year roadmaps for electronic materials.
- Procurement and supply-chain heads seeking risk mitigation and supplier consolidation strategies.
- M&A teams and PE investors evaluating add-on opportunities or carve-outs in specialty resins and electronic materials.
- R&D and product management teams aligning formulation roadmaps with downstream PCB and OEM requirements.
- Regulatory, trade and customs teams preparing for duty exposure and market-access contingencies.
Our full report supplies the detailed segmentation, supplier-level performance indicators, trade-flow matrices, and actionable financial models that underpin these recommendations. This release demonstrates the rigor and the manner in which we translate data into executable plans — the full dataset and scenario outputs are available in the report package for buyers and subscribers.
Next Steps
Contact PW Consulting’s industry desk to obtain the complete Worldwide Epoxy Resin for PCB Market report and accompanying advisory services. For strategy teams planning 2026 investments, we offer a rapid-read briefing package and bespoke workshop to translate market scenarios into a prioritized 90–180 day action plan.
PW Consulting synthesizes market intelligence and commercial playbooks so leaders can make high-conviction decisions in a market where growth and disruption coexist. The macro trajectory — from USD ~2.45 billion in 2020 to over USD ~4.89 billion by 2032 at a near-6% CAGR — demonstrates both the opportunity and the urgency for decisive strategic moves in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resin for PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com