

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide MRI-Compatible IV Infusion Pumps Market Reaches USD 465 Million in 2025, Set to Grow at 8.6% CAGR Through 2032

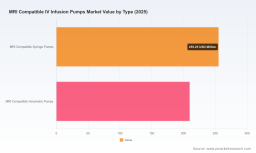
Worldwide MRI Compatible IV Infusion Pumps Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest industry brief synthesizes proprietary modeling and primary research into an actionable roadmap for executives planning product, procurement, and M&A moves in 2026. The MRI compatible IV infusion pumps market is entering a phase of accelerated commercialization and institutional adoption. Our base-year modeling (2025) and a 7-year forecast horizon (2026–2032) show a robust compound annual growth rate of 8.6%, driven by regulatory clearances, new non‑magnetic technologies, and shifting hospital capital priorities. Total market value expands materially across the forecast, underscoring clear windows for first-mover advantage and supply-side consolidation.
Worldwide MRI Compatible IV Infusion Pumps Market
Why this report matters for 2026 strategies
-
Timing: 2026 is a pivotal year where regulatory momentum and procurement recognition converge. Recent FDA clearances and sole-source procurement intents have created early adoption pockets that will set reference prices and clinical workflows.
Worldwide MRI Compatible IV Infusion Pumps Market -
Market momentum: Our base-year estimate for 2025 and near-term projection for 2026 capture inflection points in hospital purchasing cycles and capital budgets. The model projects continuous expansion through 2032, with a marked acceleration in mid‑to‑late forecast years as installed-base replacement and new MRI suite designs incorporate MRI‑compatible infusion solutions.
Worldwide MRI Compatible IV Infusion Pumps Market -
Concentration dynamics: The competitive landscape is highly concentrated (CR3 ≈ 84.5%; CR5 ≈ 92.15%), which has significant implications for pricing power, channel control, and potential regulatory scrutiny. In such markets, the ability to differentiate on safety, service, and total cost of ownership becomes as important as product feature sets.
Practical deliverables in the full report (what we give your teams)
-
Quantitative forecast model (2020–2032): Scenario-ready spreadsheets that allow you to run sensitivity analyses by assumed adoption rates, procurement lead times, and capital replacement cycles. The base scenario uses an 8.6% CAGR for 2026–2032; alternative scenarios stress-test slower and faster uptake.
-
Buyer and procurement playbooks: Hospital capital planners, diagnostic imaging networks, and government buyers exhibit different decision triggers. We provide ready-to-use procurement language, TCO templates (including AHA‑aligned 8‑year useful‑life benchmarks), and negotiation levers aligned to reimbursement and sole-source justification patterns.
-
Regulatory and clinical pathway tracker: A concise timeline of key regulatory milestones and human‑factors expectations, including interpretation of relevant FDA guidance impacting pre-market requirements. This section helps product and clinical teams prioritize data collection and submission strategies to shorten time-to-market.
-
Commercial and service playbooks: Price segmentation, warranty and service bundles, remote monitoring value‑adds, and consumables strategies that protect margins in a concentrated market. Includes hospital decision matrices that weigh upfront price against lifecycle service and compatibility with existing infusion ecosystems.
-
Partner & M&A heatmap: Where to partner, where to buy. Our strategic options matrix aligns technology gaps (e.g., ultrasonic non‑magnetic drives, wireless control interfaces, integrated drug libraries) with potential partners and acquisition targets by stage and geography.
Competitive landscape — who matters and why
The MRI‑compatible infusion space combines specialized device engineering with stringent safety and procurement dynamics. Established infusion OEMs and specialist MRI vendors are pursuing distinct plays:
-
IRadimed Corporation (Winter Springs, Florida): A leader in non‑magnetic dedicated MRI infusion systems. Its recent FDA 510(k) clearance for the MRidium 3870 and subsequent U.S. Department of Veterans Affairs sole‑source procurement intent illustrate a classic innovation‑to‑procurement pathway: regulatory differentiation followed by institutional adoption. IRadimed’s focus on ultrasonic motor technology, touchscreen usability, and a purpose‑built drug library provides a defensible product moat for in‑scanner use cases.
-
B. Braun Melsungen AG (Melsungen, Germany): Pursues a systems approach, integrating shielded infrastructure (e.g., SpaceStation) to enable multiple standard infusion pumps to function safely during MRI procedures. This play targets hospitals preferring modular, multi‑patient throughput solutions and leverages existing large‑volume infusion platforms.
-
Baxter, Fresenius Kabi, Becton Dickinson (BD), ICU Medical / Smiths Medical: These large infusion incumbents bring customer relationships, service networks, and buying leverage. Their strategies emphasize portfolio integration — embedding MRI‑compatibility considerations into broader infusion therapy ecosystems — which can slow specialist entrants’ penetration unless specialists secure clinically validated differentiation or institutional partnerships.
-
Smaller and niche vendors (e.g., Arcomed, Moog Medical/CURLIN): Focused plays on ambulatory, pediatric, or MRI‑adjacent niches where compact form factors and specific therapy profiles are valued. These players can be attractive acquisition targets for established OEMs seeking rapid entry into MRI‑certified product lines.
Recent developments that change the 2026 playbook
-
Regulatory validation accelerates commercial acceptance. The 2025 FDA 510(k) clearance for a next‑generation non‑magnetic MRI infusion pump and the VA’s procurement intent in 2026 are early indicators that validated non‑magnetic systems will be used as procurement benchmarks. This translates to shortened clinical evaluation cycles for buyers once a trusted device has regulatory and government endorsement.
-
Procurement behaviors are evolving. Sole‑source justifications by major government buyers for uniquely compliant devices set precedents that private hospital systems may emulate when updating MRI suites or negotiating service contracts.
-
Capital planning constraints remain influential. Hospitals will evaluate MRI‑compatible infusion purchases alongside MRI scanner upgrades and workflow redesigns — the combined capex case is what converts interest into purchase orders.
Strategic implications and recommended actions for 2026
-
Prioritize regulatory and clinical evidence investments that shorten adoption lag. For technology vendors, targeted expenditures on human‑factors testing, clinical usability studies in MRI environments, and comprehensive drug libraries will materially reduce buyer friction.
-
Design procurement proofs-of-concept with service economics front and center. Hospital purchasers will reward offers that reduce complexity and total cost of ownership — e.g., bundled training, fast replacement units, and remote diagnostics that minimize MRI downtime.
-
Use concentration to your advantage. Incumbents with broad installed bases can leverage service contracts and consumables to monetize MRI workflows. New entrants should instead seek anchor customers (large hospital systems, government buyers) and secure reference sites that demonstrate safety and workflow benefits.
-
Explore bolt‑on acquisitions and strategic partnerships. Given the market’s high concentration, acquiring niche MRI‑certified technologies or forging distribution agreements is a faster route to volume than organic development for many players.
-
Embed lifecycle value in commercial offers. With typical infusion pump useful life benchmarks informing hospital depreciation schedules, vendors that offer predictable upgrade paths and trade‑in allowances can accelerate refresh cycles.
What we intentionally withhold here (and why you need the full report)
In this briefing we surface market scale, growth trajectory, concentration measures, and strategic implications to inform immediate 2026 planning. However, the granular regional, application, and type‑level splits—critical inputs for routing sales resources, pricing by geography, and detailed M&A valuations—are reserved for the full report. We deliberately omit those segmentation tables and exact subsegment figures to protect the competitive value embedded in our primary research and to direct readers to the full dataset for executable commercial plans.
Next steps for executive teams
-
For product leaders: Request our regulatory pathway map and clinical evidence checklist to prioritize submissions that reduce time‑to‑adoption in 2026.
-
For commercial leaders: Acquire the buyer persona playbooks and TCO models to reconfigure pricing, service tiers, and distributor incentives ahead of expected procurement waves.
-
For corporate development: Obtain the M&A heatmap and target valuation ranges to identify high‑leverage bolt‑ons or partnership candidates before competitive auctions intensify.
PW Consulting’s Worldwide MRI Compatible IV Infusion Pumps Market report combines rigorous forecasting, in‑depth vendor benchmarking, and procurement‑grade tools designed to convert market insight into measurable outcomes. To access the full dataset, segmentation tables, and bespoke scenario runs for your organization, please contact our research team or visit the report landing page for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com