

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Long‑Lasting Liquid Foundation Market Poised for 5.48% CAGR, New Report Reveals

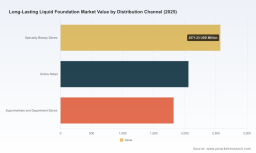
Worldwide Long-Lasting Liquid Foundation Market: Strategic Imperatives for 2026 — PW Consulting Insight
As beauty executives plan budgets, product roadmaps, and M&A pipelines for 2026, a precise understanding of the long-lasting liquid foundation market has become non-negotiable. Our latest PW Consulting report delivers an evidence-based, actionable view of this category — one that connects macro-market dynamics, input-cost pressures, regulatory shifts, and competitive positioning to the practical decisions that will determine market share gains over the next planning cycle.
Worldwide Long-Lasting Liquid Foundation Market
Market trajectory: a resilient category with predictable momentum
The long-lasting liquid foundation category has demonstrated steady expansion through the post-pandemic recovery and into 2025. Our topline market model shows the category growing from roughly USD 4.9 billion in 2020 to approximately USD 6.45 billion in 2025, and continuing to expand through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 5.48%. By 2032 the market approaches the high single-digit billion-dollar mark, reflecting a combination of premiumization, formula innovation, and an enduring consumer preference for multi-functional, high-performance foundations.
Worldwide Long-Lasting Liquid Foundation Market
For strategy teams, this profile implies a market that is large enough to sustain new product introductions and small enough that targeted investments — in formulation, shade inclusivity, digital fit technology, or channel expansion — can generate material returns. The steady CAGR provides a reasonable planning basis, but the rate disguises important pockets of variability tied to raw-material supply, regulatory constraints, and shifting retail economics.
Worldwide Long-Lasting Liquid Foundation Market
What this report gives decision-makers: practical, executable intelligence
- End-to-end market sizing and scenario-based forecasts to support revenue targets, pricing strategies, and long-range plans.
- Actionable go-to-market playbooks for product launches across trade tiers — from mass-market rollouts to prestige and DTC activations.
- SKU and portfolio optimization frameworks that reconcile shade depth, finish variety, and margin contribution.
- Ingredient and supply-chain risk assessments, including supplier concentration heat maps, costs-to-margin sensitivity, and contingency sourcing strategies.
- Regulatory compliance checklists and reformulation pathways to address evolving restrictions such as those under EU REACH and emerging product-safety findings in key markets.
- Competitive landscaping with strategic profiles, recent product moves, and prioritized M&A or partnership targets.
- Retail channel playbooks detailing customer acquisition economics for specialty stores, online travel, and department-store partnerships.
We designed the report to be a working tool for commercial, R&D, and M&A teams — not a theoretical treatise. Each chapter concludes with board-ready slides and a recommended 90-day action plan tailored to three company archetypes: global leader, challenger brand, and private-label/manufacturer.
Industry dynamics that will shape 2026 choices
-
Raw-material volatility and formulation pressure: pigment and emollient costs remain a top constraint for manufacturers; in our 2025 supplier survey, a notable share of producers identified high raw-material costs as a principal margin pressure. This dynamic necessitates active cost-pass-through planning, supplier diversification, and investment in low-cost/high-performance substitutes where formulatoryly feasible.
-
Input-specific signals: titanium dioxide prices in China softened in 2025, offering temporary relief for opacity-driven formulas, while emerging contamination concerns related to zinc oxide underline the need for enhanced raw-material quality assurance and advanced purification technologies to remain compliant in critical markets.
-
Regulatory headwinds: ongoing restrictions under REACH and parallel national regulations are accelerating reformulation cycles for certain synthetic polymers and preservatives. Companies without a proactive reformulation roadmap risk disruption to shelf availability and claims capability.
-
Consumer preference evolution: demand for hybrid skincare-infused, long-wear foundations continues to gain share. Consumers reward multifunctionality — coverage plus hydration, anti-aging, or sun protection — and brands that can credibly substantiate these benefits with clinical or consumer-data claims will capture disproportionate loyalty.
-
Sustainability and packaging innovation surfaced strongly at trade forums in 2026; expect consumer-facing sustainability credentials and refill systems to be decision levers in premium and prestige tiers.
Competitive landscape: a balance of global scale and specialist agility
The category features well-capitalized global leaders alongside digitally native and prestige specialists. Market concentration metrics indicate meaningful opportunity for both scale players and nimble challengers: the top three players account for a material but not dominant share of the market, and the top five widen that share considerably — a structure that supports selective consolidation as well as brand-level disruption.
Key competitive archetypes we profile in the report include:
-
Global CPG and beauty conglomerates — companies with broad R&D networks, robust shade-matching platforms, and deep retail relationships. These players leverage scale to optimize distribution and ingredient sourcing while investing heavily in long-wear claims and inclusive shade ranges.
-
Prestige and luxury houses — brands that monetize premium positioning through product experience, elevated textures, and boutique retail presence. Their focus is often on high-margin SKUs, editorial visibility, and selective distribution.
-
DTC and indie challengers — digitally-native brands that compete on formulation stories, clean or K-beauty credentials, and community-driven shade expansion. These players are adept at iterating quickly but face scale challenges in pigment sourcing and regulatory compliance management.
Our competitive profiles (executive synopses and strategic implications) cover the major market participants and their recent strategic moves: product launches emphasizing breathable long-wear finishes, performance updates validating wear claims, and trade-show innovations in sustainable packaging and formulation. These events illustrate two clear strategic behaviors — incremental product improvement by incumbents, and focused differentiation by challengers leveraging inclusivity and multifunctionality.
How to translate insight into 2026 decisions
-
Prioritize formulation resilience: invest now in supplier auditing, analytical screening for contamination vectors, and alternative pigment pipelines to mitigate both cost and regulatory risk.
-
Rationalize SKUs with a consumer-first lens: narrow SKUs that underperform on margin or repeat-purchase rate, reallocate R&D budget to hybrid, skin-benefit foundation platforms, and create modular shade expansion programs that minimize inventory drag.
-
Double down on claim substantiation: design clinical- and consumer-evidence strategies for “long-wear” and “skincare” claims to defend positioning against increasingly skeptical consumers and tightening regulatory oversight.
-
Align channel economics to brand ambition: calibrate DTC and specialty-store investments for higher customer lifetime value while using selective retail partnerships for scale and discovery.
-
Use M&A tactically: identify acquisition targets that fill technical gaps (e.g., pigment supply, low-impact preservatives) or accelerate digital shade-matching capabilities, and prioritize assets that derisk reformulation or expand profitable shade depth without disproportionate inventory cost.
A trailer — why you need the full report
This article outlines the macro trajectory, the high-level competitive contours, and the most consequential risk vectors for 2026 planning. The full PW Consulting report contains the operational playbooks, scenario revenue models, and the proprietary decision-support tools that product, commercial, and corporate development teams require to convert insight into measurable outcomes.
We intentionally limit disclosure of granular segment splits in this summary. Our client-facing dossier includes detailed regional and finish-type segmentation, distribution-channel economics, SKU-level profitability matrices, and bespoke scenario simulations tailored to company archetypes — the precise inputs teams will use to finalize 2026 budgets and investment roadmaps.
Final note to executives
The long-lasting liquid foundation market is neither a fad nor a static commodity; it is a category in which formulation science, supply-chain dexterity, regulatory foresight, and consumer empathy converge. For 2026, the winning strategy will be the one that couples disciplined portfolio economics with credible, evidence-backed claims and nimble sourcing approaches. PW Consulting’s report is built to be the playbook for that strategy — practical, prioritized, and directly tied to the levers that create value.
For detailed analysis of this topic, please visit the official page: Worldwide Long-Lasting Liquid Foundation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com