

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cupping Therapy Kits Market Worth USD 192.48 Million in 2025; Asia‑Pacific Dominates with USD 82.59M as 5.8% CAGR Expected (2026–2032)

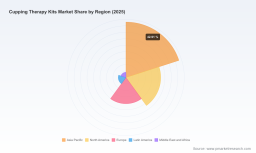
Worldwide Cupping Therapy Kits Market: Strategic Imperatives for 2026 — PW Consulting Insight
The cupping therapy kits market has transitioned from a niche complementary therapy accessory into a strategically relevant product class for manufacturers, distributors, clinicians, and health-system buyers. PW Consulting’s latest Worldwide Cupping Therapy Kits Market report (base year 2025, forecast 2026–2032) synthesizes five years of historical movement and a forward-looking model that places the market on a steady expansion path — with a compound annual growth rate (CAGR) of 5.8% across the forecast window. In revenue terms, the market has grown from a defined mid-three-figure million-dollar base in 2020 to approximately USD 192.5 million in 2025, and our model projects it will approach the high-two-hundred million-dollar range by 2032.
Worldwide Cupping Therapy Kits Market
Why this report matters for 2026 decision-makers
-
Actionable planning horizon — 2026 is the inflection year for many commercialization and channel strategies. Buyers and investors need granular visibility into product-level growth drivers (material innovation, pump technology, integrated recovery kits) and near-term demand elasticity; our report translates macro trends into operational priorities for the coming 12–18 months.
Worldwide Cupping Therapy Kits Market -
Regulatory & reimbursement clarity — with cupping kits regulated as Class I medical devices in the U.S. and emerging ISO guidance on device types, companies must align product design and labeling to avoid surprises. The report explains the practical implications of device classification and common billing pathways (codes such as vasopneumatic and manual therapy descriptors) so commercial teams can engage payers and clinicians with credible reimbursement narratives.
Worldwide Cupping Therapy Kits Market -
Competitive posture and M&A readiness — consolidation is nascent and fragmented. Our competitive mapping and valuation-ready benchmarking help corporate development teams prioritize targets, valuation levers, and integration risks.
Data-driven narrative without the spoilers
We deliberately maintain the “trailer” approach in this press release: you will see the analytical scaffolding and strategic conclusions, but the report’s granular sub-segmentation (region-by-region and application-by-application dollar splits, unit pricing curves, and channel-level SKU matrices) is reserved for the full deliverable. That said, our headline model shows continuous expansion at ~5.8% CAGR through 2032, driven by a confluence of product innovation, clinical acceptance in sports medicine and physical therapy, expanded retail/home-care adoption, and cross-border trade in cost-competitive plastic and silicone systems.
What the full report contains (practical, execution-focused)
-
Comprehensive market model: a downloadable Excel workbook with yearly revenue and volume forecasts (historical 2020–2025; forecast 2026–2032), sensitivity scenarios, and a Monte Carlo overlay to stress-test strategic choices.
-
Go-to-market playbooks: segmented strategies for practitioner channels, sports medicine OEM partnerships, direct-to-consumer subscription bundles, and institutional tendering (clinics, wellness chains, and health systems).
-
Product roadmap prioritization: decision matrices for material choices (glass vs silicone vs plastics), pump technologies (manual vs vacuum-assisted), and adjacent offerings (myofascial recovery kits, electro-compatibility, magnet-integrated systems).
-
Regulatory and reimbursement toolkit: step-by-step checklists for Class I compliance, labeling harmonization, and sample clinical documentation to support coverage conversations with payers and the VA.
-
Supply chain resilience assessment: supplier scorecards, dual-sourcing scenarios, and cost-to-serve models to mitigate raw-material volatility and logistics disruption.
-
Commercial benchmarking and pricing optimization: price elasticity analysis, SKU rationalization recommendations, and channel margin ladders for distributors and retailers.
-
M&A screening and diligence templates: thematic maps of attractive targets, pro forma synergy models, and integration playbooks tuned to this specialized, low-capex device class.
Competitive landscape: active players and strategic moves
The market remains fragmented with a mix of US-based specialty brands, legacy Asian OEMs, and distributors that combine product with education. A non-exhaustive competitive snapshot highlights how leading actors are differentiating and where opportunity pockets exist:
-
EarthSpa R&D (United States) — positions itself on quality and provenance, leveraging handblown glass heritage and proprietary pump systems. Their USP is domestically manufactured premium lines that appeal to practitioners seeking “made in USA” assurances and traceability.
-
Lhasa OMS (United States) — builds strength by bundling diversified product families (silicone, glass, magnetic and plastic kits) targeted at licensed practitioners, complemented by distribution relationships with clinical buyers.
-
HawkGrips and Thysol US / FASCIQ (United States) — focus on premium silicone systems for clinical therapy and sports recovery, often coupled with continuing education (CEU) offerings to drive practitioner adoption and premium ASPs.
-
Kangzhu (China OEM) — a credible source for cost-competitive plastic vacuum sets and FDA-registered Class I devices; their presence underpins much of the private-label supply to regional distributors globally.
-
Boen Medical and other Asian glass specialists — maintain global reach for traditional glass cupping sets and supply professional-grade cups at scale for clinic-oriented buyers.
-
Performance Health (including TheraBand/Medco) — represents a strategic exemplar of portfolio expansion: integrating cupping tools into myofascial recovery kits for physiotherapy and sports rehab, reflecting the convergence between cupping and mainstream rehabilitation products.
Recent industry activity further clarifies directional intent: Performance Health’s early-2026 product-line expansion, Kobayashi Pharmaceutical’s increased home-wellness offerings in Japan, AcuZone’s late-2025 ergonomic upgrades for practitioners, and Hwato’s durability improvements across Asia-Pacific demonstrate both demand-side depth and ongoing product maturation. These moves underscore the dual pressure on incumbents to innovate while preserving regulatory compliance and clinician trust.
Regulatory, standards and reimbursement considerations
-
Regulatory: In large markets, cupping kits are typically regulated as Class I “pressure applying” medical devices. This classification simplifies market entry pathways relative to higher-risk devices—but requires robust quality systems, proper labeling, and vigilance against misbranding.
-
Standards: ISO guidance for air-extraction and glass cupping devices exists and is becoming a commercial differentiator. Suppliers who align design-validation and test protocols to ISO standards reduce buyer friction in clinical channels.
-
Reimbursement: Clinical billing practices commonly route cupping under existing therapy or pneumatic device codes when medically necessary. Companies aiming for broader clinical adoption should invest in outcomes documentation and clinician education to facilitate coding and payer conversations.
Strategic recommendations for 2026
-
Prioritize evidence generation for clinical pathways most likely to influence procurement decisions in 2026 — sports medicine, rehabilitation, and integrated wellness chains. Small, well-designed prospective studies can materially de-risk sales to institutional buyers.
-
Design channel-specific SKUs: create durable, higher-margin kits with training bundles for clinics, and simplified, cost-efficient consumer SKUs for retail and e-commerce. Bundle logic and subscription add-ons will be key monetization levers.
-
Invest in reimbursement readiness: prepare clinical-use guides, CPT/HCPCS linkage documents, and sample medical records templates to accelerate coverage discussions with payers and the VA.
-
Strengthen supplier diversification: dual-source critical components (especially pumps and silicone compounds) and maintain an inventory buffer strategy during Q1–Q3 2026 to insulate launches from supply shocks.
-
Evaluate M&A selectively: target regional manufacturers with established distribution or education businesses that can be scaled internationally; prioritize assets with clean regulatory histories and defensible IP in pump ergonomics or integrated systems.
-
Make sustainability a competitive claim: transparent material sourcing and recycling programs for plastic cups resonate with institutional buyers and can support premium pricing.
Concluding note and how to get the complete intelligence
For commercial leaders setting 2026 strategy, this market is clear: sustained growth, tactical consolidation opportunities, and tangible upside for organizations that combine product innovation with clinical evidence and channel execution. PW Consulting’s full Worldwide Cupping Therapy Kits Market report contains the confidential segment-level revenue splits, granular regional demand matrices, price bands, SKU-level forecasts, and our interactive scenario model — resources designed to support board-level strategy and commercial planning.
To access the full dataset, interactive forecasting model, and the step-by-step implementation playbooks, visit the official report page or contact our market intelligence desk. The full analysis is the only source that publishes the underlying spreadsheets and operational templates you will need to transform 2026 intent into measurable market share.
For detailed analysis of this topic, please visit the official page: Worldwide Cupping Therapy Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com