

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide PVDF Fluorocarbon Coatings Market Valued at USD 1,600.68 Million in 2025, Poised for 6.02% CAGR Through 2032

Worldwide PVDF Fluorocarbon Coatings Market 2026: Strategic Briefing from PW Consulting
Executive summary
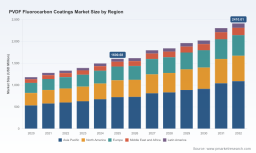
As companies plan capital allocation, product development, and go‑to‑market strategies for 2026, reliable foresight into the PVDF (polyvinylidene fluoride) fluorocarbon coatings market is increasingly material. PW Consulting’s latest market study — grounded in historical performance (2020–2025) and a detailed forecast through 2032 — shows a resilient global market expanding at a mid-single-digit compound annual growth rate (CAGR) of 6.02%. Measured in USD, the market size advances from an estimated USD 1.60 billion in the 2025 base year to a materially larger opportunity by 2032, underpinning continued strategic relevance for verticals such as architectural metals, industrial equipment, and high‑durability applications.
Worldwide PVDF Fluorocarbon Coatings Market
Why this briefing matters for 2026 decision cycles
-
Investment timing: Manufacturers and formulators evaluating capacity expansions or brownfield upgrades need a calibrated view of demand momentum and margin pressure through 2028–2032 to justify multi‑year projects.
Worldwide PVDF Fluorocarbon Coatings Market -
Product strategy: Regulatory and raw‑material headwinds are reshaping product specification requirements (low‑VOC, PFAS surfactant‑free systems), altering R&D priorities and premium positioning.
Worldwide PVDF Fluorocarbon Coatings Market -
Procurement & sourcing: Volatility in feedstock and regional production constraints will affect procurement strategy; secure sourcing and hedging approaches must be stress‑tested against realistic scenarios.
-
M&A and partnerships: The market exhibits moderate concentration among the leading suppliers, creating an active strategic landscape for tuck‑ins, licensing, and strategic alliances.
Market snapshot and outlook (strategic highlights)
Our baseline model, anchored on a 2025 base year, captures both the recovery and structural growth drivers that influence PVDF fluorocarbon coatings. The market grew steadily across the historical period and is forecast to expand at a 6.02% CAGR over the 2026–2032 horizon. This trajectory supports a multi‑year investment thesis for players that can operationally and commercially adapt to changing formulation requirements and higher input costs.
Key takeaways for 2026 planning:
-
Demand durability: End‑use demand is underpinned by long replacement cycles in architectural coatings and ongoing industrial modernization programs globally, creating a stable base while selected end markets demonstrate above‑average growth.
-
Premiumization: There is a clear bifurcation between commodity and premium PVDF‑based fluorocarbon systems — the latter commanded by long‑life color retention, weatherability, and low maintenance promises. Companies that can credibly demonstrate lifecycle value capture higher contract tenures and margin resilience.
-
Capital intensity: Resin capacity decisions have long lead times and sizeable capital requirements. The timing of these investments will determine supply balances and margin cycles into the latter part of the decade.
Dynamics shaping 2026 – risks and accelerants
-
Raw‑material cost pressure: Our analysis shows notable upward pressure in VDF monomer costs during 2024–2025, which fed through to resin pricing. Market participants will confront ongoing cost volatility; procurement strategies and pass‑through mechanisms will be decisive for 2026 margins.
-
Regional production constraints: Environmental enforcement actions in several manufacturing hubs have produced episodic cost spikes and temporary capacity tightness. For organizations dependent on spot purchases, these dynamics increase supply chain risk and mandate contingency plans.
-
Regulatory evolution: Tightening VOC standards and intensified scrutiny of PFAS‑related chemistries in North America and Europe are accelerating reformulation efforts toward low‑VOC and surfactant‑free PVDF systems. Regulatory compliance is now a design requirement, not merely a cost item.
-
Price signals: Near‑term regional price benchmarks reflect modest appreciation versus 2025 levels, underlining the importance of price modeling in contract negotiations for 2026.
Competitive landscape — what to watch in 2026
The supplier field combines multi‑national chemical producers, specialist resin manufacturers, and large coatings formulators. Market concentration is meaningful: the top three players account for a substantial share of global supply, with the top five representing an even larger portion — a structure that leaves room for both scale advantages and premium niche players.
-
Arkema (France): A leading PVDF resin supplier, Arkema’s brands are recognized for weatherability and durability, and they have been active in product innovation toward low‑environmental footprint solutions. Notably, Arkema announced a capacity expansion at its Changshu site with a planned startup targeted for 2028 — a move that will recalibrate supply dynamics in Asia and influence regional pricing and contract formation.
-
Solvay (Belgium): Solvay’s PVDF resins are central to licensed high‑PVDF coating systems widely used in architectural metal protection. Their position supports premium channel relationships with formulators and fabricators focused on long‑term color retention.
-
PPG Industries, AkzoNobel, Sherwin‑Williams: Major global coatings formulators have longstanding coil and extrusion coatings portfolios based on PVDF systems. Their customer reach and specification influence mean commercial access to large architectural projects depends on maneuvering within their procurement and licensing frameworks.
-
Daikin and Kureha (Japan): Resin manufacturers with strengths in specialty fluoropolymers and chemical resistance, supporting industrial and construction applications that require high performance under aggressive operating environments.
Recent corporate developments are material for 2026 planning. Arkema’s announced capacity expansion in March 2026 and prior product advancement toward water‑borne, low‑VOC PVDF systems highlight a dual theme that will be central in 2026: capacity reconfiguration alongside formulation innovation.
What the PW Consulting report delivers (practical, operational insights)
The full study was designed as a decision support toolkit for executives, investment committees, and commercial teams. It blends top‑down scenario modeling with bottom‑up operational inputs to produce actionable outputs, including:
-
Robust market sizing and a 2026–2032 forecast, with sensitivity scenarios around feedstock price paths and regulatory tightening.
-
Supply‑chain stress tests and contingency playbooks tailored to typical PVDF value‑chain models (resin producers, licensed formulators, coil coaters, and architectural specifiers).
-
A regulatory impact matrix linking regional rules to product specifications and likely timeline for compliance-driven reformulations.
-
Commercial playbooks for premium vs. value segments: pricing levers, specification economics (total cost of ownership models), and contract design options to protect margins.
-
Supplier scorecards, capability maps, and an M&A/opportunity heat map that prioritize targets based on technology, geographic fit, and commercial reach.
-
Capex sizing and ROI templates for resin capacity additions, including break‑even windows under multiple demand scenarios.
To remain true to the “trailer” intent of this briefing, we summarize the practical outputs above but reserve segment‑level tables, country‑level forecasts, and company valuation models for the full report.
Strategic recommendations for 2026
-
Prioritize formulation resilience: Accelerate development or licensing of low‑VOC and PFAS surfactant‑free PVDF systems to align with tightening regulations in primary markets. Early movers can capture specification positions on long‑life architectural projects.
-
Hedge smartly on feedstocks: Implement multi‑tiered procurement strategies (long‑term supply agreements, regional dual sourcing, and selective financial hedges) to mitigate VDF volatility and episodic regional cost spikes.
-
Right‑size capacity investments: Delay irreversible greenfield commitments until after near‑term demand confirmation, but proceed with brownfield debottlenecking where short lead‑time volume can be captured. Use staged investments to manage risk and preserve optionality.
-
Leverage partnerships: For formulators without in‑house resin capability, evaluate licensing, JV structures, or long‑term resin supply agreements to secure technical differentiation without incurring full upstream capital exposure.
-
Commercially defend premium pricing: Develop total cost of ownership evidence (maintenance savings, life‑cycle color retention) to justify premium contracts, particularly in architectural and façade applications.
-
Monitor competitor moves and regulatory signals: Track announced capacity additions and product launches — these are leading indicators of near‑term supply pressure or pricing disruption.
Next steps — how PW Consulting can support your 2026 planning
Our full Worldwide PVDF Fluorocarbon Coatings Market report contains the granular datasets, country‑level forecasts, and executable playbooks referenced here. For commercial teams preparing bids, R&D leaders planning reformulation roadmaps, or corporate strategists considering capacity or M&A moves, the report provides the empirical foundation and decision tools required to act confidently in 2026.
Contact PW Consulting to arrange a briefing, obtain the detailed dataset, or commission a custom scenario analysis tailored to your portfolio and risk appetite. The full intelligence package includes downloadable data tables, supplier profiles, and step‑by‑step implementation guides that are intentionally withheld from this high‑level briefing to preserve strategic exclusivity for subscribers.
For detailed analysis of this topic, please visit the official page: Worldwide PVDF Fluorocarbon Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com