

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Smart Lock With Cat's Eye Market to Grow at 13.5% CAGR, Approaching USD 3.76 Billion by 2032

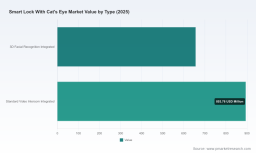
Worldwide Smart Lock With Cat's Eye Market — Strategic Outlook for 2026 Decision Makers
PW Consulting’s latest market brief on the Worldwide Smart Lock With Cat's Eye market synthesizes proprietary forecasting with on-the-ground competitive, regulatory, and technology analysis to help executives and investors make high-confidence decisions in 2026. Built on a 2025 base year and a rigorous 2020–2025 historic series, the study projects a sustained expansion through 2032, driven by convergence between smart access control, embedded imaging, and cloud-enabled services. The market grows at a compound annual growth rate (CAGR) of 13.5% across the 2026–2032 forecast window — accelerating from an early-decade base to multi-billion-dollar scale by 2032 in USD million terms — creating a landscape of rapid product innovation, new business models, and regulatory friction that will determine winners and losers over the next 18 months and beyond.
Worldwide Smart Lock With Cat's Eye Market
Why this matters for 2026
- Timing is strategic: 2026 sits at the inflection where integrated cat's eye cameras (wide-angle and HD), AI-based detection, and platform-enabled services reach price points and reliability that enable mass-market adoption in residential retrofit and greenfield installations.
- Investment clarity: the market trajectory provides a decision window for product roadmaps, channel investment, and M&A — delaying action risks ceding share to platform players and OEM consolidators.
- Regulatory complexity: privacy and data protection regimes are coalescing into divergent regional requirements that will materially affect product architectures and go-to-market tactics.
Market trajectory — a data-driven snapshot
Our base-year assessment (2025) anchors a detailed historic series (2020–2025) and a forecast covering 2026–2032. Over the 2026–2032 forecast period the market grows at an annualized 13.5%, rising from mid‑market scale in 2025 to several times that size by 2032. This pace reflects rising consumer willingness to pay for visual door monitoring, greater penetration of integrated unlocking technologies (fingerprint, face, mobile), and the migration of video-enabled peepholes from niche security add-ons to standard smart lock features bundled with services.
Worldwide Smart Lock With Cat's Eye Market
Primary growth drivers
- Technology densification: improvements in camera optics (ultra‑wide fields of view), low‑light sensors, and embedded AI allow cat's eye implementations to deliver reliable person detection and context-aware notifications without expensive external devices.
- Platform economics: cloud and IoT platforms enable recurring revenue via storage, analytics, and premium monitoring services; white‑label partnerships lower time to market for OEMs.
- Retrofit viability: form-factor and battery optimizations make cat's eye smart locks attractive for retrofit in dense urban housing, unlocking a large addressable market.
- Channel diversification: installers, telcos, and home security integrators are adopting bundled offerings, expanding reach beyond pure e-commerce flows.
Report contents — what you get (and what we intentionally keep exclusive)
The report is structured to be operational for commercial and corporate strategy teams, spanning quantitative forecasting, product benchmarking, and executable recommendations. Key deliverables include:
Worldwide Smart Lock With Cat's Eye Market
- Market sizing and a transparent methodology foundation: historic and forecast series, scenario runs, and sensitivity tests under alternative adoption and price erosion trajectories.
- Go‑to‑market playbooks for OEMs, platform providers, security integrators, and retailers, with channel economics and model P&L templates.
- Product benchmarking and technical scorecards evaluating camera field of view, AI detection fidelity, battery endurance, authentication methods, and on‑device vs cloud processing tradeoffs.
- Competitive landscaping with strategic profiles, recent launches, partnership maps, and M&A heatmaps to identify acquisition targets and alliance candidates.
- Regulatory risk matrix and compliance blueprints covering major jurisdictions, with privacy-by-design checklists and firmware/hardware mitigations for data minimization and consent management.
- Supply chain health assessment: key components, single‑source risks, and near-term procurement strategies for 2026 procurement cycles.
- Actionable decision frameworks: go/no-go investment filters, pilot-to-scale roadmaps, and a customizable ROI model to stress-test business cases at different ASP and subscription assumptions.
Note: In keeping with the “teaser” principle of this release, granular segment-level tables (detailed regional and application splits, SKU-level volumes and specific price points) are reserved for the full report and subscribers. This is deliberate: those core segmentation data are high-value inputs for supplier negotiations, channel contracting, and targeted M&A — and therefore are provided through our official distribution channels.
Competitive landscape — positioning and strategic moves
The current competitive topology is a hybrid of global consumer-technology firms, traditional lock manufacturers, platform enablers, and rapid-growth Chinese OEMs. Market concentration metrics indicate a moderately fragmented market, with leading groups collectively holding a meaningful but not dominant share — enough to pressure margins yet leave space for regional champions and focused challengers.
- Xiaomi (Beijing): Rapid consumer rollout cadence and integrated product executions (large indoor screens, 160°+ viewing angles, multi‑modal unlocking, extended battery life) position Xiaomi to scale quickly in markets where brand trust and retail access are deciding factors. Recent 2025 launches underscore a play to own the mid-tier smart home bundle.
- Huawei (Shenzhen): By combining wide-angle camera modules with AI human detection and multiple unlocking modes, Huawei’s approach emphasizes vertical integration and premium feature-packaging — a strategy that plays to its strengths in connectivity and AI silicon.
- Yale (ASSA ABLOY) (global operations): The incumbent lock player translates mechanical security heritage into integrated digital offerings, targeting buyers who prioritize proven durability combined with new visual monitoring features.
- Tuya Inc. (Hangzhou): As a platform enabler, Tuya reduces time-to-market for OEMs by providing WiFi, app control, and standardized integrations for cat's eye cameras and video doorbell linkage. Platform partners gain distribution breadth at the cost of differentiation risk.
- Regional OEMs (e.g., PuXin Smart, Locstar, Botin Smart): These firms compete on price-performance in key markets, rapidly iterating on camera and AI features and leveraging platform partnerships to scale.
Recent product launches by major vendors in 2025 — notably multiple Xiaomi releases and Huawei’s new Smart Door Lock 2 — accelerate feature parity and intensify competition at both ends of the value chain. For incumbents and late entrants, the question is not merely “who has the best sensor?” but “who can translate device capabilities into recurring consumer value while navigating compliance and distribution complexity?”
Regulatory and privacy dynamics — a critical constraint
- China: National standards to date emphasize mechanical safety; unified rules for recording functions, retention windows, and privacy protections for camera‑equipped locks are not yet established. This creates short-term uncertainty for manufacturers targeting mass deployments.
- European Union: Under GDPR the usage of footage from in‑door cat’s eye devices is strictly for private purposes; providers must ensure cameras do not point toward neighbors’ doors or public areas without justification and must uphold stringent storage and access controls.
- Local rules (example: New York City): Some jurisdictions are adopting tenant‑centric data privacy laws that mandate consent, limited retention, physical key options, data minimization, and documented security controls — requirements that can force redesigns of data flows and product features.
For product and legal teams, compliance design choices (on-device processing vs cloud, retention policies, and consent flows) are now strategic levers that affect market access and monetization options.
Strategic imperatives for 2026
- Design for privacy and modularity: architect products to default to on-device detection, provide opt-in cloud features, and enable region-specific firmware to accelerate market entry while minimizing rework.
- Partner for platform scale: leverage platform providers to access distribution while preserving differentiation through hardware-level IP and branded service experiences.
- Channel-first commercialization: invest in installer training and security integrator partnerships where trust drives purchase decisions; balance this with direct digital channels for early adopters.
- Monetize beyond the device: structure subscription tiers for cloud storage, advanced analytics, and home-assist services while protecting a base device revenue stream to maintain margin resilience.
- Prepare for regulatory shocks: prioritize compliance roadmaps and privacy engineering as pre-market investments to avoid costly recalls or market restrictions.
How to use this report in your 2026 planning
Executives should use the report to validate investment timing, stress-test product specifications against regulatory scenarios, and identify acquisition targets or platform partners. The deliverables include scenario models that can be customized to reflect company-specific ASPs, channel mix assumptions, and regional go-to-market sequences — enabling an evidence-based 100/300/1,000 day plan for pilots, scale, and expansion.
Next steps
PW Consulting offers the full dataset, detailed segmentation tables, and bespoke advisory workshops to translate findings into a tailored strategic plan. For access to the complete market model, granular regional and application splits, and vendor scorecards, please consult the official release page and contact our Smart Access practice to schedule a briefing.
In a market moving as quickly as smart locks with visual cat's eye capability, early and informed action in 2026 will determine who commands the next wave of consumer trust, recurring revenue, and cross-sell into broader smart home ecosystems.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com