

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide D‑Ring Blood Pressure Cuffs Market Poised for 7% CAGR, New Insights Reveal

PW Consulting Releases Strategic Brief: Worldwide D‑Ring Blood Pressure Cuffs Market — Critical Intelligence for 2026 Decision‑Makers
PW Consulting today publishes a strategic industry brief derived from our full market research report covering the Worldwide D‑Ring Blood Pressure Cuffs market (base year 2025, forecast period 2026–2032). Built for senior executives, corporate development teams, procurement heads and product leaders, the brief distills the macro trends, competitive dynamics and practical levers that will determine winners and laggards as the market expands at an estimated 7.0% CAGR through 2032.
Worldwide D-Ring Blood Pressure Cuffs Market
Executive snapshot: Market momentum you cannot ignore
The D‑ring blood pressure cuff market has transitioned from steady replacement demand to a growth profile driven by expanding homecare use, infection‑control preferences and renewed capital investment in outpatient monitoring. Our model shows the market growing from a mid‑single‑hundreds USD million base in 2025 to a substantially larger opportunity by 2032, reflecting the 7.0% compound annual growth rate projected across the 2026–2032 horizon. Market concentration is moderate: the top three suppliers account for roughly 42.5% of revenue and the top five for approximately 58.8%, a structure that favors both scale players and well‑positioned niche specialists.
Worldwide D-Ring Blood Pressure Cuffs Market
Why this brief matters for 2026 corporate strategy
- Immediate procurement choices: single‑patient vs reusable portfolios, SKU rationalization and cost‑per‑use analysis will materially affect 2026 margin outcomes.
- Product roadmaps: clinical validation, latex‑free materials and antimicrobial claims are now prerequisites for hospital adoption and for commanding premium pricing.
- M&A and partnership timing: consolidation opportunities and bolt‑on acquisitions are concentrated in accessory manufacturing and regional distribution — timing and target selection require current, granular market signals.
- Regulatory and reimbursement positioning: compliance with international standards and alignment with HCPCS reimbursement coding will shape list‑price strategies and channel incentives.
What’s in the full PW Consulting report (practical deliverables)
- Proprietary market model: annualized revenue by product form factor and end‑use across 2020–2032 with scenario toggles for pricing, penetration and material‑cost shocks.
- Comprehensive demand‑driver mapping: patient demographics, home monitoring growth curves, outpatient center installation plans and hospital procurement cycles.
- Supply‑chain and cost model: input cost assumptions (medical‑grade fabrics, bladder manufacturing, assembly), labour and freight sensitivities, and break‑even analyses for reusable vs single‑patient formats.
- Regulatory & reimbursement matrix: requirements reference (including clinical validation expectations) and payer code impacts on net selling prices in major markets.
- Competitor benchmarking and playbooks: capability matrices, product roadmaps, go‑to‑market paths, and a “playbook” for market entry, expansion and defensive retention.
- Commercial and procurement levers: negotiation scorecards, supplier KPIs, volume‑based sourcing scenarios and inventory strategies for 2026 planning cycles.
- Executive dashboards and downloadable models: editable files for sensitivity testing and board‑ready slide templates highlighting high‑impact choices.
Competitive landscape: who’s shaping product and go‑to‑market norms
The D‑ring cuff category is characterized by a mix of legacy medical device OEMs, specialised accessory manufacturers and regional suppliers. Key players profiled in our report include:
Worldwide D-Ring Blood Pressure Cuffs Market
- Welch Allyn (Hillrom) — USA: Offers FlexiPort D‑ring cuffs in reusable and disposable formats compatible with a broad range of monitors. Hillrom’s focus on clinical interoperability continues to support their hospital channel strength.
- Omron Healthcare — Japan: Strong in home and professional segments with wide‑range D‑ring cuffs and emphasis on consumer safety and manufacturability for mass homecare volumes.
- GE Healthcare — USA: DINAMAP D‑ring cuff family spans single‑patient and reusable units; recent regulatory steps reinforce an infection‑control positioning (see recent 510(k) activity).
- Philips — Netherlands: Supplies D‑ring cuffs for IntelliVue and SureSigns lines with an emphasis on latex‑free materials and monitor compatibility across acute care settings.
- SunTech Medical — USA: Known for segmented bladder designs and performance accuracy; recently expanded catalogues to include larger/bariatric sizes across reusable and single‑patient options.
- A&D Medical & American Diagnostic Corporation (ADC) — USA: Focus on durable nylon constructions and compatibility with aneroid and electronic gauges, serving ambulatory and professional end‑users.
Recent corporate developments illustrate how product and regulatory moves are reshaping market access. For example, GE Healthcare received FDA 510(k) clearance for a DINAMAP D‑ring cuff line with improved antimicrobial properties (Oct 2024), SunTech expanded its Advantage D‑ring line to include bariatric sizes (June 2024), and Hillrom demonstrated one‑tube connectivity and FlexiPort solutions at ACC.24 (March 2024). These actions signal two concurrent trends: feature differentiation through clinical and infection‑control claims, and supply‑side expansion to capture diverse limb profiles and care settings.
Regulatory, reimbursement and input‑cost dynamics
- Standards and accuracy: D‑ring cuffs must be validated to international accuracy standards (ISO 81060‑1:2019), which mandates clinical verification to within ±5 mmHg — a gating factor for hospital adoption.
- Reimbursement influence: Existing HCPCS categorization for reusable cuffs materially affects net pricing strategies in markets where Medicare and similar payers dominate procurement.
- Material and manufacturing cost pressure: Medical‑grade fabrics and bladder components continue to fluctuate. Manufacturers with in‑house sealing and bladder extrusion capabilities enjoy a margin buffer versus outsourced suppliers.
- Clinical safety expectations: Latex‑free materials are effectively table stakes in many hospital systems; our fieldwork shows an expectation threshold that must be met to be considered in hospital tendering processes.
Strategic implications for 2026 — five action priorities
- Prioritize clinical validation and certification now. For products targeting acute and inpatient markets, ISO‑level validation and a clear antimicrobial or latex‑free claim reduce procurement friction and shorten sales cycles.
- Rebalance portfolios between reusable and single‑patient offerings based on channel profitability. Use our cost‑per‑use model to decide which SKUs to keep, which to retire, and where to introduce disposables to capture homecare growth.
- Lock down critical raw‑material supply: secure multi‑year agreements for medical‑grade textiles and bladder components, or vertically integrate where economics permit, to reduce margin volatility in 2026 price negotiations.
- Refine commercial channels: build or expand distributor partnerships for regions with fragmented procurement, and create hospital tender playbooks to translate product features into quantifiable ROI for buyers.
- Scan acquisition targets: identify small accessory manufacturers with differentiated IP (e.g., segmented bladders, proprietary fabrics) as potential bolt‑ons to accelerate capability and reach.
90‑day playbook for executive teams
- Week 1–2: Run the PW Consulting sensitivity dashboard against your P&L to verify margin exposure to material and freight cost swings.
- Week 3–6: Commission targeted clinical validation where gaps exist; prioritize submissions that unlock major hospital tenders.
- Week 7–10: Execute supplier negotiations for critical inputs and evaluate short‑term safety stock to insulate 2026 shipments.
- Week 11–12: Finalize SKU rationalization and update commercial terms for major distributors ahead of Q1 2026 contracting rounds.
How PW Consulting supports execution
Our full report is deliberately comprehensive and operationally focused. Clients receive editable forecasting models, procurement scorecards, competitor dossiers and a phased go‑to‑market playbook. For executive teams seeking custom work, we offer accelerated sprints that combine our market model with on‑site supplier interviews and transaction support for M&A or strategic sourcing events.
Accessing the full intelligence (why you’ll want it)
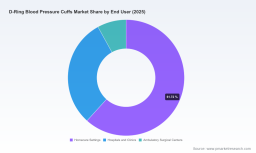
This release purposely summarizes high‑value findings but withholds the granular regional, material and end‑user revenue splits — those detailed tables and the interactive forecast sheets are only available in the paid report and client portal. If your 2026 plan depends on precise SKU sizing, regional prioritization, or supplier scorecards, the full dataset and our hands‑on advisory options are designed to turn insight into measurable outcomes.
To request a copy of the report, arrange a briefing with our senior analysts, or explore a tailored engagement, please visit the PW Consulting market research portal or contact our industry team directly. Our specialists can demonstrate how a 7.0% CAGR market and a moderately concentrated supplier landscape translate into specific revenue and margin opportunities for your organization in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide D-Ring Blood Pressure Cuffs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com