

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Sauna Steam Generator Market to Surge from USD 707.06 Million in 2025 to USD 1,106.72 Million by 2032 at a 6.61% CAGR

Worldwide Sauna Steam Generator Market: Strategic Preview for 2026 Decision-Makers
Executive summary
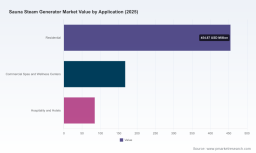
PW Consulting today releases a strategic preview of our forthcoming Worldwide Sauna Steam Generator Market report, built to inform executive teams, investors, and procurement leaders planning for 2026. The global market has expanded steadily from the start of the last decade and reached approximately USD 707 million in 2025. Our modelling indicates a continued compound annual growth rate (CAGR) of roughly 6.61% through the 2026–2032 forecast window, with the industry tracking toward just over USD 1.1 billion by 2032. These headline metrics underline a market that is mature enough to support scale players while offering tactical openings for differentiated innovators.
Worldwide Sauna Steam Generator Market
Why 2026 is a strategic inflection point
-
Regulatory deadlines and efficiency standards that come into force in 2026 will reframe product roadmaps and procurement specifications for commercial buyers.
Worldwide Sauna Steam Generator Market -
Post‑pandemic recovery in wellness and hospitality continues to underpin demand, while technology trends—especially controls, connected services and energy‑efficiency—are creating new competitive advantages.
Worldwide Sauna Steam Generator Market -
Raw material and labor cost pressures that intensified in the early 2020s have normalized at higher levels, making margin protection and supply‑chain resiliency core priorities for 2026 planning cycles.
Market dynamics: drivers, headwinds and structural features
The sauna steam generator market is shaped by three structural forces: underlying demand from wellness, retrofit and new build projects; product innovation around control, safety and efficiency; and input‑cost/regulatory pressures. Supply‑side consolidation has produced a moderately concentrated landscape—our concentration metrics show that the top three vendors control a meaningful share of market revenues and the top five hold a clear majority—creating an environment where scale and brand matter, but room remains for focused challengers.
-
Demand drivers: Continued expansion in wellness tourism and increasing wellness allocations in hospitality capex are sustaining commercial orders. Consumer adoption of home wellness amenities is supporting the residential channel.
-
Regulatory and efficiency pressures: New efficiency requirements set to become binding in 2026 elevate product performance as a gating factor for commercial procurement. Vendors that can demonstrate high delivered efficiency will command premium access to institutional buyers.
-
Cost and supply constraints: Stainless steel pricing has risen materially in recent cycles and labor availability for certified installations remains a pinch point in certain markets. These input pressures are compressing margins for low‑value producers and accelerating consolidation among mid‑tier manufacturers.
Competitive landscape: what the leaders are doing now
The competitive set includes established specialty manufacturers and system integrators that serve both residential and commercial channels. The strategic moves we are tracking fall into three categories: product sophistication (controls, connectivity and modularity), channel capture (service and installation networks) and sustainability (efficiency and materials).
-
Steamist (Long Island City, NY) continues to leverage a broad capacity range and a reputation for reliability in both residential and commercial segments. Their portfolio approach reduces barriers for multi‑site rollouts.
-
Mr. Steam (Hauppauge, NY) is pushing the premium, app‑enabled experience—recent product introductions emphasize Bluetooth and connected controls, aligning with high‑end residential and boutique spa demand.
-
Amerec (Woodinville, WA) focuses on dependable steam production across both single‑site and larger commercial installations, keeping serviceability and uptime at the core of their value proposition.
-
TyloHelo and Harvia (Europe) are advancing integrated sauna systems and energy‑efficient portfolios to meet stringent regional standards and export demand.
-
KLAFS and Saunacore are differentiating through hospitality‑grade solutions and custom stainless steel boilers for commercial applications, respectively.
Notable recent product and marketing activity illustrates the pace of innovation: trade‑show launches of new generator series and CES‑scale announcements of enhanced control suites show incumbents are investing in both the product and the experience. These initiatives signal an arms race around controls, efficiency, and serviceability rather than purely price‑based competition.
What our report delivers (practical, actionable content)
PW Consulting's full report is structured as an executive toolkit rather than an academic monograph. It is organized to support immediate 2026 decisions and includes:
-
Market sizing and trend analysis with validated historical data and our 2026–2032 forecast scenarios, enabling topline revenue planning and sensitivity testing.
-
Competitive intelligence dossiers on leading manufacturers, summarizing product roadmaps, channel strategies, manufacturing capabilities and recent deal activity.
-
Commercial playbooks for manufacturers and distributors—go‑to‑market tactics by channel, recommended product bundles, and account expansion strategies for hospitality and wellness chains.
-
Procurement and supplier selection templates, including a scorecard for evaluating OEMs on efficiency performance, service coverage, and certification compliance.
-
Regulatory compliance matrix and a certification checklist that maps major market requirements (including the safety and overheating standards required for US commercial sales).
-
CapEx / OpEx modeling templates to quantify lifecycle cost tradeoffs under different efficiency and installation‑labor assumptions.
-
M&A playbook with valuation drivers for strategic and financial buyers, identifying where consolidation and bolt‑on acquisitions create the most accretive outcomes.
To preserve the report’s proprietary value, this preview highlights the types of insights available; the full segment tables, company revenue splits and downloadable templates are available in the complete report.
Strategic implications and recommended moves for 2026
-
Manufacturers: Prioritize energy‑efficiency upgrades and certified performance guarantees. With efficiency standards tightening, plan product updates and certification timelines now to avoid 2026 procurement disqualification.
-
Distributors and integrators: Build certified installation networks and promote packaged services to capture higher lifetime value. Given elevated installation labor rates in key markets, service differentiation is a defensible revenue stream.
-
Hospitality and spa operators: Reassess retrofit strategies using lifecycle cost models rather than lowest‑upfront‑cost procurement. Higher-efficiency units may deliver superior TCO in regulated commercial environments.
-
Investors and private equity: Seek platforms with technical depth in controls and certification know‑how, and target tuck‑ins that can accelerate service coverage and assembly scale.
Risks to monitor
-
Raw material volatility: Ongoing steel market fluctuations and potential freight disruptions can compress margins—sourcing strategies and contractual protections should be stress‑tested in scenario planning.
-
Regulatory non‑compliance: Missing the 2026 efficiency thresholds in key jurisdictions risks product delisting from commercial tenders; certification pathways should be a near‑term investment priority.
-
Installation capacity: Persistent shortages of certified technicians in some countries increase project timelines and warranty exposure; training and service partnerships mitigate this risk.
Frequently asked questions (FAQ)
-
Q: Which standards matter for commercial sales in the US? A: The safety standard that certifies units against overheating and related risks is mandatory for most commercial channels; compliance is a precondition for institutional procurement.
-
Q: How should buyers approach energy efficiency claims? A: Look for third‑party verification and lifecycle modeling that includes installation and operating hours. New thresholds set in several markets mean unverified claims carry commercial risk.
-
Q: Are material cost increases transitory? A: Recent cycles indicate a higher baseline for key inputs. Hedging, multi‑sourcing and design for reduced material intensity are practical mitigants.
How to use this preview as a planning tool for 2026
-
Use the headline market sizing and CAGR to triangulate internal topline forecasts and sanity‑check growth assumptions for product lines or regions.
-
Adopt the report’s procurement scorecard to qualify suppliers for 2026 tenders and to prioritize certification investments.
-
Leverage the M&A playbook to evaluate opportunistic acquisitions that accelerate service networks or add control/IoT capabilities.
Closing: why this report matters for executives in 2026
As 2026 approaches, procurement and product decisions made today will determine which organizations win in the steam‑generator value chain tomorrow. The market is large enough to reward scale, yet dynamic enough that efficiency, digital controls and service models will define winners. PW Consulting’s full Worldwide Sauna Steam Generator Market report equips leaders with the quantitative foundations, competitive insight and executable playbooks they need to convert market momentum into durable advantage—without reinventing the wheel.
For access to the full dataset, segmented analyses, downloadable toolkits and company dossiers—including the detailed segment tables and appendices that underpin our forecasts—please consult the complete report release available on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Sauna Steam Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com