

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Agriculture Micro Irrigation Market Poised to Jump from USD 13,850 Million in 2025 to USD 26,142.6 Million by 2032 at a 9.5% CAGR

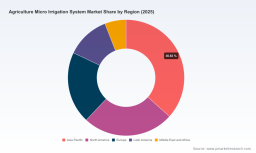
Worldwide Agriculture Micro Irrigation System Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest proprietary study on the Worldwide Agriculture Micro Irrigation System Market positions micro irrigation as a central lever for agronomic resilience, resource efficiency, and farm-level profitability over the coming decade. Using a 2025 base year and a 2026–2032 forecast horizon, our model projects the industry to expand at a compounded annual growth rate (CAGR) of 9.5%, roughly doubling market size across the forecast window. The market scale, trajectory, and competitive concentration quantified in the report provide CFOs, corporate strategy teams, product leaders, and policy advisors with a clear evidence base to prioritize investments and partnerships for 2026.
Worldwide Agriculture Micro Irrigation System Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is an inflection year where policy incentives, accelerating adoption of precision technologies, and material-cost dynamics converge — creating both opportunity and execution risk for market participants. Our analysis isolates the levers that will determine which companies capture value versus those that merely participate.
Worldwide Agriculture Micro Irrigation System Market -
Practical orientation: The study is built to be operational. Beyond high-level forecasting, it includes scenario-conditioned investment roadmaps, vendor capability scorecards, commercial playbooks for channel expansion, and supply-chain stress tests calibrated to polymer price shocks and subsidy rollouts.
Worldwide Agriculture Micro Irrigation System Market -
Decision focus: We translate market-level growth into decision-relevant insights for four corporate choices: product R&D prioritization, manufacturing footprint and inventory strategy, go-to-market segmentation, and M&A/alliance targeting.
Market trajectory and what it implies
Our base-year assessment (2025) and the forecast path through 2032 highlight a robust growth environment. The industry’s near-term momentum is backed by consistent adoption curves, technology deployment in precision fertigation and automation, and supportive public-sector programs aimed at conserving water and increasing crop productivity. Across the forecast horizon, the sector is projected to grow at a 9.5% CAGR, reflecting both organic replacement cycles (infrastructure renewal) and new-adoption waves as smallholders and commercial farms modernize irrigation practices.
For corporate planners, the implication is clear: scale is attainable, but capture is conditional on product differentiation, integrated service offerings (hardware + digital agronomy), and resilience to upstream input volatility. The report quantifies these trade-offs and maps expected payback timelines for key investment options under multiple macro scenarios.
Competitive landscape — concentration and capability patterns
The market shows moderate concentration at the top. Our CR3 and CR5 metrics indicate that leading suppliers control a meaningful share of market value, creating both stability and a high bar for new entrants. Established players combine manufacturing scale, channel depth, and growing software-enabled services that shift value capture from hardware margins to recurring service revenues.
-
Incumbent strengths: Legacy irrigation specialists continue to leverage deep product portfolios — from driplines and emitters to filtration and fertigation systems — while adding digital layers for dosing, telemetry, and remote management. These firms are increasingly investing in AI-enabled dosing, precision fertigation, and integrated hardware-software bundles to lock in recurring farm-level revenue.
-
Recent strategic moves: The market’s leading innovators have accelerated product launches and strategic partnerships. Examples include the introduction of AI-powered dosing solutions for enhanced fertigation precision, hybrid driplines designed to reduce labor and clogging risks, and targeted regional manufacturing expansions intended to cut lead times and meet subsidy-driven demand surges.
-
Manufacturing and supply adjustments: Several global suppliers have recently announced capacity and localization initiatives to mitigate long lead times. These moves are a direct response to rising stewardship demands from major agricultural programs and the need to comply with local procurement and certification rules that affect subsidy eligibility.
Regulatory and policy dynamics shaping 2026 strategies
Regulation and public funding are decisive growth engines for micro irrigation. International standards for pressurized drip systems and large-scale public investments in irrigation modernization have raised the baseline for acceptable system performance and created preferential procurement channels. Simultaneously, long-standing subsidy programs in major agricultural markets continue to accelerate replacement and new-adoption decisions at the farm level.
For business leaders, three policy-related actions are essential in 2026: engage early with standards-setting bodies and certification partners; align product specifications to subsidy program requirements; and develop policy-aware pricing and channel strategies that anticipate local documentation and compliance demands.
Supply chain, materials, and operational risks
Micro irrigation systems are materially dependent on polymer feedstocks and precision components. Price volatility in polymers and the requirement for certified components in certain subsidy schemes create both margin pressure and compliance risk. Our scenario analysis models polymer-price shocks and maps their impact on wholesale margins, recommended hedging approaches, and when to accelerate inventory builds without overexposing working capital.
The report also evaluates lead-time sensitivity across key manufacturing geographies and prescribes near-term mitigation tactics: dual-sourcing of critical components, strategic inventory placement near demand clusters, and contract structures with suppliers that balance resilience and cost.
Technology and product strategy — where to invest in 2026
-
Digital agronomy and services. The fastest routes to premiumization are through software-enabled agronomic services: AI-assisted fertigation, remote diagnostics, and outcome-linked advisory. Companies that bundle advisory subscriptions with hardware can smooth revenue seasonality and increase lifetime customer value.
-
Robust, low-maintenance hardware. Innovations that reduce clogging, simplify installation, and lower power demand on-field pumps materially shorten payback periods for farmers — especially in regions with constrained energy and labor. Hybrid designs and pressure-compensating emitters remain prime R&D targets.
-
Localized manufacturing and modular product lines. Modularization enables faster customization for local crops and climatic conditions while keeping BOM complexity manageable. Local assembly or near-market factories reduce tariff and logistics friction, aligning suppliers with subsidy and procurement timelines.
M&A, partnerships and go-to-market plays
Consolidation and targeted alliances will be prominent in 2026. Strategic acquisitions should prioritize three value levers: access to proprietary digital platforms, regional distribution footprints aligned with subsidy programs, and manufacturing capabilities that reduce time-to-market. For vendors without deep-field sales, partnerships with agri-input distributors or platform cooperatives can accelerate penetration while limiting fixed-cost expansion.
Our report includes a prioritized list of capability gaps commonly targeted by acquirers, a valuation framework adapted to recurring-revenue models, and negotiation levers specific to irrigation asset transfers (inventory, warranty obligations, and channel exclusivity).
What’s inside the PW Consulting report — operational tools for 2026
-
A calibrated market model with base-year validation and scenario branches for high-adoption, baseline, and conservative pathways — enabling quick sensitivity testing against price, subsidy, and raw-material scenarios.
-
Vendor capability matrices and scorecards focused on product breadth, digital maturity, manufacturing footprint, and channel strength — designed for rapid shortlist creation in M&A and sourcing processes.
-
Channel and commercial playbooks tailored to the unique procurement environments of major agricultural programs — including templated compliance checklists and pricing structures that align with subsidy mechanics.
-
Supply-chain resilience playbook that translates polymer-price and logistics scenarios into executable procurement and inventory tactics, including contractual templates for supplier risk-sharing.
-
Practical KPIs and post-deal integration milestones to track performance of acquisitions or new-market launches over the first 24 months.
Immediate actions for 2026 planning cycles
-
Prioritize a two-track investment strategy: (1) accelerate digital services and AI-enabled fertigation to capture recurring revenue; (2) localize critical manufacturing capacity to reduce exposure to logistics and ensure subsidy-compliant supply.
-
Run a scenario test in Q1 2026 that models three polymer-price cases and two subsidy uptake rates to quantify margin and working-capital impacts; use results to guide capital allocation.
-
Identify at least one regional partnership that provides immediate market access to subsidy recipients and a distribution counterparty to reduce go-to-market time by 6–12 months.
Conclusion — strategic value of the report
As water scarcity, regulatory pressure, and the drive for higher yields intensify, micro irrigation is moving from a niche efficiency tool to a strategic platform in agriculture. The market is sizable and expanding — our modeling indicates meaningful upside for companies that combine differentiated hardware, software-enabled agronomy, and supply-chain resilience. PW Consulting’s report equips executives with the quantitative scaffolding and practical playbooks needed to convert market growth into durable competitive advantage in 2026 and beyond.
Next steps
Access the full analysis, including the interactive market model, vendor scorecards, and the 24-month integration playbook, via our report portal. For tailored briefings or to commission a bespoke scenario run calibrated to your balance sheet and product roadmap, contact PW Consulting’s Agriculture Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Agriculture Micro Irrigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com