

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Amino Acid Metabolism Disease Market to Expand at a 7.2% CAGR Through 2032

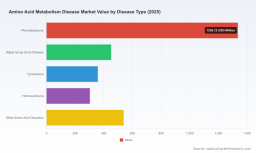
Worldwide Amino Acid Metabolism Disease Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s newest market intelligence brief, Worldwide Amino Acid Metabolism Disease Market (Base year 2025; Forecast 2026–2032), is designed as a practical playbook for life‑science executives, investors, and public‑policy stakeholders who must make high‑stakes decisions in 2026. The report synthesizes historical performance (2020–2025), a financially grounded forecast (2026–2032), and scenario‑based strategic guidance to prioritize investments across therapeutics, diagnostics, and supply‑chain interventions. At a macro level, the market grows from a 2025 baseline of approximately USD 2,990.8 million to an expected USD 4,865.4 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.2%—a growth trajectory that supports bold moves but demands disciplined, risk‑aware planning.
Worldwide Amino Acid Metabolism Disease Market
Why this report matters in 2026
-
Actionable forecasting for capital allocation: Our model translates the 7.2% CAGR into revenue scenarios and return sensitivities for late‑stage assets, platform technologies (e.g., gene therapy vectors), and specialty chemical supply investments.
Worldwide Amino Acid Metabolism Disease Market -
Competitive concentration and access: With the top three players controlling a significant share of the market (CR3 ~42.5%) and the top five expanding to nearly 59%, incumbency advantages coexist with targeted white‑space opportunities for novel modalities and niche geographic plays.
Worldwide Amino Acid Metabolism Disease Market -
Regulatory and reimbursement inflection points: Recent regulatory rulings and reimbursement rules are creating short windows of premium pricing and exclusivity—opportunities that are often time‑limited and regionally differentiated.
What the report contains — practical tools, not just charts
-
Integrated market model: A dynamic, scenario‑enabled financial model that maps patient populations, treatment uptake, pricing scenarios, and reimbursement pathways to revenue outcomes across the 2026–2032 forecast horizon. The model is designed for sensitivity testing and M&A valuation inputs.
-
Commercial playbooks: Step‑by‑step GTM templates for medical foods, enzyme replacement therapies (ERTs), small molecules, and gene therapies—covering channels, key opinion leader (KOL) engagement, diagnostics linkage, and payer negotiation strategies.
-
Regulatory roadmaps: Comparative timelines and risk matrices for accelerated approvals, orphan exclusivity strategies, label expansions, and post‑market study obligations across major jurisdictions.
-
Supply‑chain and manufacturing checklist: Practical due‑diligence templates to assess API dependencies, single‑source risks, and cost‑to‑serve dynamics for specialty APIs and biologic COGS.
-
M&A and partnership scorecards: Objective criteria and a prioritized target universe highlighting where licensing, bolt‑on M&A, or co‑development can materially de‑risk a portfolio while preserving upside.
-
Executive dashboards and investor briefs: Ready‑to‑use executive summaries, investor Q&A, and board‑level slides to accelerate decision cycles in 2026.
Key market dynamics shaping 2026 strategy
-
Regulatory and exclusivity dynamics: Orphan designations and label expansions continue to be primary value levers. For example, certain gene therapy programs have already secured orphan designations that would translate into multi‑year exclusivity upon approval. Companies and investors must map these regulatory lifecycles against patent timelines to accurately project revenue windows and post‑patent erosion risk.
-
Reimbursement variability: Payer policies are fragmenting by indication and region. Certain pharmacologic therapies for phenylketonuria, for instance, are covered under public programs with prior‑authorization rules tied to biochemical thresholds. Negotiation playbooks that combine outcomes‑based pricing with diagnostic gating can materially improve access.
-
Supply‑chain concentration: Some APIs rely on proprietary synthesis routes; absence of alternative sources raises both commercial and clinical supply risks. Sponsors should prioritize dual‑source strategies or backward integration where feasible—especially for products with limited therapeutic substitutes.
-
Intellectual property cliffs and biologic protection: Composition‑of‑matter patents for certain biologics extend into the early 2030s, delaying biosimilar entry in key markets. That window creates a premium commercial environment for late‑stage investments but also compresses the runway for novel entrants who might otherwise depend on price erosion to compete.
-
Technology inflection: Gene therapies and AAV‑based platforms are progress drivers, but as of 2026 several advanced constructs remain constrained to clinical‑trial use only. This makes partnership models—where established players de‑risk delivery and manufacturing—especially attractive.
Competitive landscape — focus on who matters and why
Our analysis profiles incumbents and emergent challengers across therapeutic modalities. We dissect commercial strength (product portfolio and market access), scientific moat (novel mechanisms, platform IP), and operational leverage (manufacturing, specialty channels). Highlights:
-
BioMarin Pharmaceutical Inc. — A leader in enzyme replacement and amino‑acid disorder therapeutics, with market‑moving label changes (e.g., expanded self‑administration approvals) that materially alter patient management and cost structures.
-
Travere Therapeutics, Inc. — Demonstrating the potential for adjacent rare‑disease franchises to scale beyond narrow indications following positive late‑stage results in related organ systems.
-
Chiesi Farmaceutici S.p.A. — Holds strategic control over a critical synthesis pathway for a key API; this creates a persistent barrier to generic entry and offers optionality for global supply partnerships.
-
Recordati Rare Diseases — Focused on metabolic niche therapeutics with established distribution footprints in certain markets, making it an attractive acquirer for companies seeking immediate commercial infrastructure.
-
Platform accelerants — Dimension/Takeda and LogicBio/AstraZeneca transitions highlight how platform acquisition strategies consolidate gene therapy know‑how and factory capacity; these moves are reshaping partnership economics and R&D risk allocation.
-
PTC Therapeutics — Progressing clinical programs that could reframe standards of care in certain amino‑acid disorders if late‑stage readouts are positive; pipeline timing and trial design are central to 2026 pipeline prioritization debates.
Recent developments that shift the 2026 playbook
-
Label expansion and self‑administration approvals have changed cost and adherence assumptions for enzyme therapies, increasing addressable outpatient management and altering payer willingness to reimburse in outpatient settings.
-
Positive Phase 3 results in related rare kidney conditions highlight the opportunity to repurpose or extend indications for molecules active in amino‑acid metabolism pathways—an important hedging strategy for pipeline value realization.
-
Initiation of Phase 3 trials for novel small molecules in major indications creates potential catalysts in 2026–2028 that should be integrated into valuation models and partnering timelines.
-
Regulatory approvals for pediatric formulations change prescribing behavior and widen access, but also introduce pediatric post‑market obligations that must be priced into commercial investments.
Strategic recommendations for executives and investors in 2026
-
Reprioritize portfolios against exclusivity calendars: Map patent expiries and orphan exclusivity windows against launch and commercialization timelines to determine where to invest for maximum NPV uplift.
-
Insulate supply chains early: For products dependent on single‑source APIs or proprietary synthesis, secure second‑source agreements or consider upstream acquisitions to avoid costly shortages or price shocks.
-
Consider hybrid commercialization models: For ultra‑rare indications, blended partnerships with local specialty distributors can deliver reach without unsustainable fixed costs.
-
Leverage regulatory incentives: Use orphan pathways, label expansion strategies, and accelerated programs to compress time‑to‑market; however, bake in the cost of confirmatory studies into financial models.
-
Time partnership and M&A windows to clinical catalysts: Structure deals that align milestone payments with late‑stage readouts to preserve upside while limiting near‑term capital exposure.
-
Adopt outcome‑linked contracting: For high‑cost therapies, build real‑world evidence (RWE) collection into launch planning to support performance‑based reimbursement pilots.
Limitations and where to find the full intelligence
Consistent with our “teaser” approach, this release emphasizes strategic takeaways and macro drivers without reproducing the report’s proprietary sub‑segment tables, regional revenue splits, or customer‑level forecasts. The full report contains detailed segmentation by disease type, treatment modality, region, and payer scenarios, together with downloadable model files, clinician interview transcripts, and step‑by‑step commercialization templates that are essential for granular decision execution. PW Consulting clients and authorized subscribers can access the complete dataset, financial model, and bespoke advisory hours for tailored strategic planning.
Frequently flagged regulatory & R&D constraints (selected)
-
Orphan exclusivity is a powerful value lever; certain advanced programs already carry designations that materially alter competitive dynamics upon approval.
-
Patent protections for key biologics persist into the next decade in major markets; entrants should build multi‑axis strategies rather than relying on price erosion alone.
-
Gene therapy programmes for some disorders remain in clinical use only as of 2026—commercial readiness requires parallel investments in manufacturing scale and long‑term safety surveillance.
For executives preparing 2026 budgets, prioritizing initiatives that increase optionality—dual sourcing, flexible manufacturing, strategic partnerships, and outcome‑based contracting pilots—will be decisive. PW Consulting’s full Worldwide Amino Acid Metabolism Disease Market report delivers the granular analytics and executable templates necessary to convert the macro trends outlined here into competitive advantage. To obtain the full report and model access, visit the PW Consulting research portal or contact our advisory team for a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Metabolism Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com