

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Movie Projector Market to Expand at 7.21% CAGR Through 2032

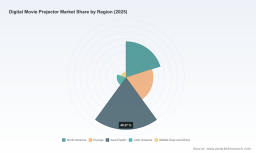
Worldwide Digital Movie Projector Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Digital Movie Projector Market positions strategic decision-makers to move fast and confidently in 2026. Built on a detailed base year of 2025 and a seven-year forecast horizon (2026–2032), the report synthesizes market sizing, competitive dynamics, technology evolution, and supply‑chain risks into an actionable playbook. At a macro level, the market continues to expand at a healthy compound annual growth rate of 7.21% (USD, Million), validating sustained reinvestment opportunities across product, channel and services strategies.
Worldwide Digital Movie Projector Market
Market snapshot: growth trajectory and what it means
After a period of accelerated adoption between 2020 and 2025, the digital movie projector market transitions from recovery to structurally higher baseline demand, driven by technology refresh cycles, a resurgence in theatrical exhibition and premium venue investments. Our model — calibrated on company filings, component lead‑times, and verified vendor deployments — shows an upward trend through the forecast horizon, with the global market expanding from a mid‑cycle total in the base year to materially higher aggregate revenue by 2032 (all figures in USD Million). This trajectory is not linear: it reflects waves of product upgrades (notably laser and next‑generation DMD platforms), pockets of large institutional procurement tied to strategic cultural investments, and episodic supply‑side shocks that create tactical buying windows.
Worldwide Digital Movie Projector Market
For boards and corporate strategists, the implication is clear: 2026 is a year to act on two fronts simultaneously—accelerate premium product rollouts to capture high‑value refresh demand, and shore up supply‑chain resilience to avoid margin compression during the next component cycle.
Worldwide Digital Movie Projector Market
Why this report matters for 2026 planning
- Investment prioritization: We translate the CAGR and market trajectory into prioritized opportunity clusters — hardware, integrated systems, and aftermarket services — so executives can allocate capital where returns are most likely in 18–36 months.
- Product roadmaps: Our analysis maps technology readiness (optical engines, illumination systems, and controller chips) to customer willingness to pay, enabling product managers to sequence feature introductions that maximize adoption without eroding installed base value.
- Go‑to‑market timing: With detailed scenario planning, the report identifies optimal windows for channel promotions, strategic pricing, and enterprise bids, reducing risk of head‑to‑head margin wars in contracting cycles.
- Risk mitigation: We quantify the supply exposures that matter most and prescribe specific operational levers — dual sourcing, inventory positioning, and contract structuring — to preserve delivery credibility and margin.
What’s inside the report (executive‑grade, operationally relevant)
- Market sizing and validated growth scenarios (base year 2025, forecast 2026–2032) with sensitivity bands reflecting technology adoption and macroeconomic permutations.
- Demand‑side segmentation frameworks that prioritize target segments by upgrade velocity and lifetime revenue potential (presented as strategic archetypes rather than exhaustive numeric splits).
- Competitive playbooks for market leaders and fast followers that synthesize product portfolios, channel strategies, and recent go‑to‑market moves into actionable steps for market share defense and capture.
- Supply‑chain heat maps and mitigation tactics: focused guidance on laser diode suppliers, controller IC risk, and contract and inventory levers to reduce single‑source exposure.
- Commercial templates (RFP language, service packaging, and bundling recommendations) to accelerate sales cycles in both retrofit and greenfield deployments.
- Scenario builders and dashboards that allow CFOs and strategy teams to stress‑test revenue outcomes under variant cost and adoption assumptions.
Competitive landscape — who matters and why
The market remains concentrated among a handful of established vendors, with a tight top‑tier concentration that materially influences technology licensing and channel behavior. Our competitive analysis focuses on companies that shape product, standards and procurement trends:
- Barco NV (Belgium) — recognized for a leading portfolio of next‑generation laser cinema projectors. Barco’s strategic emphasis on high‑brightness RGB laser systems and simplified families for theaters gives it an operational advantage in large venue rollouts and premium screen installations.
- Christie Digital Systems (United States; Ushio subsidiary) — continues to be a key innovator with recent product extensions focused on modular illumination and compact high‑performance chassis. Christie’s product cadence and successful bids into large cultural projects illustrate its ability to convert technical differentiation into sizable deployments.
- NEC Display Solutions (Sharp NEC, Japan) — a dependable executor in DLP‑based projectors with a focus on long‑life laser models for theatrical and institutional customers. NEC’s channel relationships in certain regions provide steady retrofit demand and aftermarket service revenues.
- Sony Corporation (Japan) — although its positioning has evolved, Sony remains relevant at the high end through distinct optical and image‑processing offerings — particularly where differentiated image quality or franchise relationships matter.
Recent product and component announcements underscore the industry’s technical momentum. Notable 2025–2026 developments include new laser‑illuminated projector series with advanced illumination technologies and chipset innovations showcased at major events in early 2026. These advances reduce the cost per lumen, enable higher native frame rates and improve native contrast — all factors that accelerate replacement cycles for premium screens.
Technology and supply‑chain dynamics to watch
Three dynamics will determine winners and losers over the next 24 months:
- Illumination technology momentum: Leading manufacturers have standardized on laser‑based systems for performance and longevity. Laser has become the de facto performance tier for premium theaters and high‑end venues; vendors that can couple power‑efficient illumination with robust service agreements will capture the most lucrative upgrade segments.
- Critical component concentration: High‑performance laser diodes and some optical materials rely on narrow supplier bases and rare earth‑dependent supply chains. Executives should assume intermittent supply constraints and plan sourcing strategies accordingly.
- DMD/Controller roadmap acceleration: Advancements in DMD chipsets and controller electronics enable higher brightness and frame‑rate features in compact form factors. Early adopters of these chipsets can differentiate by offering reduced total cost of ownership and new use cases (e.g., immersive and premium small‑screen venues).
Regional demand and geopolitical considerations
While demand growth is global, certain policy and nation‑level investments are shaping procurement. Sovereign cultural and entertainment initiatives in select markets have produced concentrated procurement events and multi‑year contracts. Such programs can materially shift regional supplier footprints and create strategic footholds for companies that secure early wins. At the same time, technology licensing regimes and patents (including DLP licensing arrangements) remain structural factors determining who can deliver certain classes of products at scale.
Recommended 2026 playbook for executives
- Prioritize premium‑segment capacity and margin protection: Shift R&D and production readiness toward laser‑illuminated and next‑generation controller platforms where margin upside and replacement demand are greatest.
- Harden supply chains proactively: Execute dual‑source agreements for critical laser diode families, consider strategic stockpiles for key optical components, and include pass‑through clauses in customer contracts to protect margins against component cost spikes.
- Win institutional programs: Build tailored commercial bundles for sovereign and large cultural programs — combining hardware, installation, and predictable long‑term service revenue models that align with public procurement cycles.
- Monetize service and retrofit: Develop aftermarket offerings (performance upgrades, energy‑efficiency retrofits, and subscription‑style maintenance) to augment hardware revenues and smooth revenue cyclicality.
- Plan tactical partnerships: Evaluate partnerships with key chipset and optical suppliers to co‑develop compact, higher‑lumen modules that shorten OEM time‑to‑market.
How PW Consulting’s report supports implementation
Our study is designed for immediate operational use: each major finding is paired with a short‑form action plan, a one‑page risk mitigation checklist, and an executable commercial template. For strategy teams, the included scenario builders translate market growth assumptions into revenue and margin outcomes under alternative supply and demand states. For product teams, the report provides prioritized feature roadmaps mapped to willingness to pay and channel acceptance. For procurement, we provide supplier maps and contractual negotiation playbooks tied to realistic lead‑time scenarios.
Governance and methodology
The report’s sizing and forecasts are built from a hybrid methodology: triangulation of vendor financials, primary interviews with OEM and component suppliers, procurement callouts from major institutional buyers, and bottom‑up modeling of installed base replacement cycles. We apply conservative adoption curves for new illumination and controller technologies, and we stress‑test results across macroeconomic and component supply scenarios to produce high‑confidence decision inputs for 2026 planning.
Next steps — where to get the full intelligence
This article is a strategic trailer: it demonstrates the depth of our analysis and highlights the decision levers that matter for 2026, while preserving the detailed segment matrices and contract‑level intelligence that drive tactical execution. To access the full dataset, detailed regional and channel breakouts, and the operational toolkits referenced above, PW Consulting invites executives to review the full Worldwide Digital Movie Projector Market report on our site — the only place to obtain the proprietary models, scenario builders, and the complete segmentation that underpin the recommendations outlined here.
For a briefing tailored to your firm’s position in the value chain, contact PW Consulting’s Strategy & Industry Practice; our team will prioritize a customized executive workshop that accelerates decision‑making for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Movie Projector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com