

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Paper Dry Strength Resin Market Forecast to Reach USD 1,333.1 Million by 2032

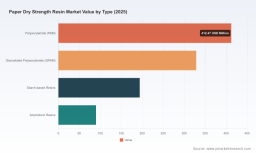
Worldwide Paper Dry Strength Resin Market: Strategic Insights for 2026 Decision‑Making
PW Consulting’s latest market research — the Worldwide Paper Dry Strength Resin Market Report (base year 2025) — delivers a focused, practice‑oriented roadmap for executives, procurement leads, R&D heads and investors preparing strategy for 2026 and beyond. Built on an audited historical series (2020–2025) and a detailed forecast window (2026–2032), the study quantifies market size in USD (Million), models scenario returns under a 3.82% compound annual growth rate (CAGR), and translates those macro dynamics into actionable commercial and technical recommendations. This release note highlights the report’s strategic value while intentionally withholding core segmentation datapoints to encourage readers to access the full study for granular intelligence.
Worldwide Paper Dry Strength Resin Market
Market snapshot: what the numbers mean for strategic choices
The market is sized and tracked on an annual basis in USD Million with 2025 as the report’s base year. After a steady recovery through the early 2020s, the sector shows continued expansion into the early 2030s under a mid‑single‑digit trajectory (3.82% CAGR over the forecast period). By 2032 the total market is projected to be materially larger than in 2025 — a growth envelope that is large enough to reward investment in capabilities (R&D, formulation, supply chain resilience) while still creating headroom for disciplined consolidation and premiumization.
Worldwide Paper Dry Strength Resin Market
For 2026 planning, two quantitative takeaways are immediate: (1) growth is persistent but not hyperbolic, which favors targeted investments over broad capital deployment; (2) volatility in feedstock and regional demand cycles will determine near‑term margin trajectories more than sheer volume expansion. In short: 2026 is a year for precision — optimize where you have leverage, defer where complexity outruns return.
Worldwide Paper Dry Strength Resin Market
Strategic implications and recommended moves for 2026
- Procurement & raw‑material risk management
Feedstock volatility has become an operational pulse‑check. Acrylamide monomer, a core input for many synthetic polyacrylamide chemistry routes, has fluctuated markedly in recent years. The report quantifies scenarios showing how swings in acrylamide pricing and availability affect EBITDA on typical resin portfolios. Practical options for 2026 include hedging programs tied to energy indexes, negotiating longer‑term offtake with staggered price collars, and qualifying multi‑sourced feedstock streams including semi‑synthetic alternatives.
- R&D and product roadmaps
Regulatory and customer pressure for sustainability is accelerating development of bio‑based and hybrid chemistries. The report maps risk/reward profiles for electrifying R&D pipelines: incremental reformulations to reduce chemical load, higher‑efficiency GPAM and amphoteric PAM blends for recycled fiber furnishes, and starch‑polymer hybrids that preserve performance while lowering synthetic content. For 2026, we advise a two‑track R&D posture — defend core PAM offerings (performance and dosing reliability) while fast‑tracking at least one low‑carbon/bio‑augmented formulation to pilot scale.
- Commercial and go‑to‑market tactics
Given moderate market concentration among global suppliers, differentiation and service models will matter as much as price. The research recommends pricing architectures that couple product tiers with value‑based outcomes (strength per basis weight, energy savings from reduced refining) and performance guarantees supported by digital dosing telemetry. For tissue and packaging customers, “outcome contracts” that share productivity upside create stickiness and improve lifetime customer economics.
- Manufacturing & operations
Operational levers — consistency of polymer attributes, batch traceability, and optimized dosing equipment — directly affect mill runnability and customer retention. Capital allocation in 2026 should prioritize modular upgrades in mixing and quality control, and investments in remote monitoring to reduce on‑site troubleshooting. The report includes a practical checklist of plant retrofits and their expected paybacks under conservative volume scenarios.
- M&A, partnerships and route to scale
The market’s CR metrics indicate room for strategic consolidation alongside meaningful regional champions. For acquirers, attractively priced bolt‑on targets include regional specialties with strong customer relationships and niche chemistries (e.g., starch engineering). For incumbents, alliances with dosing/equipment providers and fiber innovators offer faster route to integrated value propositions than greenfield capacity expansion.
Competitive landscape — who matters and why
The competitive environment blends large, diversified chemical players with focused specialty formulators and regional manufacturers. Global suppliers with extensive portfolios and technical service footprints are well positioned to capture value from large mill conversions and sustainability programs. Equally, agile specialty firms compete on speed, bespoke formulations, and close mill collaboration.
- Solenis — Broad additive portfolio across amphoteric, anionic and cationic chemistries; strengths in field service and bundled performance additives that target runnability and CO2/resource efficiency outcomes (recent recognition at a major mill underlines commercial traction).
- Kemira — Portfolio play with both synthetic polyacrylamide chemistry and engineered cellulose; recent new product releases emphasize pump‑and‑go convenience for tissue manufacturers, enabling fast adoption with clear operational benefits.
- Buckman, SNF Group, BASF, Harima — These players combine broad geographic networks, technical service, and product depth across dry and wet strength spaces; their competitive posture focuses on system solutions and long‑term supply agreements.
- Regional and specialty players (Ecolab/Nalco Water, Derypol, Aurora Specialty Chemistries, Thermax, Aries Chemical, Seiko PMC, and Chinese manufacturers) — Offer targeted chemistries, cost advantages in local markets, or rapid co‑development pathways for specific fiber furnishes and recycled content challenges.
Recent product and application milestones documented in the study are instructive: in 2025 Kemira launched a pump‑and‑go solution built to deliver step‑change strength improvements and operational simplicity, while a leading supplier’s field program demonstrated measurable CO2 and resource benefits tied to a dry strength additive suite. These developments exemplify the competitive mix of product performance, sustainability claims, and practical dosing/service models that will decide customer choices in 2026.
Segment dynamics and structural themes (high‑level)
The market comprises a set of well‑understood chemistry buckets (polyacrylamide variants, glyoxalated polyacrylamide, starch‑based resins, amphoteric grades) and end‑use families (packaging & industrial, tissue & towel, graphic grades, and specialty segments). While the full report contains the detailed segmentation tables and region/application breakdowns, the strategic conclusion is clear: success depends on matching chemistry selection and service design to specific mill constraints (fiber mix, refining strategy, machine speed) rather than a one‑size‑fits‑all commercial play.
Two structural trends worth flagging for 2026 planning: (1) recycled fiber and lightweighting initiatives increase the technical premium for high‑performance dry strength resins, and (2) sustainability and regulatory scrutiny drive adoption of lower‑intensity chemistries and documentation of life‑cycle improvements.
What’s in the full report — operationally focussed deliverables
- Validated market sizing (2020–2025) and scenario forecasts (2026–2032) in USD Million, with sensitivity to raw material price bands
- Detailed supplier profiles and benchmarking versus commercial and service KPIs
- Granular application and type segmentation (available in the full dataset) and adoption curves by paper grade
- Practical commercial playbooks: pricing models, outcome contracting templates, and customer onboarding flows
- R&D and formulation decision matrices (cost, performance, regulatory fit), plus a prioritized list of reformulation pilots with estimated time‑to‑market
- Supply chain stress tests, hedging scenarios for acrylamide price swings, and inventory strategies for 90‑day and 12‑month horizons
- M&A screening checklist and integration playbook for bolt‑on targets
- Case studies and mill‑level ROI analyses demonstrating how vendors translated chemistry improvements into measurable basis weight, energy, or CO2 gains
How to use the research in your 90‑day and 12‑month plans
- 90 days: Run supplier stress‑tests, obtain updated acrylamide exposure statements, and pilot one outcome‑based commercial model with a strategic mill partner.
- 6–12 months: Initiate a low‑carbon formulation pilot, lock in staged feedstock contracts, and evaluate at least one regional M&A or alliance opportunity to shore up market position.
Conclusion — why this report matters for 2026
2026 will be a year where execution discipline outperforms bold scale‑up bets. With a mid‑single‑digit CAGR pathway and visible feedstock volatility, the market rewards companies that combine technical excellence with commercial creativity — outcome contracting, digital dosing, and modular manufacturing upgrades. PW Consulting’s report is structured to convert macro forecasts into mill‑level choices: what to buy, what to pilot, and what to bid. It equips decision‑makers with the models and playbooks necessary to protect margins, accelerate sustainable product transitions, and capture profitable share in an evolving competitive set.
For the full dataset, proprietary segmentation breakdowns, supplier scorecards, and the detailed ROI case studies referenced above, access the complete Worldwide Paper Dry Strength Resin Market report on the PW Consulting website. The public synopsis you have read is intended to establish the analytical frame; the full study contains the granular intelligence required to operationalize a winning 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Dry Strength Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com