

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cotton Bedsheets Market at USD 18,650 Million in 2025; Asia Pacific Leads with USD 7,738.9 Million as 5.12% CAGR Projected to 2032

Worldwide Cotton Bedsheets Market: Strategic Roadmap for 2026 Decision-Makers
PW Consulting today releases a forward-looking briefing derived from its comprehensive Worldwide Cotton Bedsheets Market study (base year 2025), designed to equip C-suite executives, procurement leaders, product strategists and private equity investors with the operationally actionable intelligence they will need throughout 2026. The full study contains detailed segment-level data, scenario modelling and proprietary vendor benchmarks; this press release summarizes the strategic implications and high-level findings while intentionally reserving granular splits to encourage direct access to the complete report.
Worldwide Cotton Bedsheets Market
Executive summary
The global cotton bedsheets market reached USD 18,650 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.12% across the 2026–2032 forecast window, reaching an overall market size north of USD 26,400 Million by 2032 under the base case scenario. Market structure remains highly fragmented (CR3 ~12.5%; CR5 ~18.6%), which creates differentiated playbooks for scale players, regional specialists and branded direct-to-consumer upstarts.
Worldwide Cotton Bedsheets Market
Why this report matters for 2026 planning
-
Macro-to-micro visibility for procurement: Our modelling links global cotton supply/demand and price scenarios to finished goods cost curves, enabling procurement teams to quantify margin exposure at discrete cotton-price points and to design practical hedging and contracting strategies.
Worldwide Cotton Bedsheets Market -
Channel-aware product roadmaps: The research disaggregates demand dynamics by material types and end-user categories, creating SKU rationalization and premiumization strategies tailored for e‑commerce, hospitality and institutional channels.
-
Near-term tactical playbooks: The report provides immediate 12–18 month playbooks — from short-term supply reallocation and inventory buffers to rapid price-protection clauses for major retail contracts.
-
M&A and partnership prioritization: Using our eight-factor valuation overlay, the study identifies the characteristics of the most attractive acquisition targets and JV partners for rapid scale or margin improvement, without publishing target-level valuations in this release.
Market dynamics that will define 2026
-
Supply-demand balance and price volatility: Global cotton production for the 2025/26 season is estimated around 121.9 million bales while consumption is approximately 119.1 million bales (USDA FAS). That tight balance, combined with periodic weather and geopolitical risk, is a primary driver behind recent price moves — U.S. season-average farm price for 2025/26 is forecast near $0.61/lb and cotton futures spiked close to $0.80/lb in April 2026 (Industry Price Data). For manufacturers and large buyers, these movements can swing gross margins materially within a quarter.
-
Trade policy and nearshoring: Trade actions — including adjustments to U.S. Section 301 exclusions observed in 2025 — are reshaping cost math for importers and prompting capacity shifts or nearshoring of finishing operations to mitigate tariff exposure (U.S. Customs and industry tariff updates, 2025).
-
Regulatory and classification continuity: Bed linen of cotton remains actively traded under well-established tariff classifications (HTSUS Chapter 63), a factor that simplifies customs compliance planning but does not remove the need for tactical responses to evolving trade measures (USITC / OEC data, 2024–2026).
-
Fragmentation and opportunity: Low concentration ratios indicate that scale economies are not yet monopolizing the market; nimble branded entrants and regional exporters continue to capture share by combining localized supply advantages with differentiated product positioning.
Segmentation and product posture (high level)
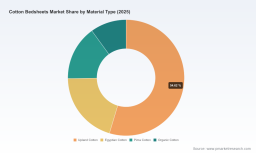
The market continues to bifurcate along two material axes — classical commodity cottons and value-differentiated varieties (e.g., long-staple and organic cotton). Concurrently, end-use demand is stratified across residential retail, hospitality procurement and institutionally oriented buyers such as healthcare. Our full analysis maps how each material-to-channel pairing behaves under multiple demand and price regimes, and prescribes product and pricing architectures for each.
Competitive landscape — strategic takeaways
We analyzed a cross-section of incumbent manufacturers, hospitality suppliers and consumer brands. High-level observations include:
-
Scale manufacturers with vertical integration (e.g., spinning-to-finishing capabilities) hold durable cost advantages when cotton price volatility is high. Their primary strategic levers are capacity utilization, bulk raw-material contracting and direct relationships with major retail/hospitality buyers.
-
Specialized suppliers focused on hospitality leverage product durability, service-level agreements and rapid replenishment as competitive moats. For hotels and institutional buyers, total cost of ownership (durability + wash cycles) increasingly trumps unit price.
-
Premium direct-to-consumer brands have demonstrated that consumer willingness to pay for provenance and certified organic cotton can support higher gross margins, but scale and customer acquisition costs present persistent headwinds.
Profiles of notable players (select insights):
-
Welspun Living Limited (India): Large-scale global manufacturer with retail and hospitality reach; strategic strengths include global distribution and manufacturing scale, enabling aggressive bid strategies for large contracts.
-
Trident Limited (India): Vertically integrated producer emphasizing sustainable manufacturing; well-positioned to supply hospitality-grade bedding while pursuing premiumization through certification and traceability initiatives.
-
Indo Count Industries (India): Focuses on premium and export markets, pairing global cotton sourcing with advanced finishing; benefits from diversified channel exposure.
-
Standard Textile (United States): Vertically integrated supplier concentrated on hospitality innovation and textile systems; competitive moat rests on service-level reliability for institutional clients.
-
1888 Mills (United States): Active in 100% cotton lines and notable for consumer-recognized marks (e.g., Seal of Cotton); product launches in late 2025 expanded its mid-market appeal and reinforced consumer trust in branded cotton offerings.
-
Boll & Branch (United States): Premium DTC brand that leverages ethical sourcing and organic certification — a useful benchmark for premiumization strategies despite higher acquisition costs.
-
American Textile Company and WestPoint Hospitality: Represent legacy U.S. players supplying both residential and institutional channels; their incumbency in procurement relationships remains a gate to hospitality contracts.
Practical, actionable elements inside the full study
-
Quantified sensitivity matrices linking cotton price, freight and tariffs to finished‑goods gross margins and recommended contract language for price pass-through and force majeure events.
-
Supply‑chain heatmaps highlighting short‑lead finishing hubs, pinch‑points for dyes/chemicals, and recommended dual-sourcing pairs to reduce single‑point failures.
-
Channel-specific SKU architectures and a 90‑day SKU rationalization playbook focused on optimizing inventory turns and reducing hold costs without sacrificing retail shelf presence.
-
Ten practical procurement contract clauses and a model hedging framework combining physical forward coverage and selective futures/options placements.
-
A curated M&A shortlist methodology and thematic targets (e.g., finishing specialists, niche organic-mills, digital-native brands) — with acquisition success levers and post-merger integration checkpoints.
-
Regulatory risk matrix covering tariff scenarios, customs classification issues and recommended compliance checklists for cross-border supply chains.
Recommended 2026 playbook — five priority moves
-
Lock forward supply selectively: Combine short‑term physical coverage with strategic options to protect margins while retaining upside exposure if prices ease.
-
Diversify finishing footprints: Move toward multi-region finishing or contracted co‑packers to neutralize single-market tariff shocks and port congestion risk.
-
Prioritize durability metrics for hospitality bids: For hotel and institutional business, quantify lifecycle cost per wash cycle and use it to win longer-term service agreements.
-
Invest in premium/traceable lines incrementally: Pilot organic and long‑staple product lines with a disciplined CAC/LTV framework before scaling.
-
Target bolt‑on acquisitions that add finishing/traceability capabilities rather than high-cost customer aggregation — small technical assets can unlock substantial margin improvements.
Closing — how to use this insight
For executives preparing 2026 budgets and three‑year strategic plans, the report offers a bridge between macro commodity dynamics and operational levers at the SKU and factory level. It converts market scenarios into playbooks you can apply immediately — from procurement and pricing to product and M&A. We have deliberately withheld certain granular regional and application-level revenue splits and company-level shares from this press release; those proprietary tables, interactive charts and downloadable models are available in the complete Worldwide Cotton Bedsheets Market report.
To request the full report, interactive dashboards, or a tailored executive briefing for your organization, please visit PW Consulting’s research portal or contact our industry team directly. Equip your 2026 planning process with the scenario-tested strategies that convert cotton-market volatility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Cotton Bedsheets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com