

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Condensation Cure Silicone Rubber Market to Rise from USD 2,253.33 Million in 2025 to USD 3,132.81 Million by 2032 at a 4.82% CAGR

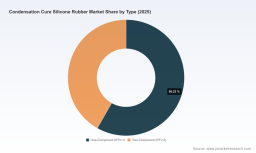
Worldwide Condensation Cure Silicone Rubber Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market brief on the Worldwide Condensation Cure Silicone Rubber market synthesizes proprietary forecasting, supplier benchmarking, raw‑material scenario analysis and go‑to‑market playbooks to inform executive decisions in 2026. The market is in a steady phase of recovery and structural realignment: after multi‑year growth through 2020–2025, our base‑year snapshot (2025) shows a global market on the order of USD 2.25 billion, and our forecast points to a compound annual growth rate (CAGR) of about 4.82% across 2026–2032, reaching roughly USD 3.13 billion by 2032. This release explains why these macro dynamics matter for procurement, product development and M&A agendas in the coming 12–36 months — while reserving the granular splits and proprietary tables for the full report.
Worldwide Condensation Cure Silicone Rubber Market
Market Snapshot: Why Condensation Cure Silicones Matter Now
-
Market trajectory and stability: After a period of cyclical volatility in the early 2020s, condensation‑cure silicone rubber demand has stabilized around the mid‑single‑billion USD mark globally. The forecasted CAGR near 4.8% reflects a mix of steady end‑market demand (molding, construction, specialty repair and industrial maintenance) and selective displacement by addition‑cure systems where performance requirements demand it.
Worldwide Condensation Cure Silicone Rubber Market -
Concentration dynamics: The market shows moderate concentration — our concentration analysis indicates that the top three and top five suppliers command a meaningful share of the industry value pool. This creates differentiated supplier power across customer segments and geographies, and makes supplier strategy a central lever for price and availability management.
Worldwide Condensation Cure Silicone Rubber Market -
Cost pressure from inputs: Raw‑material cost inflation, especially for cyclic siloxane intermediates (notably D4) and industrial silicone oils, is a near‑term margin risk for suppliers and a price‑pass‑through risk for buyers. D4 price moves in 2025 (exceeding a 20% year‑on‑year increase) materially altered cost curves; industrial silicone oil prices in China also rose into higher bands, with high‑viscosity and modified grades commanding further premiums. Regulatory tightening in production hubs has exacerbated supply pressure.
What the PW Consulting Report Delivers (Practical, Actionable Content)
-
Robust market sizing and scenarios: A conservative baseline forecast complemented by upside and downside scenarios driven by raw‑material shocks, regional demand shifts and substitution rates. Models are dynamic and ready for client customization.
-
Quantitative sensitivity analysis: Price and margin sensitivity to D4 and silicone oil price pathways, with tipping points for supplier profitability and customer price pass‑through thresholds.
-
Supply‑chain heat maps: End‑to‑end mapping of feedstock exposure, major refineries and conversion nodes, and logistics chokepoints that matter to delivery reliability and working‑capital planning.
-
Commercial playbooks: Segment‑specific GTM (go‑to‑market) strategies for manufacturers and distributors — including premiumization paths (higher‑value, faster‑curing grades), contract structures, and channel optimization.
-
M&A and partnership screening: A ranked shortlist of target archetypes, valuation sensitivities, and integration checklists for bolt‑on and capability‑acquisition plays.
-
Regulatory and compliance primer: Practical steps to manage environmental and chemical compliance risks, particularly given stricter policies in major producing countries that have already affected cost and supply profiles.
Competitive Landscape: Who Matters and Why
The condensation‑cure segment remains a mix of specialized formulators, chemical majors and niche regional players. PW Consulting’s assessment focuses on the strategic positioning and capability vectors of core suppliers.
-
Smooth‑On, Inc. — a recognized specialist in mold‑making rubbers with a broad product range that spans multiple Shore‑hardness grades and established brand equity among prototyping and artistic users. Their strength is product breadth and channel reach in Western markets.
-
Polytek Development Corp. — known for robust, tear‑resistant condensation formulations. Polytek’s value proposition is performance and user familiarity in flexible mold making and casting workflows.
-
Silicones, Inc. and Silpak, Inc. — US‑based formulators with long track records in tin‑catalyzed RTV‑2 systems, offering both off‑the‑shelf and tailored compounds for electronics potting, special effects, and industrial molding.
-
CHT Group and Elkem Silicones — established suppliers with global ingredient and formulation capabilities; their competitive edge lies in integrated offerings (polymers, catalysts, additives) and technical services for architectural and industrial molding applications. CHT’s visible participation at recent industry forums underscores a continued commercial focus on product and channel engagement.
-
Shin‑Etsu and Momentive — larger chemical incumbents supplying condensation grades alongside broader silicone portfolios. These players can leverage scale, global technical support, and rapid‑cure product variants for higher‑throughput industrial customers.
-
BBN Materials — a China‑based specialist competitive on lead‑time flexibility, customization and price for local and regional customers; represents the incremental competitive pressure on global suppliers when buyers prioritize unit economics and local supply certainty.
Tactically, the competitive field is bifurcating: branded/formulation leaders defend value through technical service and proprietary catalyst systems, while regional specialists compete on cost, customization and localized delivery. This bifurcation creates win opportunities for mid‑sized suppliers pursuing either premiumization or regional consolidation strategies.
Raw‑Material & Regulatory Dynamics — Operational Implications
-
Feedstock volatility: The D4 price shock in 2025 materially increased upstream costs for condensation systems. Our models isolate the impact on typical condensation formulations and identify the margin erosion thresholds for different customer contract structures.
-
Silicone oil cost and grade scarcity: Industrial silicone oils have moved into higher price bands, with high‑viscosity and modified grades becoming scarce at times. This affects specialty grades used for viscosity control and thixotropy; formulators are responding with additive reformulations and inventory buffering strategies.
-
Regulatory tightening: Stricter environmental policies in major producing regions led to curtailment and higher compliance costs in 2025. For buyers and suppliers, this increases the value of local supply relationships and creates strategic rationale for dual‑sourcing or near‑shoring.
Strategic Priorities for 2026 — A Pragmatic Roadmap
Based on our analysis, we recommend a prioritized set of actions for executive teams evaluating exposure to the condensation‑cure segment in 2026:
-
Short term (0–12 months): Stabilize supply and cost exposure. Negotiate tiered contracts with pass‑through clauses keyed to D4/major oil indices, secure safety stock for high‑usage grades, and run targeted supplier audits focusing on compliance and capacity buffers.
-
Medium term (12–36 months): Differentiate product portfolios. Invest selectively in rapid‑cure and premium grades where margin expansion is achievable; for commodity grades consider strategic partnerships with regional specialists to reduce landed cost and improve responsiveness.
-
Long term (36+ months): Build resilience and capability. Consider M&A to acquire technical catalysts/additives capabilities or regional production footprints; pursue formulation innovation that reduces reliance on constrained intermediates (e.g., alternative chain extenders, recycling of silicone streams where feasible).
How PW Consulting’s Full Report Supports Execution
The condensed release above signals where value and risk converge, but the full PW Consulting report supplies the executable detail executives need to act in 2026. Deliverables include:
-
Downloadable financial models with scenario toggles for raw‑material prices and demand elasticity.
-
Supplier scorecards and a validated M&A target shortlist, with deal rationale and integration risks quantified.
-
Detailed regional, type and application split tables, channel maps and buyer personas (kept private here to protect proprietary segmentation — available in the complete report).
-
Commercial templates (RFP language, sample tiered contract clauses, inventory KPIs) proven in advising clients across manufacturing and distribution tiers.
Conclusion — Decision Imperatives for 2026
Condensation cure silicone rubber occupies a strategically important niche: technically mature but exposed to raw‑material shocks and regulatory pressure. For 2026, the highest‑impact moves are pragmatic: lock supply with flexible price mechanisms, prioritize product streams with resilient margins, and use selective inorganic moves to acquire capability and geographic coverage. PW Consulting’s report is designed as an operational tool for CFOs, Heads of Procurement and Corporate Development teams to convert market foresight into defensible, measurable actions. For the full dataset, proprietary segmentation tables and downloadable models that underpin our recommendations, please access the full report through our official release page.
Recent note — market activity: CHT Group showcased condensation‑cure molding rubbers at a prominent industry expo in late 2025, underlining continued upstream and application‑level engagement by established suppliers. Companies and investors should treat such exhibition activity as a leading indicator of product focus and customer outreach priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com