

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft Load Control Solutions Market Forecast to Reach USD 275.03 Million by 2032, Growing at a 6.72% CAGR

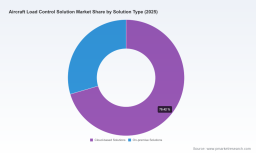
Worldwide Aircraft Load Control Solution Market: Strategic Imperatives for 2026 Decision-Makers
As airlines, ground handlers, and airport operators plan investments and operational transformations for 2026, the emerging contours of the aircraft load control solutions market demand focused strategic responses. PW Consulting’s latest market study—anchored on 2025 as the base year and extending forecasts through 2032—synthesizes financial trajectories, regulatory shifts, vendor capabilities, and actionable implementation roadmaps to inform procurement, integration and partnership decisions. The report is deliberately practice-oriented: it equips executives with the analysis and tools to prioritize initiatives, evaluate vendors, and structure pilots—while reserving detailed segment tables for the complete report to protect competitive value.
Worldwide Aircraft Load Control Solution Market
Market trajectory and what it means for investment timing
Our analysis traces the market from the early-2020 baseline through 2025 and projects forward to 2032. After a recovery and acceleration phase from 2020, the global aircraft load control solutions market reached approximately USD 174.45 Million in 2025. Under the base forecasting scenario, the market continues to expand at a compound annual growth rate (CAGR) of about 6.72% across the 2026–2032 horizon, reaching a projected total market size in 2032 that reflects sustained, structural demand for digitalized weight & balance and load-control capabilities.
Worldwide Aircraft Load Control Solution Market
For decision-makers, this profile signals two practical implications for 2026:
Worldwide Aircraft Load Control Solution Market
- Now is the window to secure technological and integration advantages before the market matures further and differentiation compresses.
- Investment pacing should privilege flexible architectures (cloud-native where appropriate, with robust offline capabilities) and vendor arrangements that permit rapid feature expansion as regulatory and operational requirements evolve.
Why load control is moving from compliance to competitive lever
Historically, load control systems were viewed primarily as a compliance and safety function—ensuring center of gravity limits and correct mass calculations. Today, regulatory stringency (ICAO, FAA, EASA) and NextGen digitalization programs have elevated load control into a multi-dimensional operational lever. Modern systems can reduce fuel burn through optimized trim and Zero Fuel Weight calculations, accelerate turnaround times via automated loadsheet generation, and reduce incident risk through exception-driven workflows. Executives who treat load control as a merely tactical area miss a larger opportunity to extract recurring operational savings and service consistency.
Key dynamics shaping buyer requirements in 2026
- Regulatory acceleration: Ongoing updates from global and regional authorities intensify requirements for verifiable, auditable weight & balance calculations—driving demand for systems that support certification, training records, and traceable change logs.
- Integration expectations: Operators expect seamless integration between load control, flight planning, EFBs, and airport operations platforms. Systems that remain siloed impose manual workarounds and slow adoption.
- Operational models diversifying: Centralized Load Control (CLC) continues to expand alongside decentralized, station-based models. Each model imposes distinct requirements for latency, redundancy and user interface design.
- Cloud adoption with edge resiliency: Buyers favor cloud-first solutions for scale and analytics, but require strong offline/edge capabilities to maintain continuity at remote stations and during connectivity loss.
- Automation and exception handling: Automation reduces human touchpoints, but the residual value is in intelligent exception handling—alerting operators only when manual intervention is needed.
Competitive landscape — practical takeaways
The market features a mix of specialist load-control software providers, established aviation IT integrators, and global ground-handling service operators that offer load control as a managed service. Market concentration metrics indicate a moderately consolidated environment—leading vendors control meaningful shares of demand without creating insurmountable entry barriers for innovative challengers. This mix creates opportunities for both incumbent airlines seeking one-stop solutions and nimble vendors offering rapid, targeted innovation.
- Specialist W&B and load-control vendors: Companies with core products focused exclusively on weight & balance and load planning bring depth in aircraft models, regulatory compliance and domain workflows. Their strength lies in rapid feature development aligned to operational pain points and close co-development with launch customers.
- Aviation IT platform players: Larger IT integrators and flight planning vendors are integrating load-control modules into broader operations suites—an attractive proposition for carriers that prefer fewer vendors and unified data models.
- Managed-service operators: Global ground-handling firms and specialist load control centers have scaled Central Load Control services and can deliver near-immediate operational capacity for airlines seeking to outsource while retaining oversight.
Representative firms covered in the study include a cross-section of these approaches: providers engineering automated weight & balance applications for both narrow- and wide-body fleets; vendors offering high levels of autonomy in loadsheet generation; airlines and handlers operating centralized load control centers; and large aviation IT houses integrating load-control into flight management ecosystems. The full report contains vendor scorecards, comparative feature matrices and procurement-ready evaluation criteria to help buyers narrow choices efficiently.
Market concentration data included in the study (CR3 and CR5 measures) demonstrate that top-tier vendors capture significant, but not dominant, portions of demand—reinforcing that strategic partnerships and proven reference deployments are differentiators more than sole determinants.
Report contents — what practitioners will actually use
The report is engineered as a practitioner's guide for 2026 decision cycles. Contents include:
- Executive dashboard: concise KPIs, market pace indicators, and investment thresholds to support board-level discussions.
- Vendor playbooks: anonymized vendor benchmarking, deployment case studies, and RFP templates tailored to different operational models (CLC, station-based, hybrid).
- Integration blueprints: sequence diagrams and data-mapping templates for connecting load control with flight planning, EFB, baggage and cargo systems, and airport AODB platforms.
- Implementation toolkits: pilot design guides, sample SLA clauses, change-management checklists, training curricula aligned to IATA certification pathways, and cyber/assurance checklists for FAA/EASA compliance.
- ROI and scenario models: customizable financial templates to model fuel savings, turnaround productivity gains, and risk reduction benefits under conservative, base, and accelerated adoption scenarios.
- Regulatory compendium: concise summaries of ICAO/FAA/EASA expectations and practical steps to achieve audit-ready operations.
Use cases and illustrative outcomes
Applied case studies in the report demonstrate how different operator types realize value: an airline that prioritized integration with flight planning and EFB systems cut average turn times through automated loadsheet handoffs; a cargo operator improved payload utilization by refining weight allocation rules; and a ground handler reduced load-related exceptions through centralized reconciliation workflows. These examples are accompanied by the operational metrics and pilot parameters necessary to replicate outcomes.
Risks and uncertainties to plan for in 2026
- Regulatory shifts: Ongoing adaptations in FAA and regional frameworks may require incremental software updates and re-certification work—buyers must include upgrade and validation windows in procurement timelines.
- Interoperability challenges: Legacy systems and diverse data schemas at airports can complicate integration—programs should budget for middleware and mapping resources.
- Data integrity & cybersecurity: Increased digitalization raises exposure; resilience planning and secure authentication are not optional.
- Human factors: The transition to automated processes requires investment in re-skilling and careful user-experience design to maintain operator trust.
Strategic recommendations for 2026
For executives aligning to 2026 objectives, our study recommends a three-track strategy:
- Stabilize core operations: Prioritize solutions with proven offline reliability and credentials for regulatory compliance. Short-term pilots should minimize operational disruption while proving automation benefits.
- Architect for integration: Insist on open APIs, standard data models and vendor commitments to integration timelines. Favor solutions that can plug into existing flight planning, EFB and AODB layers without wholesale replacement.
- Scale through outcome contracts: Structure vendor relationships around performance and outcomes—fuel-efficiency milestones, turnaround-time reductions, and accuracy targets—rather than pure license models, to align incentives.
Implications for vendors and investors
Vendors should double down on three value levers: regulatory compliance features and documentation, automation and exception-handling capabilities, and seamless integration. Investors should favor firms with demonstrated deployments across multiple operational models and those showing durable partnerships with major airline or ground-handling reference customers. Managed-service models remain attractive for rapid scale, but pure-play software providers with strong integration frameworks present compelling margin and product differentiation opportunities.
How this report supports 2026 decision-making
PW Consulting’s report is designed to move beyond descriptive market data: it supplies procurement teams with RFP-ready materials, informs IT architecture choices with practical integration mapping, and supplies finance teams with rigorous ROI templates calibrated to real-world pilot outcomes. The combination of market-level forecasting, vendor analysis, regulatory context and implementation toolkits aims to shorten procurement cycles, reduce deployment risk, and accelerate the realization of operational value.
For leaders planning capital and operational budgets in 2026, this IP allows you to prioritize initiatives, benchmark vendor claims against anonymized peer cases, and structure contracts that preserve upside while sharing implementation risk. The full study contains the detailed segment matrices, vendor scorecards, and appendices that procurement and technical teams will require to execute with confidence.
Where to go next
This briefing is a strategic preview crafted to demonstrate the depth and practical utility of the full PW Consulting study. To access the complete vendor benchmarking, segment detail, downloadable RFP and ROI templates, and step-by-step pilot plans that underpin the recommendations above, please consult the full report page on our website. PW Consulting’s research team is also available for tailored briefings and implementation advisory to support procurement and integration programs commencing in 2026.
Prepared by PW Consulting — Senior Strategy & Industry Analysis. For practitioners who must convert regulatory pressure and digital opportunity into measurable operational value in 2026, the right combination of technology, integration discipline and vendor governance will determine who captures the productivity and fuel-efficiency gains embedded in the aircraft load control transition.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com