

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide DC Power Supplies and Electronic Power Loads Market Set to Grow at a 6.42% CAGR Through 2032

Worldwide DC Power Supplies and Electronic Power Loads Market — Strategic Imperatives for 2026
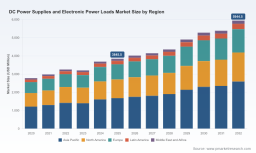
PW Consulting today publishes an advanced industry briefing aligned with our full report "Worldwide DC Power Supplies and Electronic Power Loads Market" (base year 2025, forecast period 2026–2032). The market reached roughly USD 3.85 billion in 2025 and, under our central scenario, is expected to expand at a compound annual growth rate (CAGR) of 6.42% through 2032 — approaching an estimated USD 5.9–6.0 billion by the end of the forecast horizon. For executives planning capital allocation, R&D roadmaps, supply-chain responses and M&A activity in 2026, the findings crystallize where measurable risks and high-return opportunities converge.
Worldwide DC Power Supplies and Electronic Power Loads Market
Why 2026 is a Pivotal Inflection Point
-
Demand profile shift: Power electronics is being re-shaped by rapid electrification (notably EV traction and ancillary systems), expansion of hyperscale data center capacity, and higher-performance power regulation in AI servers. These structural trends are increasing demand for higher power density, higher efficiency, and bi-directional/regenerative capabilities in both DC power supplies and electronic loads.
Worldwide DC Power Supplies and Electronic Power Loads Market -
Technology acceleration: SiC and GaN devices have moved from niche to mainstream in traction and high-efficiency conversion platforms. This accelerates architectural redesigns across OEMs and test houses, creating winners and losers depending on integration speed and IP holdings.
Worldwide DC Power Supplies and Electronic Power Loads Market -
Supply-side stressors: 2025–Q1 2026 saw a combination of policy and component cost shocks — export controls on critical materials, new trade measures targeting processed minerals, and material/semiconductor price inflation for key passive and active components. These factors are driving longer lead times, higher unit costs, and renewed incentive for supplier consolidation or vertical integration.
What PW Consulting’s Report Delivers — Practical, Actionable Intelligence
The full study is built for decision-makers who require more than directional narrative. Highlights include:
-
Proprietary market model: A transparent, auditable demand model calibrated to 2020–2025 historicals and scenario-driven forecasts for 2026–2032, enabling “what-if” analyses for volume, pricing and technology adoption assumptions.
-
Competitive benchmarking: Cross-metric scorecards (technology portfolio, vertical focus, go-to-market, manufacturing footprint, channel strength, pricing power and service capabilities) for incumbent and emerging suppliers.
-
Supply-chain heat maps: Identification of critical nodes and component sensitivities (MLCCs, tantalum capacitors, MOSFET/IGBT supply) together with mitigation options — from hedging strategies to dual-sourcing and nearshoring tradeoffs.
-
Go-to-market playbooks: Tailored strategies for OEMs, contract manufacturers and test-house operators to capture share in high-growth adjacencies (EV charging test, battery simulation, datacom power validation and ATE for semiconductors).
-
Regulatory and raw-material tracker: Continuous monitoring framework to quantify exposure to policy actions and export controls, with trigger-based mitigation actions for procurement and product qualification timelines.
-
M&A and partnership scorecards: Identification of bolt-on and capacity-expansion targets, together with synergy and integration risk estimates under multiple scenarios.
To preserve the strategic advantage for report subscribers, granular regional and end-use splits, detailed product-level revenue ladders and company-level revenue breakdowns are reserved for the full deliverable.
Competitive Landscape — Strategic Themes and Company Positioning
The market exhibits moderate concentration: in our assessment the top three suppliers account for under half the market while the top five capture just over half — a structure that enables global leaders to set technical direction while leaving room for specialist challengers. Key strategic archetypes we observe include:
-
Precision measurement and test specialists (e.g., Keysight Technologies, Chroma ATE, EA Elektro-Automatik): These companies compete on accuracy, automation, and ATE integration. Their product roadmaps emphasize high-precision programmable supplies, regenerative loads and software-driven test orchestration tailored for semiconductor fabs, EV powertrain validation and battery R&D.
-
High-power engineered systems (e.g., Magna-Power, Advanced Energy): Focused on high-voltage/high-current platforms, many are expanding modular architectures and cooling technologies to serve industrial and large-scale test facilities.
-
High-volume industrial/commercial suppliers (e.g., Mean Well, Delta, TDK-Lambda, XP Power): These providers emphasize robust supply chains, cost-optimized designs and adoption of SiC/GaN at scale for efficiency gains in telecom, industrial automation and medical equipment.
-
High-density module innovators (e.g., Vicor, Murata): Concentrated on power conversion modules and embedded DC-DC solutions for computing and defense electronics where power density and thermal management are premium attributes.
-
Service and quick-ship specialists (e.g., Acopian, B&K Precision): Competitive differentiation comes from availability, customization speed and aftersales service for bench and education markets.
Recent product introductions — from very-high-voltage 1U DC supplies to SOSA-aligned VPX power modules and new programmable bench supplies — confirm that incumbents are diversifying across both ends of the performance spectrum. New entries and incremental launches show the market’s appetite for higher voltage capability, compact footprint and test automation features.
Implications of Raw-Material and Policy Shifts
Policy and material-cost shocks observed in 2025–early 2026 materially alter supplier economics and design choices:
-
Export controls and trade actions raise the strategic value of digitized supplier visibility and geographic diversification. Procurement teams must quantify exposure not only to raw materials broadly, but to facility- and country-specific process capabilities that feed magnetics and passive component supply.
-
Component inflation — notably in capacitors and discrete power semiconductors — is prompting redesigns that reduce part-count, shift to alternative topologies, or outright substitute technologies (e.g., reduced MLCC reliance, earlier adoption of SiC/GaN where thermal and efficiency payback exists).
-
Lengthening lead times for high-voltage MOSFETs and IGBTs creates a premium for flexible bill-of-materials and validated second-source strategies; margin management will increasingly depend on pass-through mechanisms and value-added services.
Top-line Strategic Recommendations for 2026 Executives
-
Re-align procurement to strategic sourcing: Move from transaction-based buying to layered contracts that include capacity reservations, price collars and shared-risk clauses with key suppliers.
-
Accelerate SiC/GaN adoption where system-level economics justify it: Prioritize pilot programs in high-value segments (traction inverters, DC-DC converters for telecom and hyperscale UPS) and fast-follower designs elsewhere.
-
Invest in test automation and regenerative load capabilities: These reduce test cycle cost and energy consumption while opening new service revenue streams for test-as-a-service.
-
Develop a scenario-driven inventory playbook: Maintain trigger-based buffer strategies keyed to supplier lead-time, component price delta and demand elasticity.
-
Pursue targeted M&A or JVs to fill capability gaps: Focus on power-module IP, thermal management, and regenerative technologies to accelerate time-to-market.
-
Differentiate via lifecycle services: Offer calibration, upgrades, and test program maintenance to capture higher-margin recurring revenue.
Scenario Playbooks and KPIs
We recommend a three-scenario planning approach for 2026: baseline (steady demand growth as per the CAGR), supply-constrained (short-term component price and lead-time spikes) and demand-accelerated (AI/data center-driven surge). Key actionable KPIs to monitor include order book velocity, BOM cost inflation, supplier single-source ratios, and time-to-qualified-second-source. Each KPI should be mapped to pre-approved responses (e.g., material hedges, price-pass clauses, qualification sprint teams).
Conclusion — The Strategic Value of the Full Report
For executives who must translate macro growth (projected market expansion and a healthy CAGR) into executable plans in 2026, this PW Consulting study provides the modeling, competitive insight, and practical playbooks needed to reduce risk and seize opportunity. The summary above is intentionally selective — the full report contains the detailed regional and end-use segmentation, company-level models, priority partner lists, and financial scenarios that underpin these recommendations.
To access the full diagnostics, proprietary models and executable templates that support strategic decisions in 2026, visit PW Consulting’s report page or contact our industry practice for a briefing tailored to your firm’s position in the power-electronics value chain.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com