

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide MLCC Dielectric Materials Market at USD 1,856.4 Million in 2025, Projected to Grow at 7.05% CAGR Through 2032

Strategic Preview: Worldwide MLCC Dielectric Materials Market — 2026 Imperatives for Executive Decision-Making
As PW Consulting publishes its latest market study on the Worldwide MLCC Dielectric Materials Market (base year 2025; forecast period 2026–2032), one clear signal emerges for 2026 planning cycles: this market is on a sustained growth trajectory. Our modelling shows an aggregate market of approximately USD 1.86 billion in 2025, expanding at a compound annual growth rate (CAGR) of about 7.05% to approach nearly USD 3.0 billion by 2032. For C-suite leaders making capital allocation, supply-chain, and R&D decisions in 2026, that macro dynamic creates both runway and urgency—opportunities require execution now, and mistakes compound quickly in a market that rewards technical differentiation and supply resilience.
Worldwide MLCC Dielectric Materials Market
Why this report matters to 2026 strategy
- Actionable foresight: We translate macro growth into discrete strategic choices—technology bets, supplier commitments, and go-to-market moves—that must be decided in 2026 to influence outcomes across the 2026–2032 horizon.
- Risk-to-reward clarity: The market’s growth is accompanied by concentration and material supply nuances that reshape bargaining power and margin pools. Our analysis isolates where competitive advantage will accrue.
- Playbook orientation: Beyond forecast tables, the study delivers checklists, supplier scorecards, and investment templates designed to accelerate decision cycles and reduce execution risk.
Market structure and competitive positioning — strategic takeaways
The MLCC dielectric materials market combines technical intensity with moderate to high market concentration. The top three suppliers capture a material majority of the market, while the top five approach near-complete dominance—an oligopolistic topology that elevates the strategic importance of partnerships, technology licensing, and targeted M&A for challengers. For incumbents, scale and proprietary dielectric formulations remain powerful moat elements; for challengers, niche specialization and vertical-integration into powder supply can be effective routes to value.
Worldwide MLCC Dielectric Materials Market
- Incumbent strengths: Firms such as Murata, Samsung Electro-Mechanics, and TDK leverage deep in-house dielectric R&D and production scale to push miniaturization, automotive-grade qualification, and high-capacitance layering. Their product roadmaps emphasize both ultra-miniature high-capacitance MLCCs and high-reliability C0G/X7R variants for demanding end-markets.
- Integrated suppliers & materials specialists: Players like Yageo (inclusive of KEMET/AVX portfolios), Taiyo Yuden, and Kyocera bring combined capabilities spanning MLCC assembly, dielectric formulation, and application know-how—enabling rapid qualification into automotive, medical, and aerospace programs.
- Dielectric powder specialists: Suppliers such as Prosperity Dielectrics, Vibrantz Technologies, and Sakai Chemical hold strategic leverage in the raw-materials chain—particularly high-purity barium titanate grades produced via hydrothermal routes. Control of powder quality and formulation know-how is increasingly a gating factor for high-performance MLCCs.
Recent vendor moves highlight competitive vectors that matter in 2026. Murata’s ramp to mass-produce 0402 high-capacitance MLCCs (announced July 2025) underscores the race on miniaturization and capacitance density; TDK’s expansions of automotive and low-resistance soft-termination MLCC lines (2024–2025) reflect sustained investment toward EV and automotive electrification requirements. These developments signal that technical differentiation—rather than price alone—will be the primary battleground over the next planning horizon.
Worldwide MLCC Dielectric Materials Market
Material and supply-chain dynamics — what to watch
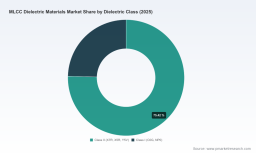
At the material level, barium titanate (BaTiO3) continues to be the foundational dielectric for both Class I and Class II MLCCs, with specialized grades and dopants (including rare-earth additions, zirconates, and stannates) determining performance in temperature stability, capacitance density, and voltage endurance. Japanese suppliers retain leadership in high-purity hydrothermal BaTiO3 production—creating a geopolitical and supplier-concentration vector that procurement teams must actively manage.
- Supply risk and sourcing strategies: Given concentration in high-purity powder supply, companies should evaluate multi-sourcing, strategic inventory buffering, and selective backward integration. Long-term offtake contracts with defined quality gates are increasingly standard negotiating tools.
- Regulatory and sustainability pressure: The industry is moving toward lead-free, RoHS-compliant dielectric formulations. Compliance roadmaps affect material selection, costs, and qualification timelines—especially for automotive and medical customers where certifications can extend lead times.
- Formulation innovation as competitive edge: Proprietary blends (e.g., rare-earth-doped oxides, controlled zirconate/stannate mixes) enable unique performance trade-offs—making R&D pipelines and IP portfolios central to differentiation strategies.
Demand drivers and commercial implications
Demand remains underpinned by three converging forces: (1) the continual miniaturization trend in consumer electronics and mobile devices requiring higher capacitance per unit volume; (2) the electrification and electronic content growth in automotive platforms (including EV power electronics and ADAS sensor suites) that require automotive-grade MLCCs; and (3) infrastructure buildouts—5G, industrial automation, and data-center edge compute—that raise requirements for high-reliability, high-frequency components.
These drivers create uneven demands across dielectric classes and material formulations, with pockets of premium pricing for high-performance, qualified dielectrics. Commercial teams should therefore re-evaluate pricing architectures, channel incentives, and qualification roadmaps to capture upside in premium segments while protecting margin in commoditized tiers.
What the PW Consulting report provides (practical modules)
- Forward-looking demand model (2026–2032) calibrated to device-level adoption scenarios and supply-side constraints—enabling rapid scenario testing for capex and commercial sensitivity.
- Supplier benchmarking and scorecards that synthesize technical capability, capacity footprint, quality track record, and strategic intent—prepared to support sourcing decisions and partnership negotiations.
- Technology roadmap and patent landscape for dielectric formulations, sintering processes, and miniaturization techniques—intended to inform R&D prioritization and patent-risk assessments.
- Raw-material risk matrix and mitigation playbooks (including multi-sourcing, contract terms, and vertical integration case-studies).
- Go-to-market playbooks for incumbents and entrants, including channel strategies, qualification timelines for automotive and medical applications, pricing frameworks, and M&A targets aligned to capability gaps.
Note: to preserve the commercial value of our primary datasets, this release intentionally refrains from publishing granular regional, application, and material split figures. The full report contains those segment-level forecasts and interactive models for corporate use.
Strategic actions for 2026 — five prioritized moves
- Lock in supply for high-purity powders: Initiate or extend multi-year offtake and quality-guarantee arrangements for BaTiO3 and specialty dopants; evaluate selective equity or JV plays with powder specialists to secure long-term access.
- Accelerate product qualification for high-growth applications: Fast-track automotive and 5G qualification programs by front-loading testing cycles and co-development agreements with key OEMs—time-to-qualification is a competitive weapon.
- Invest selectively in dielectric R&D: Prioritize projects that enable either higher capacitance density in ultra-miniature packages or improved stability for high-voltage/temperature environments; protect these efforts with targeted IP filings.
- Rebalance capex against demand scenarios: Use the provided demand-sensitivity model to align capacity investments with the most probable adoption pathways—avoid overcommitment in cyclic short-term spikes, while ensuring capacity to meet certified, long-cycle automotive contracts.
- Pursue strategic partnerships and tuck-in acquisitions: For OEMs and mid-tier suppliers, acquire or partner to close gaps in powder-formulation, sintering, or termination technologies rather than attempting end-to-end buildouts from scratch.
Competitive scenarios — preparing for 2026 outcomes
We model three plausible competitive outcomes through 2032: consolidation driven by vertical integration; status-quo concentration with technology-led premiumization; and disruptive entry by materials specialists combined with manufacturing partners. Each scenario demands different 2026 moves—from defensive capacity commitments and exclusivity agreements to offensive M&A and R&D acceleration. PW Consulting’s scenario suite maps these outcomes to decision triggers (e.g., inventory cycles, raw-material price shocks, or technology breakthroughs) and prescribes immediate mitigations.
Next steps — how to use this intelligence in 2026 planning
- Procurement leaders: Request the supplier scorecards and risk matrix to re-run sourcing tenders with quality-adjusted total cost of ownership metrics.
- R&D heads: Use the technology roadmap and patent slices to prioritize three high-impact projects for FY2026 and define milestone-based funding releases.
- Corporate development teams: Access the M&A target list and capex overlays to identify bolt-on opportunities and valuation benchmarks consistent with market concentration dynamics.
- Commercial teams: Leverage our go-to-market playbooks to re-shape qualification pipelines and reprioritize customer wins by margin and certification lead times.
PW Consulting’s full Worldwide MLCC Dielectric Materials Market report supplies the segment-level forecasts, interactive modelling tools, and supplier dossiers required to operationalize these recommendations. For leaders drafting 2026 budgets and roadmaps, the choice is simple: use high-fidelity intelligence to lock in scarce advantages now, or accept longer and more expensive catch-up cycles later.
Contact PW Consulting to obtain the complete report, licensing options for the interactive forecast model, and tailored advisory engagements that convert these insights into executable 2026 programs.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com