

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Marine Satellite Internet System Market Poised for 11.22% CAGR in 2026–2032, New Report Reveals

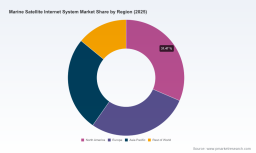
Worldwide Marine Satellite Internet System Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a preview of our authoritative market research — Worldwide Marine Satellite Internet System Market (Base Year: 2025; Forecast Period: 2026–2032). The global market crossed the USD 6.25 billion threshold in 2025 and, under our central scenario, is forecast to roughly double by 2032 to about USD 13.16 billion, reflecting a compound annual growth rate (CAGR) of 11.22% through the forecast window. This preview explains why the report is an essential decision tool for maritime operators, satellite network providers, systems integrators, equipment manufacturers, and public-sector stakeholders planning capital and operational investments in 2026.
Worldwide Marine Satellite Internet System Market
Why this report matters to 2026 decision-makers
-
Market timing and scale: With multi-year expansion driven by LEO deployments, GEO high-throughput satellites (HTS) refresh cycles, and rapid fleet digitization, investment windows in terminal upgrades, hybrid-network procurement, and shore-to-ship integration are opening now — not later. The report translates headline growth into actionable timing recommendations for procurement, fleet rollouts, and vendor negotiations.
Worldwide Marine Satellite Internet System Market -
Risk-adjusted strategy: From spectrum policy shifts to national digital-sovereignty regimes, regulatory risks are now material to network design and supplier selection. Our scenario-based analysis quantifies the impact of regulatory permutations on service availability, pricing, and compliance requirements so executives can hedge effectively.
Worldwide Marine Satellite Internet System Market -
CapEx / OpEx optimization: Operators must choose among CAPEX-heavy VSAT upgrades, lower upfront LEO terminal rollouts, and managed hybrid options. The report contains TCO frameworks and break-even matrices tailored to vessel classes and operational profiles to support board-level CAPEx approvals.
-
Vendor & technology fit: The competitive landscape has shifted from a GEO-dominated ecosystem to a hybrid multi-orbit market. Our comparative vendor evaluation and integration playbooks help procurement teams map supplier capabilities to corporate priorities (resilience, latency, global reach, crew welfare, regulatory compliance).
What’s inside the full report (practical, implementation-focused)
-
Market sizing and growth model: Transparent methodology, base-year calibration (2025), and three forecast scenarios (Conservative, Central, Upside) with sensitivity to terminal costs, airtime pricing, and LEO constellation ramp rates.
-
Strategic playbooks: Actionable decision trees for fleet owners and offshore operators covering retrofit vs. greenfield deployments, phased hybrid adoption, and managed-service vs. in-house network operation models.
-
Vendor intelligence pack: Qualitative assessments and readiness matrices for leading service providers, hub operators, and terminal manufacturers — including service footprints, multi-orbit integration capabilities, and partner ecosystems.
-
TCO & ROI tools: Excel-ready models for capex, opex, crew productivity benefits, and operational efficiencies tied to connectivity upgrades (available as deliverables with the full report).
-
Regulatory and spectrum playbook: Impact analysis of ongoing spectrum policy developments (e.g., Upper C-Band and AWS-3 activity, EU digital network proposals) with compliance checklists by operating region.
-
Operational constraints and integration guidance: Power, weight, and physical footprint checklists for terminal selection; cybersecurity baseline controls for maritime network deployments; and interoperability tests for hybrid architectures.
-
Procurement artifacts: RFP templates, SLA negotiation guides, and contract clauses focused on performance, redundancy, and lawful interception / data sovereignty requirements.
Competitive landscape: who matters and why
The supplier landscape is now a balanced mix of traditional GEO incumbents, emerging LEO disruptors, specialized managed-service players, and terminal manufacturers. Market concentration is meaningful but not insurmountable: the three largest groups account for roughly 42.6% of market value, while the top five approach 58.8%, indicating room for differentiation and new entrants at scale.
-
Viasat (Inmarsat Maritime) — Positioned to serve enterprise networking needs with bonded multi-orbit services that combine GEO HTS capacity with LEO augmentation. Their NexusWave strategy and new terminal platforms focus on bandwidth-hungry applications (video, remote operations) and fleet-level managed services.
-
SpaceX Starlink Maritime — Disruptive on latency and throughput metrics with a product that targets crew welfare and operational connectivity with flat-panel phased-array terminals and simple commercial terms. Starlink’s low-latency proposition forces incumbent pricing and service-bundle responses.
-
Iridium Communications — Retains a unique safety and narrowband position through services like Certus and GMDSS capabilities, making it the de facto global safety-layer and a compelling redundancy partner for hybrid architectures.
-
Managed-network specialists (Marlink, Speedcast, NSSLGlobal, Satcom Global) — These players excel at stitching multi-orbit capacity into resilient networks with value-added services (fleet management, cybersecurity, application hosting) and are central to fleet-scale transformations that favor outcome-based contracts.
-
Terminal and antenna manufacturers (Intellian, KVH, Hughes) — Hardware roadmaps now determine which service profiles are technically feasible on specific vessel types. Recent product releases (e.g., ruggedized LEO-capable terminals and Intellian’s VS60) change retrofit economics and speed of deployment.
-
Satellite operators and constellations (Intelsat/SES, Eutelsat/OneWeb) — The blended GEO+LEO strategies of major operators create differentiated wholesale options for service providers and introduce aggregation opportunities for large-volume fleet customers.
Recent market developments underscore these dynamics: Viasat’s NexusWave evolution and new terminal launches in late 2025; Hughes’ ruggedized transportable LEO terminals certified for OneWeb networks; and high-profile hybrid selections (e.g., Iridium Certus alongside Starlink for major fleets). These moves validate the industry’s pivot to hybrid, multi-orbit solutions and make a compelling case for rapid but measured investment in 2026.
Key strategic implications for executives in 2026
-
Adopt a hybrid-first procurement posture: Single-orbit reliance is now a strategic vulnerability. Design procurement frameworks that prioritize multi-orbit compatibility, clear redundancy provisioning, and staged hardware refreshes to control upgrade cycles.
-
Design for regulatory resilience: Factor spectrum and digital-sovereignty scenarios into network contracts. Insist on contractual mechanisms for lawful-interception support, local termination options where required, and re-route capabilities if national licensing regimes harden.
-
Align CapEx with phased commercial outcomes: Use PW Consulting’s TCO matrices to align terminal investment to measurable outcomes (reduced downtime, crew productivity, data-enabled fuel efficiency) and prefer outcome-based pricing where possible.
-
Prioritize operational integration over headline bandwidth: Real-world benefit comes from integrated applications (telemedicine, voyage optimization, remote maintenance), not raw Mbps alone. Vendor evaluations should include application enablement and managed security services.
-
Manage power and physical constraints early: Terminal power draw and mounting footprint remain practical gating factors on retrofit schedules. Early engineering surveys reduce costly vessel downtime and integration rework.
-
Use staged pilots to de-risk scale: Begin with targeted pilots (route clusters, vessel types) that validate billing models, SLAs, and application performance before fleet-wide rollout.
-
Explore partnership and M&A pathways: For service providers, acquiring or partnering with network aggregation specialists, or terminal OEMs, accelerates multi-orbit offerings and provides differentiation through integration services.
Immediate actions — 90 / 180 / 365 day playbook
-
90 days: Conduct a connectivity audit for high-priority vessels, gather power/space constraints, and identify critical applications. Engage shortlisted vendors for capability demonstrations and obtain baseline TCO inputs.
-
180 days: Run pilot projects across representative vessel types (one-offshore, one merchant, one passenger/cruise) with explicit KPIs tied to operations, safety, and crew welfare. Negotiate pilot-to-scale commercial terms.
-
365 days: Execute scaled rollouts leveraging lessons from pilots, secure multi-year wholesale capacity hedges where appropriate, and formalize managed-service agreements that include security and regulatory compliance guarantees.
Why PW Consulting’s report is the right tool
Our report combines a rigorous forecasting engine calibrated to 2020–2025 historicals, a vendor-ready TCO toolkit, and an actionable implementation playbook shaped by fleet-level operational realities. We balance strategic perspective with implementation detail — providing decision-makers with the confidence to move from evaluation to execution without being forced into premature technical commitments. Importantly, this preview intentionally omits the granular segment-by-segment datapoints and the detailed vendor scoring matrix that are available only in the full report; that level of detail is what equips procurement and technical teams to sign contracts with confidence.
To access the full dataset, proprietary models, and downloadable tools (including the vendor matrix, RFP templates, and TCO spreadsheets) visit our report page and request the complete Worldwide Marine Satellite Internet System Market report. For tailored briefings, scenario workshops, or vendor arbitration support for 2026 tenders, PW Consulting’s maritime connectivity practice is available for direct engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Marine Satellite Internet System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com