

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Whetstones Market to Reach USD 198.73 Million by 2032 from USD 148.5 Million in 2025 — 4.25% CAGR (2026–2032); North America Leads, Market Remains Fragmented

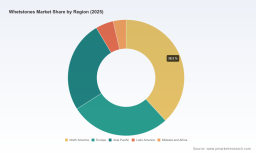
Whetstones Market 2026: Tactical Intelligence for Executives — PW Consulting Releases Whetstones Market (Whetstones Market) Whetstones Market Whetstones Market Insight Brief
Executive summary
PW Consulting’s new Whetstones Market report (base year 2025; forecast period 2026–2032) equips senior leaders with the data, frameworks, and tactical workbooks required to convert sharpening-stone market dynamics into executable decisions in 2026. After tracking historical performance from 2020–2025 and stress-testing multiple demand and supply scenarios, our model shows the global market advancing from roughly USD 148.5 million in 2025 toward an approaching USD 199 million by 2032 at a compound annual growth rate (CAGR) of approximately 4.25% during the forecast window. This steady expansion masks a number of structural shifts — raw-material constraints, evolving channel economics, product-innovation cycles, and changing standards for authenticity and country-of-origin claims — that will define who wins and who is disadvantaged in the next five years.
Whetstones Market
Why this report matters to 2026 decision-makers
- Decision-grade forecasting: We translate the 4.25% CAGR into scenario-specific demand bands keyed to segmentation, price tiering, and channel mix so procurement and revenue leaders can stress-test budgets and inventory plans without overexposure.
- De-risked sourcing playbooks: With raw-material provenance becoming a strategic variable (notably for natural novaculite), we provide supplier concentration analyses, reserve-duration heuristics, and contingency ladders that procurement teams can operationalize this quarter.
- Brand and compliance strategy: Few categories have as much brand resonance tied to origin claims as natural whetstones. Our report decodes FTC “Made in USA” implications and maps certification-dependent premiums by channel and buyer persona.
- CapEx vs. outsource matrix: For manufacturers evaluating resin-bonded or ceramic investments, our cost-per-grit and throughput models convert lab metrics into capex payback timelines and margin sensitivity for 24–36 month investment horizons.
Market trajectory and dynamics — what the numbers hide (and reveal)
The headline trajectory — mid-single-digit CAGR and close to a third growth in nominal market size through 2032 — understates the heterogeneity within the category. Growth is bifurcated between heritage, origin-led natural stones and high-performance synthetic/ceramic offerings that target professional and specialist segments. Meanwhile, mainstream consumer demand remains tied to lifestyle cycles (home cooking and hobbyist blades), product reviews, and influencer-driven sampling — a reality underscored by recent 2026 product tests and editorial roundups.
Whetstones Market
External signals matter. Independent testing and editorial endorsements (notably recent 2026 evaluations by consumer publications) are accelerating trial cycles for premium kits. Simultaneously, ownership of quarry reserves and control of feedstock supplies give certain incumbents defensible cost and quality advantages that do not show up in headline growth figures but are material in margin and scarcity scenarios.
Whetstones Market
What’s inside the PW Consulting Whetstones Market report
We designed the deliverable as an executive toolkit rather than a passive narrative. Key components include:
- Integrated forecast engine: Base and alternative scenarios with month-level roll-ups to support inventory planning, promotional timing, and contract negotiations.
- Channel economics and buyer journey mapping: Margins by distribution model (direct-to-consumer, specialty retail, B2B industrial supply), including CAC, average order value elasticities, and return/defect curves.
- Supply-chain heatmaps: Sourcing nodes for natural and synthetic feedstocks, lead-time matrices, and tiered supplier scorecards for rapid supplier replacement or qualification.
- Product-performance to P&L translation: Testing protocols for grit consistency and blade life that link lab metrics to warranty exposure, R&D prioritization, and pricing ladders.
- M&A and partnership playbook: Valuation ranges, integration checklists, and 100-day value-capture plans tailored for bolt-on acquisitions or contract manufacturing agreements.
- Regulatory & brand-protection module: Compliance checklists for origin-of-manufacture claims, label auditing templates, and consumer-communication frameworks that preserve premium positioning.
- Rapid-deployment tools: Supplier RFP templates, production line yield improvement guides, and go-to-market launch decks for new product introductions.
Note: This release deliberately omits granular segment tables and split-level forecasts. Those datasets, including unit economics by grit and distribution channel cohorts, are available in full with the complete report subscription.
Competitive landscape and strategic positions
The category presents a classic mix of niche heritage producers, vertically integrated quarry owners, high-performance technical specialists, and platform-oriented equipment brands. A few illustrative profiles and the strategic implications we derive for 2026:
- Legacy quarry and vertically integrated players: Firms that control natural novaculite reserves and manage quarry-to-finished-product operations enjoy asymmetric access to scarce feedstock and can command origin premiums. For buyers, this creates supplier dependency risk but also predictable quality benefits. Our playbook prioritizes multi-sourcing and spot-contract strategies for firms reliant on these suppliers.
- Global abrasives majors: Companies with broad abrasives portfolios leverage scale in synthetic abrasives and distribution but compete on different margins and innovation cycles. These incumbents are likely to push higher-velocity, lower-SKU strategies into mass channels — an important consideration for brands planning premium launches.
- Japanese high-performance specialists: Producers focusing on ceramic or advanced bonded stones differentiate on cut-rate, speed, and maintenance convenience; their IP and proprietary production processes can support premium ASPs and tighter retail partnerships.
- Equipment and system vendors: Companies offering sharpening systems (benchtop and guided systems) are converting hobbyists into recurring consumable consumers — a recurring-revenue angle that changes unit economics for manufacturers and distributors alike.
The market concentration remains relatively diffuse: the largest incumbents occupy meaningful positions but do not command dominant aggregate shares. That dispersion creates acquisition and partnership opportunities for growth-oriented firms willing to invest in vertical capabilities or brand-led distribution agreements.
Industry signals and recent developments
- Editorial product testing in early 2026 accelerated consumer awareness for certain collaborative and curated kits — a pattern that typically translates into short-term spikes in conversion rates for retail partners.
- Ongoing, multi-year operations by quarry-owning producers continue to materially constrain high-quality natural-stone supply, necessitating longer-term offtake planning for industrial and professional buyers.
- Technical disclosures on synthetic compositions — especially aluminum oxide and silicon carbide bonding — enable manufacturers to standardize performance claims; firms that can demonstrate reproducible grit performance stand to capitalize on institutional contracts in the culinary and woodworking segments.
Strategic implications and recommendations for 2026
For executives deciding where to allocate scarce strategic bandwidth this year, PW Consulting recommends a two-track approach: protect core supply while selectively investing in product and channel plays that deliver high ROI within 12–24 months.
- Secure feedstock and manage optionality: Negotiate multi-year offtakes with key quarry owners or qualify synthetic alternatives to mitigate price and availability shocks. For procurement, build a triage list: primary, secondary, and emergency suppliers with associated contractual triggers.
- Product-tier rationalization: Reallocate SKU-level investment toward “hero” SKUs that perform best in independent testing and have high cross-sell potential with consumables and systems.
- Channel-led differentiation: Use editorial and earned-media proof points to drive DTC premium conversion while working retail partners on exclusives and limited-edition co-branded lines to maintain retail shelf velocity without sacrificing margin.
- Operationally optimize grit consistency testing: Adopt the report’s lab-to-plant testing protocol to shorten R&D cycles and reduce warranty exposure; small improvements in consistency yield disproportionate savings in rework and returns.
- Prepare for M&A and JV opportunities: With consolidation possibilities high among mid-sized manufacturers, maintain a shortlist of accretive targets and early integration playbooks focused on supply consolidation and brand portfolio rationalization.
How to use this report right away
- Run a 90-day supplier-risk audit using our checklist and prioritize dual-sourcing for any SKU reliant on single-source natural feedstock.
- Apply the quick-scan GTM scorecard to evaluate current product launches; cancel or reallocate budgets from launches scoring below threshold.
- Leverage the channel elasticity matrices to redesign promotional calendars for the next two holiday seasons, aligning inventory with editorial cycles and testing release windows.
Conclusion — an actionable intelligence edge
Topics that will separate winners from laggards in 2026 are practical rather than exotic: feedstock access, reproducible product performance, compliance transparency, and channel sophistication. PW Consulting’s Whetstones Market report bundles these elements — macro forecasting, supplier playbooks, compliance templates, and go-to-market tools — into a compact, implementable resource tailored for procurement, innovation, and commercial leaders.
For executives seeking the full datasets, granular segmentation tables, and downloadable toolkits referenced above, the complete Whetstones Market report and accompanying implementation pack are available through PW Consulting’s Whetstones Market portal. The public summary intentionally omits split-level tables and segment-by-grit economics to protect the actionable workbooks included with the full subscription.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com