

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
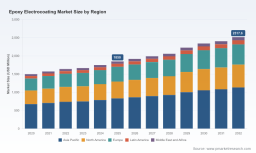
PW Consulting Finds Asia‑Pacific Tops Epoxy Electrocoating Market at USD 833.19 Million in 2025

Epoxy Electrocoating Market — Strategic Imperatives for 2026: A PW Consulting Brief
Executive summary
As markets normalize from pandemic-era distortions and raw material volatility escalates, epoxy electrocoating (e-coat) has moved from a specialist surface-finishing technology to a strategic input for manufacturers prioritizing corrosion protection, compliance, and total cost of ownership. Our new market study (base year 2025, historical series 2020–2025, forecast 2026–2032) quantifies this shift and frames the decisions that matter for procurement, plant investment, and go-to-market strategy in 2026. At a compound annual growth rate (CAGR) of 4.5% across the 2026–2032 forecast window, the industry trajectory is steady—supporting incremental capacity investment, targeted vertical integration, and premiumization where performance differentiates.
Epoxy Electrocoating Market
Macro trajectory: What the numbers tell strategic planners
PW Consulting’s topline view shows the global epoxy electrocoating market expanding from the low‑to‑mid billions in the early 2020s to approximately USD 1,850 Million in 2025, with a projection to exceed USD 2,500 Million by 2032 under our central scenario. The 4.5% CAGR embedded in our forecast reflects a balance of end‑market demand (notably in transportation and industrial equipment), regulatory-driven substitution from solvent-borne systems, and a steady pace of electrified corrosion protection adoption among OEMs and tier suppliers.
Epoxy Electrocoating Market
For 2026 planners, these macro parameters mean two things: first, demand growth supports capacity utilization improvements rather than rapid build-out; second, margin preservation will be heavily influenced by feedstock dynamics and formulation efficiency. The arithmetic of growth is not uniform—geographies and applications will oscillate around the global trend—so strategic moves must be local in execution yet global in risk management.
Epoxy Electrocoating Market
Market dynamics shaping 2026 decisions
-
Raw material volatility and pass‑through pressure. Supply chain stressors and petrochemical feedstock dislocations have produced material cost shocks in late 2025 and into 2026. Manufacturers have responded with price revisions and tighter procurement windows. For companies that buy resins and curing agents, 2026 will require active hedging, longer‑dated contracts for critical inputs, and reformulation levers to protect margin without compromising corrosion performance.
-
Regulatory and trade interventions. Trade enforcement actions and antidumping determinations introduced in 2025 have re‑shaped import economics for several supply corridors. Buyers and exporters need to reassess sourcing strategies to avoid retroactive duties and to exploit regional capacity growth where domestic production is incentivized.
-
Demand composition—industrial resilience, automotive nuance. Underlying demand remains anchored by industrial machinery and automotive OEMs, but growth profiles vary by region and application complexity. OEMs pursuing lighter, corrosion‑resistant, and assembly‑friendly coatings continue to favor e-coat solutions despite incremental processing costs because lifecycle economics and warranty exposure favor superior coating performance.
-
Capex and localization trends. Leading suppliers are expanding manufacturing footprints in proximity to automotive clusters and high-growth industrial markets. These expansions emphasize flexible lines capable of handling next‑generation chemistries and localized service models for OEM integration.
-
Consolidation and competitive concentration. The market shows notable concentration among established coating majors and regional specialists. This structure favors vertically integrated players and those with deep application engineering capability. M&A and joint ventures remain credible strategic levers for scale and technology access in 2026.
Strategic implications and recommended moves for 2026
-
Procurement and supplier strategy. Shift from transactional buying to supplier partnerships. Locking in multi-year supply agreements with indexed pricing combined with collaborative development clauses will mitigate short‑term price spikes while preserving access to formulation expertise. Include clauses that address force majeure and duty reversals given the trade environment.
-
Formulation and R&D prioritization. Invest selectively in low‑energy cure and high‑throw formulations that reduce cycle time and increase first‑pass yields. Where product differentiation is possible, premium formulations that reduce warranty exposure can justify higher up‑front costs.
-
Operational resilience. For manufacturers using e-coat internally, 2026 should be a year of operational audits: focus on bath management, drag‑out recovery, and energy optimization. These levers materially affect cost per part and can offset raw material inflation.
-
Capex sequencing and localization. Prioritize brownfield upgrades with modular lines over greenfield scale‑ups unless tied to significant contractual commitments. Localization of supply and technical service is an increasingly decisive factor for OEM customers seeking reduced logistics lead time and regulatory alignment.
-
M&A and alliance playbook. Use M&A to secure regional capacity, specialized formulations, or application know‑how. For buyers, joint ventures with local formulators provide a pragmatic route to market access in protected jurisdictions.
Competitive landscape: Who matters and why
The sector is anchored by a handful of global coating majors complemented by strong regional players. Market leaders bring integrated offerings (resins, curing agents, and technical services), which accelerates adoption across automotive and industrial segments. Key industry participants profiled in our report include:
-
PPG Industries, Inc. — A global leader with high‑performance cathodic epoxy e-coats (Powercron) that emphasize corrosion resistance and uniform film build. PPG’s advantaged application engineering and OEM relationships underpin its role in heavy‑duty and industrial accounts.
-
Axalta Coating Systems — Offers the AquaEC series, focused on mechanical robustness and corrosion protection for automotive OEMs. Axalta pairs product portfolios with strong OEM qualification pipelines.
-
BASF SE — With its CathoGuard family, BASF combines throw power and sustainability claims; recent investments in Europe and South Asia signal an aggressive capacity and market‑service push.
-
The Sherwin‑Williams Company — Supplies Vectrogard e-coats with emphasis on edge coverage and performance on heavy machinery; the company leverages broad distribution and application support.
-
Nippon Paint Holdings , Kansai Paint , and KCC Corporation — East Asian incumbents that combine local market scale with targeted technology offerings, particularly where low‑temperature cure and low‑voltage processing are competitive advantages.
-
Tatung Fine Chemicals — A regional manufacturer serving industrial and automotive sectors, representing the local supplier tier that many OEMs engage for niche requirements.
Recent corporate actions—price revisions by resin producers, plant commissioning and capacity expansions by major coating houses, and trade rulings—have immediate implications for market access, margin structures, and supplier selection strategies. The competitive map in 2026 will reward companies that combine application know‑how with resilient raw material strategies.
What our report delivers — practical tools for decision makers
PW Consulting’s full report is designed as an operational playbook for 2026. It includes:
-
Topline and bottom‑up market modeling (historical 2020–2025 and forecast 2026–2032) with scenario sensitivity to raw material price paths and trade policy shocks;
-
Decision frameworks for procurement, capex sequencing, and supplier selection—complete with model clauses and risk allocation templates;
-
Technical evaluation matrices that link formulation attributes to total cost of ownership across representative part types;
-
Competitive intelligence dossiers on major players and actionable benchmarks for qualification timelines, service SLAs, and integration costs;
-
A proprietary dealflow and M&A readiness checklist for companies contemplating consolidation or strategic partnerships in 2026.
We deliberately withhold granular regional and application split tables from this brief to preserve the commercial value of our proprietary segmentation; the full dataset and interactive tools are available through the report portal.
Methodological note and actionable next steps
Our analysis uses a blended approach: primary interviews with OEMs and formulators, trade and customs flow analysis, supplier capacity mapping, and a bottom‑up cost model calibrated to prevailing feedstock price trajectories. We supplement this with scenario testing that reflects upside and downside raw material movements and potential trade policy escalations.
For executives planning 2026 activities, recommended first steps are:
-
Conduct a 90‑day supplier‑risk triage focused on resin exposure and alternative sourcing options;
-
Prioritize two quick‑win operational changes (bath optimization, drag‑out recovery) to improve margin resilience;
-
Engage with technical vendors to pilot reformulated baths that reduce cure energy or increase solids;
-
Explore regional partnerships for markets affected by trade remedies to preserve customer continuity.
How to obtain the full analysis
This briefing is a strategic summary intended to inform board‑level and executive planning for 2026. For the full dataset, regional and application split tables, proprietary concentration metrics, and the interactive scenario toolset, please visit our report page or contact the PW Consulting market intelligence desk. The full report contains the granular models and contractual templates needed to convert the insights above into executable plans.
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com