

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Zero Gravity Bed Market Set to Soar at 11.85% CAGR During 2026–2032, Report Shows

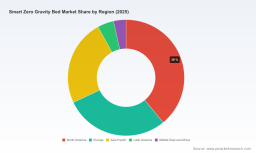
Worldwide Smart Zero Gravity Bed Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research, “Worldwide Smart Zero Gravity Bed Market (Base year: 2025; Forecast: 2026–2032),” delivers an executive-grade roadmap for companies, investors, and policy leaders planning moves in 2026. The market is on a sustained expansion trajectory driven by demographic tailwinds, clinical adoption, and smart-home convergence. This briefing summarizes the report’s strategic value: it shows where to focus investment, which commercial plays are likely to scale, and what regulatory and reimbursement inflection points will shape winners — while reserving the detailed segment tables and proprietary scoring models for the full report.
Worldwide Smart Zero Gravity Bed Market
Market at a Glance: Growth and Structure
Our forecast model shows the global market for smart zero gravity beds growing from a market size of USD 1,815.39 Million in the 2025 base year to an estimated USD 2,030.51 Million in 2026, with a compound annual growth rate (CAGR) of 11.85% across the 2026–2032 forecast window. By the end of the forecast horizon (2032), the market approaches a near-USD 4.0 billion opportunity. These macro dynamics reflect a compound effect of increasing consumer willingness to adopt premium sleep solutions, higher clinical adoption of positioning technologies in homecare and post-acute settings, and steady product innovation in adjustable bases, sensors, and software integration.
Worldwide Smart Zero Gravity Bed Market
Market concentration is meaningful but leaves scope for challenger entrants: the top three suppliers account for around 38% of industry revenue, and the top five capture just over half the market. That structure creates an environment where scale advantages matter, but differentiated product, channel partnerships, and certification for clinical use can create defensible niches.
Worldwide Smart Zero Gravity Bed Market
Why this Report Matters for 2026 Strategy
- Timing of investment and launches: With the market accelerating in 2026, product and channel investments made this year are positioned to capture an expanding addressable base. The report identifies which go-to-market models compress payback periods and which R&D bets are likely to translate into commercial traction.
- Clinical and reimbursement levers: Recent updates to durable medical equipment (DME) policy and the U.S. Medicare framework increase the likelihood that clinically justified adjustable beds remain reimbursable under existing codes when specific criteria are met. Our analysis translates these policy signals into market access requirements and commercial scenarios.
- M&A and partnership playbook: Fragmentation outside the top tier highlights acquisition opportunities across manufacturing, smart-base firmware, and telehealth-enabled service layers. The report includes an M&A prioritization matrix that aligns acquisition targets with integration complexity and near-term revenue uplift.
- Risk-adjusted commercialization: Regulatory, supply-chain and reimbursement contingencies materially affect project valuations. The report’s scenario toolkit enables CFOs and strategy leads to stress-test business cases under different policy and supply-risk conditions.
Actionable Insights for Key Stakeholders
- Product and R&D leaders: Prioritize modular platform architectures that permit clinical firmware variants and consumer feature packs. Investing in sensor integration and data analytics tied to pressure-relief outcomes will accelerate clinical adoption and create premium service revenue streams.
- Commercial and channel executives: Hybrid distribution — combining consumer retail partnerships for lifestyle variants and accredited clinical channels for reimbursable solutions — delivers better margin and mitigates single-channel concentration risk. The model in our report quantifies channel economics across multiple scenarios.
- Regulatory and reimbursement teams: Now is the moment to operationalize evidence-generation plans that align with DME medical necessity criteria (e.g., capacity to achieve therapeutic positioning). A targeted clinical-compliance roadmap in the report lays out minimum documentation, trial designs, and coding strategies.
- Operations and supply-chain leads: Identify dual-source suppliers for key electromechanical components and prioritize regional subassembly to lower tariff and logistics exposure. Our supply-chain heat maps identify sourcing bottlenecks and cost inflection points across the product lifecycle.
- Investors and corporate development: Evaluate targets using a blended scorecard of technological differentiation, clinical-readiness, distribution reach, and margin resilience. The report includes a proprietary valuation sensitivity matrix to support negotiation and post-merger integration planning.
Competitive Landscape: Who’s Moving and Why It Matters
The competitive map includes established adjustable-beds manufacturers, specialty medical-bed producers, and consumer-sleep brands that have extended into smart bases. Leading players vary in focus — from premium consumer ecosystems to clinically oriented hospital- and homecare products — and the competitive dynamics reflect differing go-to-market plays rather than a single dominant model.
- SonderCare (London, Ontario): Focused on premium home-hospital beds with therapeutic positioning and a product set that targets long-term care and recovery. Their strengths lie in clinical positioning options and home-health integrations.
- Ergomotion (Santa Barbara): A global leader in adjustable bases for smart beds, known for high-volume manufacturing and strong retail partnerships. Recent milestone activity underscores ongoing investment in design and showroom experience, reinforcing brand leadership in adjustable-base technology.
- Leggett & Platt (Adjustable Beds Division, USA): A major U.S. manufacturer whose scale and retail relationships make it a go-to supplier for both consumer and medical channels. Its product breadth and manufacturing scale are competitive advantages.
- Tempur-Pedic (USA): Positions smart bases as part of premium sleep systems with differentiated software integrations such as AI-driven sleep tracking, creating a strong bundle value proposition for consumers.
- Hebei Chibang (China) and Zero-G Beds (India): Represent regional manufacturing and homecare-focused producers supplying hospital and homecare markets with medically featured adjustable beds and zero-gravity modes; they are important players in lower-cost supply and growing domestic demand.
Our competitive assessment blends product feature mapping, channel reach, and clinical certification status to produce a short-list of realistic challengers for each strategic play (premium consumer, clinical/homecare, or OEM supply). For readers who require the vendor-by-vendor scorecards and readiness indices, the full report includes downloadable matrices and vendor dossiers.
Regulatory and Reimbursement Dynamics — Practical Implications
Two public-policy realities have immediate strategic implications: 1) Medicare Part B continues to provide coverage for hospital beds deemed medically necessary when criteria are met; and 2) documentation and practitioner examination requirements are non-negotiable components of successful reimbursement. These points are not abstract — they determine whether a path-to-market is commercially feasible for products positioned as medically necessary versus consumer-wellness devices.
Equally important, evolving guidance around telehealth and remote patient monitoring creates new opportunities to pair beds with remote care services. The report provides a compliance checklist and recommended evidence-generation strategies that align product design with prevailing HCPCS coding practices and clinical acceptance thresholds.
Report Contents: Practical, Executable, Confidential
PW Consulting’s report is designed to be immediately actionable. Key deliverables include:
- Market sizing and seven-year forecast model (2026–2032) with scenario and sensitivity views;
- Go-to-market playbooks for consumer, clinical, and hybrid channels, including pricing and margin templates;
- Regulatory and reimbursement mapping with compliance checklists tailored to major markets;
- Competitive intelligence dossiers and a vendor readiness index for acquisition and partnership screening;
- Supply-chain risk maps and near-term mitigation pathways for sourcing and cost management;
- Commercialization KPI dashboards and a 100-day market-entry checklist for product launches;
- Investor-facing valuation and M&A playbooks with integration risk scoring.
To preserve commercial value across stakeholders, this public briefing highlights the themes and strategic choices while the full report delivers the granular tables, proprietary scoring algorithms, and downloadable models that executives and investors rely on.
Navigating the Near-Term Risks and Opportunities
- Opportunity — Premiumization meets clinical need: Pressure-relief and circulatory benefits associated with zero gravity positioning create a clear clinical value proposition for elderly and postoperative populations. Converting clinical outcomes into reimbursement-ready evidence is the fastest route to scaled revenue.
- Risk — Policy and documentation friction: Reimbursement is not automatic. The need for practitioner validation and documented medical necessity introduces sales friction that demands dedicated clinical affairs capabilities and training in provider engagement.
- Opportunity — Smart services monetization: Subscription services tied to analytics, mattress lifecycle management, and remote caregiver dashboards are high-margin adjacencies that increase customer lifetime value.
- Risk — Supply and component concentration: Electromechanical actuators and control modules are concentrated in a limited supplier pool. Mitigation requires dual-sourcing and local assembly strategy.
How to Use This Intelligence in 2026
If you are a C-suite leader, board member, or investor planning 2026 resource allocation, this report functions as both a market map and decision-support system. Use the findings to:
- Prioritize R&D investments that align with reimbursement windows and clinical evidence timelines;
- Design pilot partnerships with clinical networks to accelerate coverage and referral flows;
- Evaluate M&A targets using the report’s integration risk and revenue accretion models;
- Implement a phased go-to-market plan that balances retail exposure with accredited clinical channels.
For executives who need the full dataset (including the proprietary segment models, vendor scorecards, and downloadable financial templates), PW Consulting’s full report provides the detailed evidence base that underpins the strategic recommendations summarized here. Reach out to our team to schedule a confidential briefing and receive the complete analytics package tailored to your business priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com