

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Embedded System Market Poised to Reach USD 201.15 Billion by 2032, Growing at a 6.85% CAGR

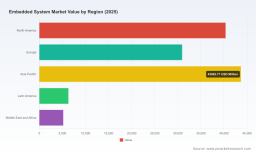
Worldwide Embedded System Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting’s new Worldwide Embedded System Market report—anchored on a 2025 base year and projecting through 2032—translates the sector’s macro trajectory into concrete choices for executives preparing budgets, roadmaps, and M&A plans in 2026. Our analysis shows the global embedded systems market reached roughly USD 126.5 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.85% across the 2026–2032 horizon, reaching approximately USD 201.1 billion by 2032. This press release outlines the report’s strategic value and highlights the operational insights leaders will need to convert growth expectations into competitive advantage—while preserving the detailed segment-level datasets and granular vendor scoring exclusively for report subscribers.
Worldwide Embedded System Market
Why this report matters for 2026 decision cycles
-
Timing budgets and capital allocation. With multi-year procurement cycles in semiconductors and embedded platforms, 2026 is a pivotal year to re-sequence CapEx and R&D investments in systems that must meet evolving performance, safety, and cybersecurity requirements.
Worldwide Embedded System Market -
Risk-adjusting supply chain choices. The report identifies supply-side stress points and provides hedging strategies that are implementable during vendor selection and contract negotiation.
Worldwide Embedded System Market -
Complying without sacrificing velocity. New regulation and standards will change compliance checklists and timelines; the report maps practical compliance pathways that preserve product time-to-market.
-
Targeting M&A and partnerships. We score business models and technical roadmaps to identify the most accretive targets for companies seeking inorganic growth or capability augmentation.
Macro picture: what’s driving the 6.85% CAGR
The forecasted mid-single-digit CAGR reflects a balance of sustained demand for embedded compute across automotive, industrial automation, healthcare devices, telecommunications, and consumer systems, alongside episodic volatility from component supply and policy-driven integration requirements. Two structural forces are particularly influential:
-
Functionality densification at the edge — led by edge AI inference, more complex sensor stacks, and mixed-criticality compute — which raises average system bill-of-materials and drives replacement cycles;
-
Regulatory and safety floor-raising, which increases non-recurring engineering and certification costs yet creates differentiation opportunities for compliant-platform providers.
Headwinds are tangible: memory and RAM constraints (notably for low-power LPDDR classes) are elevating component costs and driving design trade-offs, while talent scarcity in embedded software pushes teams toward higher automation, model-based design, and AI-assisted development tools.
What’s inside the report — practical, operational deliverables
-
Transparent market sizing and methodology: a reconciled historical series (2020–2025) and forward scenarios (2026–2032) with sensitivity to component price shocks and regulatory adoption schedules.
-
Commercial playbooks for vendors and OEMs: go-to-market options for platform-based versus product-led strategies, and commercial terms to negotiate with tier-1 suppliers.
-
Procurement and supply-chain toolkit: supplier scorecards, dual-sourcing blueprints, inventory hedging templates, and lead-time stress tests.
-
Regulatory impact maps: compliance timelines and practical steps to embed SBOM, vulnerability handling, and secure development lifecycle practices into product roadmaps.
-
Vendor profiles and vendor-fit matrices: qualitative and quantitative assessments of technology stack, longevity commitments, ecosystem support, and route-to-certification risk.
-
M&A and partnership shortlists: accretive target archetypes by capability (edge AI, safety-certified stacks, connectivity gateways) and integration risk checklists.
-
Scenario-driven financial models: revenue, margin, and cashflow permutations for platform investment choices under varying component-price and regulatory-cost outcomes.
Competitive dynamics — what to watch among core vendors
The embedded systems landscape remains relatively fragmented, with large, diversified semiconductor and platform suppliers coexisting alongside focused specialists. This structure yields an open field for both consolidation and vertical integration plays. Key vendor takeaways from our benchmarking:
-
Intel: continues to leverage long-life availability and platform breadth—positioning for industrial and automotive compute with roadmap emphasis on edge AI acceleration and lifecycle services.
-
Texas Instruments: deep in analog, power, and low-power MCUs, TI remains a go-to for OEMs optimizing for energy efficiency and reliability in industrial and consumer designs.
-
NXP: strongest where secure controllers and connectivity meet automotive and industrial IoT requirements; security and vehicle-network integration are clear differentiators.
-
STMicroelectronics: the STM32 ecosystem and sensor integration underpin broad uptake in embedded control and sensor-fusion applications; ecosystem support reduces time-to-deploy for customers.
-
Renesas: competitive in automotive-grade MCUs and mixed-signal SoCs, with strategic emphasis on safety-certifiable platforms and long-term supply commitments.
-
Qualcomm: shifting more resources to edge AI and wireless-enabled embedded platforms for IoT and mobility use cases.
-
Infineon: power-semiconductor leadership and secure microcontroller offerings make it central to safety-critical and high-reliability applications.
-
Microchip, Analog Devices, Samsung, Broadcom, NVIDIA, AMD: each plays a clear role—ranging from control and analog specialization to high-performance GPU-accelerated edge platforms—creating an ecosystem where strategic partnering often beats single-vendor reliance.
Regulation, standards, and supply-side constraints: immediate triggers for 2026
Several near-term developments will materially affect product roadmaps and procurement strategies in 2026:
-
Cybersecurity regulation: the EU Cyber Resilience Act—now in its transition window—requires embedded hardware and software placed in applicable markets to adopt secure development practices, vulnerability handling pipelines, and SBOM generation. Organizations must budget for compliance activities and align release cadences with regulatory timelines.
-
Standards update: the refreshed ISO/IEC/IEEE 12207:2026 codifies modern lifecycle practices. Teams that align early will reduce audit friction and accelerate supplier qualification.
-
Memory supply pressure: AI-driven reallocation of memory manufacturing capacity has driven up prices and constrained availability for LPDDR families commonly used in embedded designs. Design-to-cost and memory-footprint optimization become critical tactical levers.
-
Safety standards remain non-negotiable: ISO 26262 and IEC 61508 will continue to raise certification costs—favoring providers that offer safety-certified reference platforms.
-
Talent scarcity: embedded software engineering talent remains tight; successful organizations are accelerating adoption of AI-assisted coding, model-based systems engineering, and higher-level abstraction frameworks to amplify scarce engineering resources.
Six strategic imperatives for 2026
-
Design for regulated markets: embed SBOM and secure-by-design practices into product foundations now—retrofits are costly and slow.
-
Hedge memory exposure: negotiate supply agreements, qualify alternative parts, and invest in software techniques to reduce memory dependence.
-
Platformize where value accumulates: prioritize platform plays (hardware + validated software stacks) in applications where certification and longevity drive customer lock-in.
-
Dual-source critical components: split strategic suppliers across geographic and process nodes to limit single-point-of-failure exposure.
-
Invest in verification and safety-as-a-service: build or partner for safety certification capabilities to shorten customer qualification cycles and justify premium pricing.
-
Adopt AI-assisted engineering: accelerate embedded firmware and validation throughput with tools that augment rather than replace expert engineers.
How executives should use the report in 2026 planning
CEOs and boards should use the report to stress-test topline scenarios and calibrate inorganic strategies against supply and regulatory variability. CTOs and heads of product will find prioritized technology roadmaps and vendor-fit matrices useful for setting 18–36 month architecture commitments. CFOs and procurement leads can use the financial scenarios and procurement toolkits to insulate margins from volatile component markets. Heads of M&A will benefit from the curated target archetypes and integration-risk assessments when sizing bolt-on acquisitions.
To preserve actionable intellectual property and modeling fidelity, the report with full segment breakdowns, interactive dashboards, detailed company scorecards, and downloadable financial models is available on the PW Consulting research portal. The executive summary and methodological appendix in the full report will enable you to adapt models to internal assumptions and run bespoke sensitivity tests with your own cost, price, and timeline inputs.
Closing: a practical roadmap for converting growth into advantage
The embedded systems market’s steady expansion through 2032 creates both opportunity and complexity. For 2026 in particular, the intersection of regulatory acceleration, memory supply pressure, and rising system complexity means that choices made this year will determine competitive positioning for the next contract cycle. PW Consulting’s Worldwide Embedded System Market report is designed to move you from strategic intent to operational execution—offering the templates, risk maps, and vendor intelligence needed to make 2026 investment decisions with confidence.
To access the full dataset, vendor scorecards, and implementation playbooks, contact PW Consulting or visit our research page for subscription options and enterprise licensing.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com