

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Elapegademase-lvlr Market Poised to Expand at an 8.5% CAGR During 2026–2032

Worldwide Elapegademase-lvlr Drugs Market: Strategic Imperatives for 2026
As PW Consulting publishes its latest in-depth study on the Worldwide Elapegademase-lvlr Drugs Market, this briefing distills the report’s strategic value for executives making high-stakes decisions in 2026. The analysis combines a rigorous, data-driven foundation with an operational playbook built for immediate implementation—while deliberately reserving proprietary segmentation granularity for the full report. Below we outline the high-level market trajectory, competitive dynamics, regulatory and supply considerations, and the actionable scenarios leaders should use to stress-test their 2026 plans.
Worldwide Elapegademase-lvlr Drugs Market
Market snapshot: size, trajectory, and concentration
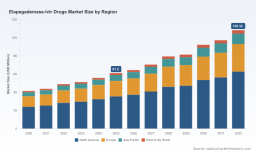
Our model, calibrated across the historical window 2020–2025 with base year 2025 and a forecast horizon extending through 2032, shows the global Elapegademase-lvlr market expanding at a compound annual growth rate (CAGR) of 8.5% during the 2026–2032 forecast period. On an absolute basis, the market has grown materially from the early 2020s and reached USD 61.2 Million (USD Million, base year 2025). Our baseline projection anticipates continued expansion through the forecast period, approaching the low triple‑digit mark in USD Million by 2032 under the central case.
Worldwide Elapegademase-lvlr Drugs Market
Concentration metrics underscore the market’s structural characteristics: the dominant incumbency of the marketed therapy results in an exceptionally high top-tier concentration. This degree of concentration materially shapes commercial strategy, negotiation dynamics with payers and providers, and the returns profile for new entrants.
Worldwide Elapegademase-lvlr Drugs Market
Why this report matters for 2026 decision-making
- Resource allocation with clarity: The market’s steady CAGR and trajectory offer finance and portfolio teams a defensible baseline for capital planning, manufacturing investments, and global launch sequencing.
- Supply chain and manufacturing prioritization: Historical shortage events combined with rising demand create a persistent premium on supply security; our report provides a targeted risk matrix and mitigation paths that should be operationalized in 2026.
- Payer and access strategy optimization: Given existing orphan reimbursement pathways in major markets, 2026 will be a tactical year to shape contracting frameworks and patient access programs that lock in utilization ahead of competitive inflection points.
- Regulatory and lifecycle timing: Exclusivity timelines and label constraints require synchronized clinical, regulatory, and commercial activities—our timeline synthesis equips teams to prioritize filings and investments with precision.
What the report contains: an operational playbook (high level)
The full study is designed as a transactional tool for senior leadership, combining the following practical components:
- Transparent market-sizing model (historical and forecasted in USD Million) with driver-level decomposition and sensitivity toggles for demand, price dynamics, and access scenarios;
- Scenario-based forecasts (base, upside, downside) aligned to supply disruptions, regulatory shifts, and competitive entry timing;
- Commercial playbooks including pricing levers, payer segmentation strategies, contracting templates, and channel optimization guidance;
- Supply chain risk assessment with prioritized mitigation actions (contract manufacturing options, dual-sourcing thresholds, safety stock policies, and regulatory-compliant tech transfers);
- Regulatory and reimbursement timeline matrix with jurisdiction-specific milestones and suggested filing sequences;
- Competitive playbook covering incumbent defense tactics, potential biosimilar/alternative entrant responses, and M&A/licensing decision frameworks;
- Patient access and real-world evidence (RWE) strategies designed to accelerate uptake and reinforce value dossiers for payers.
Competitive dynamics: incumbent position and implications
The market’s principal marketed therapy is distributed by a single, identifiable incumbent. The company’s global commercialization of the PEGylated recombinant human adenosine deaminase product has established a de facto standard of care across the indicated population. Recent operational notes—from documented manufacturing delays and an associated shortage to subsequent resupply actions—illustrate how supply-side events can quickly influence utilization patterns and payer behavior.
Key commercial and strategic implications:
- High market concentration decreases near-term pricing pressure but raises the strategic importance of supply reliability; a single supply disruption can materially alter demand realization and create windows of opportunity for competitors.
- Exclusivity windows and orphan drug protections create predictable planning horizons; the end of key exclusivity dates will be a focal point for 2026 planning, prompting preemptive lifecycle and defense strategies.
- Payer coverage pathways that favor orphan-designated therapies can facilitate rapid uptake, but they also set expectations for evidence generation and outcomes tracking—requirements that must be met to secure durable access.
Regulatory, reimbursement, and clinical constraints shaping market access
Several non-negotiable dynamics inform any go-to-market calculus for 2026:
- Orphan-exclusivity mechanics have historically offered meaningful protection that affects entry timing and commercial returns; parties should align launches, filings, and competitive intelligence to these timelines.
- Supply disruptions that have occurred since late 2022 highlight the operational fragility of the category; contingency manufacturing and inventory strategies are now central to commercial viability.
- Reimbursement pathways in large markets provide a route to coverage, but payer expectations for cost-effectiveness and RWE are evolving—companies must prepare more rigorous health economic arguments and patient support frameworks.
- Product constraints such as contraindications tied to excipients (for example, hypersensitivity to PEG) will continue to influence patient segmentation, necessitating parallel clinical and commercial pathways for alternative patient cohorts.
Scenario planning for 2026: three actionable cases
Leaders must stress-test plans against plausible futures. We offer three scenario archetypes that anchor strategic choices in the report:
- Base case (central): Demand continues along the modeled CAGR of 8.5% as the incumbent maintains market leadership, and supply normalizes. Actions: secure long-term supply agreements, deploy phased geographic expansion, and prioritize payer dossier updates.
- Supply-disruption downside: Recurrent manufacturing bottlenecks constrain access in the near term. Actions: accelerate alternative manufacturing partnerships, implement prioritized allocation frameworks, and expand patient-assistance programs to preserve adherence.
- Post-exclusivity competitive pressure: Earlier-than-expected entrants or regulatory shifts compress pricing and share. Actions: invest in label-advancing studies, prepare value-based contracting pilots, and consider defensive licensing or M&A to shore up position.
Six strategic moves for 2026
- Lock in supply resiliency: Establish multi-sourced manufacturing capacity and clinical‑grade fill/finish contingencies to eliminate single points of failure.
- Operationalize payer strategies: Use targeted value dossiers, outcome-based contracting pilots, and early HTA engagement to accelerate coverage and reduce time-to-therapy.
- Prioritize evidence generation: Fund pragmatic trials and RWE collection to address real-world effectiveness and safety, including monitoring for excipient-related hypersensitivity risks.
- Design patient-centric access: Build integrated hub services, copay assistance, and adherence support to maximize persistence and real-world outcomes.
- Prepare defensive lifecycle plays: Map exclusivity cliffs and prepare label-extension studies, manufacturing scale-up, or strategic partnerships to sustain margins if competitive entrants emerge.
- Evaluate strategic transactions: Use disciplined M&A and licensing to acquire complementary assets, secure supply, or fast-track entry into prioritized geographies—driven by rigorous scenario valuation work.
What executives should do next
For senior teams entering 2026, the path forward is clear: translate the macro trajectory and concentration realities into operational commitments now. That means allocating capital to supply certainty, accelerating evidence programs that satisfy payers, and designing flexible commercial models that can adapt to both supply shocks and competitive incursions.
PW Consulting’s full report delivers the empirical underpinnings and executable modules that make these moves operational—market models in USD Million, scenario sensitivities, playbooks, and a confidential segmentation analysis that assigns commercial priority by geography, channel, and patient cohort. Those proprietary segmentation insights and granular revenue impact scenarios are intentionally reserved for the full report to preserve their strategic value.
Learn more
To access the complete Worldwide Elapegademase-lvlr Drugs Market report—including the detailed segmentation, model files, and customized scenario outputs—visit our report page. The full package provides the granular intelligence necessary to finalize budgets, structure regulatory and commercial timelines, and set measurable 2026 KPIs with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Elapegademase-lvlr Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com