

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 13.01% CAGR for Worldwide Automotive Image Signal Processor Market in 2026–2032

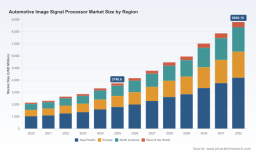
Worldwide Automotive Image Signal Processor Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
As automotive vision moves from convenience to core vehicle safety and autonomy, Image Signal Processors (ISPs) are transitioning from component‑level enablers to strategic assets. PW Consulting’s latest research—anchored on a 2025 base year and a 2026–2032 forecast horizon—finds the global automotive ISP market on a sustained expansion path, reflecting accelerated ADAS deployment, richer in‑cabin sensing, and the rise of zonal/AI architectures. The market more than doubled in scale through the first half of the decade and is projected to continue growing at a double‑digit compound annual rate across the forecast period. For executives planning capital allocation, supply contracts, product roadmaps or M&A in 2026, this is a pivotal intelligence moment: structural growth is clear, but strategic choices about supplier architecture, safety compliance, and supply‑chain resilience will determine winners and losers.
Worldwide Automotive Image Signal Processor Market
Macro trajectory: what the headline numbers mean for corporate strategy
Between 2020 and 2025 the market expanded significantly, driven by rapid adoption of surround‑view systems, ADAS camera suites, and the first waves of in‑cab monitoring. The market’s momentum carries into the forecast window (2026–2032), where our model projects sustained double‑digit growth. This macro trajectory signals three practical implications for 2026 planning horizons:
Worldwide Automotive Image Signal Processor Market
- Demand certainty for ISPs is shifting capital allocation from speculative R&D to scale investments—both among established semiconductor vendors and systems integrators.
- Vehicle OEMs and Tier‑1s must choose between vertically integrating ISP capabilities (via SoC partnerships or in‑house IP) or locking in multi‑sourced, certified suppliers to manage risk across models and regions.
- Procurement strategies need to transition from single‑year spot buys to multi‑year supply and licensing agreements that reflect the multi‑phase evolution of camera stacks (from basic exposure/HDR to AI‑augmented pipelines).
Technology and product dynamics shaping 2026 decisions
Three technical vectors are converging to increase ISP strategic importance:
Worldwide Automotive Image Signal Processor Market
- Higher sensor performance and interface evolution: Newer automotive CMOS sensors with wider dynamic ranges and high pixel throughput (and physical interfaces such as automotive‑grade A‑PHY) are raising the bar for ISP pipelines. Customers evaluating camera subsystems in 2026 should prioritize interoperability with next‑generation sensor interfaces.
- AI and functional safety embedding: ISPs are no longer only about image tuning. Integration of NPUs, pre‑processing for perception stacks, and certifications linked to functional safety regimes are becoming gating factors for selection in safety‑critical ADAS domains.
- Architecture choices—integrated vs. standalone: OEMs face a fundamental tradeoff: integrated SoC approaches reduce BOM complexity and power consumption but can lock customers into broader software ecosystems; standalone ISPs offer modularity and faster time‑to‑market for differentiated camera features.
Competitive landscape: how suppliers are positioning for 2026
The ISP supplier landscape is populated by diversified semiconductor majors, camera sensor leaders, dedicated ISP specialists, and IP providers. Each group brings differentiated value propositions that matter for procurement and partnership strategy:
- Sensor‑first players (example: Sony Semiconductor Solutions): Lead with high‑end CMOS imagers; recent product introductions with built‑in automotive interfaces underscore the strategic coupling of sensor and ISP roadmaps. For OEMs, partnering with sensor‑first suppliers can accelerate high‑dynamic‑range camera performance.
- Integrated SoC vendors (examples include NXP, Qualcomm, Ambarella): Deliver end‑to‑end compute platforms with ISPs embedded. These vendors appeal to OEMs prioritizing consolidated software stacks, latency optimization, and consolidated supplier management.
- Discrete ISP and IP specialists (examples include onsemi, OmniVision, VeriSilicon, Nextchip, and Renesas): Offer optimized ISP pipelines, functional‑safety IP, and flexible licensing models. Recent industry certifications and IP upgrades demonstrate their focus on ASIL support and high‑throughput pipelines required by ADAS.
- Analog and mixed‑signal incumbents (examples include Texas Instruments, STMicroelectronics): Complement ISP capabilities with robust analog front‑end and power management, enabling system‑level optimization for automotive form‑factors.
Recent product and certification developments crystallize competitive positioning: sensor makers shipping A‑PHY‑enabled parts and IP vendors achieving ISO 26262 certifications are effectively hardening their value proposition for safety‑critical applications. Firms upgrading HDR/IR pipelines and integrating NPUs are competing on feature‑velocity and software enablement.
Supply‑chain, regulation and operational risks that will influence 2026 outcomes
Three non‑technology risks loom large for 2026 program decisions:
- Trade and tariff dynamics: Recent government actions on advanced computing chips and investigations into processed critical minerals introduce near‑term cost and sourcing uncertainty. Buyers must model tariff scenarios into TCO analyses and consider alternative sourcing or regional manufacturing strategies.
- Lead‑time volatility: Automotive semiconductor lead times lengthened recently amid heightened ADAS demand, implying program buffer requirements and tighter coordination between procurement, forecasting, and product engineering teams.
- Regulatory and safety certification needs: Functional safety certification is rapidly becoming table stakes in ISP selection for production‑grade ADAS. Suppliers that can demonstrate robust ISO 26262 pathways will be advantaged in safety‑sensitive tenders.
What PW Consulting’s report delivers (practical, actionable content)
Where many market briefs stop at high‑level forecasts, this report is built to be operationally useful for 2026 decision cycles. Highlights include:
- Forward‑looking demand model calibrated to vehicle production, trim adoption curves, and camera content per vehicle—useful for component procurement planning and capital budgeting.
- Technology adoption curves for HDR, RGB‑IR, embedded NPUs, and A‑PHY‑class interfaces to guide R&D and supplier alignment decisions.
- Vendor scorecards and procurement playbooks: head‑to‑head supplier assessments across software maturity, functional‑safety readiness, roadmap alignment, and commercial flexibility.
- Scenario analyses quantifying the P&L and working‑capital impact of tariff, lead‑time and certification outcomes under conservative, base and accelerated ADAS adoption trajectories.
- Contracting templates and negotiation tactics tailored for ISPs—covering IP licensing, long‑lead components, and warranty allocations for safety‑critical functions.
- M&A and partnership screen: shortlists of target profiles (IP houses, camera SoC specialists, sensor integrators) and valuation sensitivities under multiple market growth scenarios.
Practical recommendations for 2026 planning cycles
For corporate leaders who must translate market growth into concrete actions this year, our research points to a compact set of priorities:
- Adopt dual‑track sourcing for ISPs: Combine at least one integrated SoC partner with a specialized ISP supplier to preserve architectural optionality while securing performance differentiators.
- Prioritize suppliers with clear ISO 26262 roadmaps: Certification timelines should be gating factors in supplier selection for any safety‑critical program entering design freeze in 2026.
- Model tariff and mineral‑sourcing scenarios into supplier TCO: Stress test supplier quotes for tariff‑driven cost uplift and incorporate contingency sourcing clauses in new agreements.
- Invest in software and calibration capabilities: Differentiation increasingly shifts to ISP tuning, AI pre‑processing and camera validation—capabilities that shorten time‑to‑market and reduce field recalls.
- Plan for multi‑year commitments on long‑lead items: Lead‑time drift requires earlier procurement decisions; synchronous planning between electronics, mechanical and software teams is now essential.
- Use the report’s scenario outputs to calibrate M&A and R&D spend: Identify targets with proven safety IP or durable customer relationships rather than purely revenue‑growth targets.
Why this is a “must‑read” for 2026 decision windows
Growth in the automotive ISP market is not merely quantitative—its strategic importance has evolved. ISPs now sit at the intersection of sensing hardware, perception software and safety compliance. For 2026, that means the right ISP decisions will materially affect vehicle architecture, supplier ecosystems, and capital intensity for the remainder of the decade. PW Consulting’s report is structured to reduce execution risk: it links market sizing to procurement playbooks, supplier scorecards, and regulatory scenario planning so that leadership teams can move from insight to implementation within a single planning cycle.
Next steps
Executives planning 2026 product launches, procurement rounds, or M&A activity should treat this report as input to board‑level scenario planning sessions and supplier negotiation checklists. The public summary provided here outlines strategic themes and the macro growth trajectory; the full report contains the granular forecast models, vendor benchmarking matrices, scenario P&Ls, and contracting templates you will need to act with precision.
To access the complete analysis, detailed vendor profiles, and downloadable forecast models, please visit our report landing page for the Worldwide Automotive Image Signal Processor Market. PW Consulting’s advisory team is available for custom deep‑dives to translate the findings into procurement strategies, product roadmaps, or M&A diligence tailored to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com