

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Robust 8.5% CAGR for Worldwide Shape Memory Alloys in Civil Engineering Through 2032

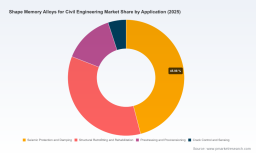
Worldwide Shape Memory Alloys for Civil Engineering Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting today publishes a strategic preview of our forthcoming market research on the Worldwide Shape Memory Alloys (SMA) for Civil Engineering market. This advisory briefing synthesizes why 2026 is a pivotal year for infrastructure owners, system integrators, materials suppliers and private‑equity investors evaluating entry, expansion or partnership strategies in SMAs for structural applications.
Worldwide Shape Memory Alloys for Civil Engineering Market
Why this market matters in 2026
The global SMA for civil engineering market has moved beyond niche laboratory demonstrations into repeatable field deployments. After a steady expansion through the 2020–2025 historical window, the overall market is projected to accelerate through the 2026–2032 forecast horizon at an 8.5% compound annual growth rate (CAGR). In monetary terms, the market expanded from the low hundreds of million USD in 2020 to approximately USD 245.5 million in the 2025 base year and is forecast to approach the mid‑hundreds of million USD by 2032 under the baseline scenario.
Worldwide Shape Memory Alloys for Civil Engineering Market
For business leaders preparing 2026 capital and product roadmaps, this trajectory signals a transition phase: from proofs‑of‑concept and pilot retrofits to selective mainstreaming across seismic protection, structural retrofitting, prestressing and sensing/damage‑detection applications. The strategic question is not whether SMA technologies will matter — they will — but how and where to position along the value chain to capture outsized return while managing technical, supply‑chain and regulatory risks.
Worldwide Shape Memory Alloys for Civil Engineering Market
What the PW Consulting report delivers (practical, operational content)
- Actionable market sizing and growth scenarios (base year 2025; forecast 2026–2032) with sensitivity analysis for material price shocks and accelerated standards adoption.
- Methodology transparency: data sources, primary interview networks, project‑level validation and triangulation against deployment case studies from 2020–2025.
- Segment coverage: regional, material (NiTi, iron‑based, copper‑based and variants) and application-level views — note: detailed segment splits and granular revenue tables are reserved for the full report.
- Supply‑chain and manufacturing analysis, including feedstock sourcing, vertical integration profiles and capacity constraints for key alloy types.
- Regulatory and standards mapping with ASTM references relevant to civil engineering adoption and procurement specifications.
- Competitive benchmark and vendor scorecards with capability matrices and go‑to‑market positioning.
- Procurement and pilot playbooks for public agencies and EPCs: specification templates, risk allocation, installation checklists and lifecycle cost models.
- Investment and M&A framework: valuation drivers, consolidation scenarios and criteria for strategic partnerships.
Key strategic takeaways for 2026 decision‑makers
- Prioritize pilots that de‑risk installation and inspection protocols. The fastest routes to scale are repeatable, low‑risk implementations that deliver measurable outcomes (reduced downtime, simplified execution, or demonstrable lifecycle savings).
- Adopt a materials‑agnostic evaluation early: NiTi (Nitinol) delivers unmatched superelastic performance; Fe‑based SMAs offer cost and scalability advantages for large structural elements. Each class carries different supply‑chain and qualification timelines.
- Manage raw‑material exposure proactively. Nickel and titanium price volatility materially affect NiTi cost curves; hedging, strategic vendor relationships and alternative alloys can moderate procurement risk.
- Leverage standards readiness as a competitive lever. Compliance with ASTM test methods and standards reduces buyer friction — procurement teams should require documented conformance and test evidence during supplier selection.
- Match supplier capability to use‑case complexity. Pure materials suppliers can serve commoditized needs; integrators with systems capability (sensing, actuation, installation services) outperform when projects require turnkey delivery.
- Factor market concentration into partnership strategy. The market is moderately fragmented: the top three firms account for roughly one‑third of commercial activity, and the top five for under half. There remains room for new entrants with specialized system offerings or cost advantages.
Competitive landscape — who to watch and why
Our vendor analysis highlights distinct business models that buyers and investors must evaluate not simply on price but on demonstrable field performance, systems capability and supply security.
- re‑fer AG (Brunnen, Switzerland) — https://www.re-fer.eu
A focused player in iron‑based memory®‑steel for concrete and masonry strengthening. Their patented approach and documented deployments (dozens of real‑world applications) make them a go‑to for structural retrofitting and digital fabrication experiments. Strengths: targeted domain expertise, proven field track record in repair/retrofit. - Ingpuls GmbH (Bochum, Germany) — https://ingpuls.de
Offers customizable SMAs and integrated solutions across building technology use cases (actuators, dampers, crack detection). Ingpuls excels where materials meet mechatronic integration and full‑value‑chain delivery — attractive for owners seeking single‑vendor responsibility. - SMA CORES Inc. (Champaign, Illinois, USA) — https://sma-cores.com
Focused on SMA structural technologies using thermal prestressing and superelasticity to accelerate construction and reduce labor intensity. Their solutions are positioned to shorten schedules on rehabilitation projects where thermal activation is feasible. - SAES Getters S.p.A. (Lainate, Italy) — https://www.saesgetters.com
A vertically integrated manufacturer of NiTi alloys — from melting through component production. Vertical integration offers supply security and process control advantages for high‑performance NiTi components. - Dynalloy Inc. (Irvine, California, USA) — https://dynalloy.com
Known for Flexinol® NiTi actuator wires; well‑placed where compact actuation and retrofit actuation are required. Their materials are often embedded into subsystem suppliers' actuator solutions. - Memry Corporation (Bethel, Connecticut, USA) — (corporate profile)
Supplies Nitinol in multiple forms (wire, tubing, components), supporting engineering use cases that require standardized feedstock and custom component fabrication.
What these profiles collectively signal: differentiated players either focus on materials production, system integration, or hybrid offerings. Buyers should evaluate beyond catalog items — preference should be given to suppliers who can demonstrate code‑level documentation, field deployments, and scalable manufacturing pathways.
Recent developments shaping the 2026 agenda
- February 2026 — Swiss researchers in collaboration with Empa demonstrated a heat‑activated iron‑based SMA strengthening method for ageing bridge decks, underscoring Fe‑SMA real‑world applicability to structural overlays.
- January 2026 — re‑fer AG reported use of memory®‑steel in a digitally fabricated concrete staircase, demonstrating cross‑disciplinary adoption in research and advanced construction methods.
- September 2026 — TRANS‑IPIC will host the 1st International Symposium on Shape Memory Alloys in Infrastructure, creating a focal point for knowledge exchange and potential acceleration of standards and procurement frameworks.
Market dynamics and risk factors you must model
- Raw material exposure: nickel and titanium price volatility from mine supply constraints and geopolitical factors can shift NiTi cost competitiveness rapidly; Fe‑SMA presents an alternative exposure profile.
- Standards and qualification: ASTM references (including standards and test methods for SMAs and actuators) are becoming table stakes for public procurement. Projects lacking standardized test evidence face longer approval cycles.
- Manufacturing scale: Fe‑SMA advantages in producing larger components using conventional metallurgical equipment can compress unit costs for heavy structural elements, while NiTi remains preferred for high‑performance actuation and sensing.
- Procurement conservatism: public agencies often require multi‑year validation and third‑party verification for new materials in safety‑critical infrastructure — anticipate elongated sales cycles and plan pilots accordingly.
Readiness checklist for procurement, engineering and corporate strategy teams (2026)
- Shortlist suppliers by proof points: installed projects, third‑party test reports and references.
- Run a two‑track pilot program: a lightweight sensor/actuation pilot for quick wins and one structural retrofit for lifecycle economics demonstration.
- Include raw‑material clauses and indexation in long‑term supply contracts; assess alternative alloy pathways (Fe‑SMA) as a hedge.
- Require ASTM‑compliant test evidence as part of pre‑qualification packages.
- Map potential partners across the value chain: alloy makers, component fabricators, system integrators and inspection service providers.
- Model consolidation scenarios: given the market’s current concentration metrics, consider strategic minority investments or JV structures to secure preferred access to capacity.
Next steps — where the full intelligence is
This briefing is a strategic trailer: it highlights the most material trends, risk vectors and competitive dynamics that should inform 2026 decision‑making. PW Consulting’s full Worldwide Shape Memory Alloys for Civil Engineering market report contains the detailed regional and application segmentation, granular vendor scorecards, country‑level forecasts and downloadable procurement templates required to execute pilots and commercial rollouts. For procurement teams, engineering leads and investors planning entry or scale strategies in 2026, the full report provides the operational playbooks and data tables necessary to move from strategy to contract.
To access the comprehensive dataset, supplier benchmarks and practical templates, please visit the PW Consulting report page or contact our industry practice leads for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com