

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Die Cutting Service Market valued at USD 6.55 billion in 2025, set to grow at a 4.85% CAGR through 2032

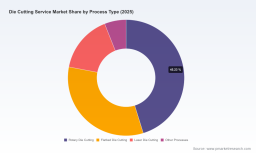
Worldwide Die Cutting Service Market — 2026 Strategic Brief
As we move into 2026, corporate leaders facing capital-allocation, procurement, and sustainability decisions must reconcile a maturing demand base with intensifying technological change and regulatory pressure. PW Consulting’s latest market study — the Worldwide Die Cutting Service Market (base year 2025, forecast 2026–2032) — frames that reconciliation with a concise set of decision-grade insights. The global market reached approximately USD 6,550 Million in 2025 and, under the central case in our model, is forecast to grow at a 4.85% compound annual growth rate (CAGR) through 2032, reaching roughly USD 9,125 Million by the end of the forecast horizon. This briefing highlights the report’s strategic value for 2026 decisions while deliberately withholding the full segmentation tables and granular figures to direct readers to the full report for transaction-ready detail.
Worldwide Die Cutting Service Market
Executive snapshot — why this matters now
-
Growth momentum and volatility coexist. After a steady expansion from the early-2020s, the die cutting services market is entering a phase where moderate growth (mid-single digits) is paired with heightened margin pressure from raw-material swings and compliance costs.
Worldwide Die Cutting Service Market -
Structural fragmentation creates strategic optionality. Market concentration remains low, presenting opportunities for acquirers and incumbent service providers to scale via targeted capacity investments or bolt-on acquisitions rather than broad market roll-ups.
Worldwide Die Cutting Service Market -
Technology and sustainability are the primary differentiators. Advanced rotary and flatbed equipment, digital performance platforms, and material substitution strategies will define winners in the next three years.
Key macro and market signals incorporated in the analysis
-
Historic trajectory: PW Consulting’s baseline traces market expansion from the low billions in 2020 to USD 6.55 billion in 2025, providing a disciplined view of demand recovery and secular shifts.
-
Forecast discipline: The 4.85% CAGR to 2032 reflects scenario-tested assumptions around packaging demand, industrial end markets, and uptake of higher-value die-cut solutions (precision, multi-layer, and sustainable substrates).
-
Input-cost realism: Our analysis embeds recent raw-material indicators — for example, elevated corrugated paper indices and regional price spreads — to stress-test margin scenarios for converters and captive die-cutting operations.
-
Regulatory overlay: Adoption of Extended Producer Responsibility (EPR) measures across multiple U.S. states in 2025–2026, together with tightening recycling and labelling rules, materially affect packaging design cycles and the required capabilities of die cutters and converters.
What the full report contains — practical deliverables for decision-makers
-
Actionable market model: A downloadable, scenario-ready model covering 2020–2032 with baseline, upside, and downside cases; adjustable drivers let users test price, volume, and material substitution assumptions.
-
Service-provider playbook: Supplier selection frameworks, TCO calculators for insourcing vs. outsourcing die cutting, and KPIs for throughput, changeover time, and scrap reduction that procurement and operations teams can adopt immediately.
-
Investment & capacity guide: Capital planning templates, ROI thresholds for new rotary and flatbed lines, and comparative case studies that demonstrate payback timelines under varying utilization levels.
-
Regulatory impact matrix: Line-item analysis of EPR and packaging mandates by jurisdiction, with estimated compliance cost ranges and recommended governance checkpoints for product and packaging owners.
-
Competitive intelligence annex: Vendor profiles, recent strategic moves, and M&A heatmaps that map capability gaps and acquisition targets for strategic buyers. (Note: detailed regional and application splits are available in the full report.)
Competitive landscape — synthesis and strategic implications
The die cutting services ecosystem is populated by specialized converters, global packaging players, equipment OEMs, and toolmakers. PW Consulting’s competitive review synthesizes public disclosures and primary interviews to produce a prioritized set of strategic theses:
-
Specialist converters (long-established, material-focused firms) remain the backbone of bespoke, high-mix work. Their depth in material handling — foams, plastics, complex laminates — keeps them attractive to industrial and medical clients seeking tight tolerances and quick turnarounds.
-
Large packaging players are consolidating value by integrating advanced converting lines and digital print-to-cut workflows. Recent investments by tier-one corrugated providers to add high-precision rotary lines with inline printing demonstrate a clear play to capture higher-value packaging formats and shorten customer lead times.
-
Equipment vendors are extending offerings from machines to service platforms. New flatbed and rotary systems that emphasize quick-change tooling, higher throughput, and connectivity shift the economics toward more flexible, just-in-time die cutting—benefiting converters who invest early.
-
Toolmakers and die suppliers are reducing customer downtime by bundling design-for-manufacture (DFM) services with rapid tooling and lifecycle management; this is a low-cost way to raise switching costs and deepen account penetration.
Representative company moves — which the report analyzes in depth — include major plant investments to expand corrugated conversion capacity, strategic acquisitions adding rotary and rewinding capabilities, and product launches for higher-speed flatbed systems with digital integration. Each of these developments signals where premium pricing and margin pools will concentrate over the next 24–36 months.
2026 implications — five strategic choices for executives
-
Prioritize modular investments. When adding capacity, prefer modular rotary or flatbed lines with quick-change capabilities to limit downtime risk and to capture multiple end-use categories as demand patterns shift.
-
Lock in raw-material exposure. Use hedging, multi-supplier contracts, and indexed pass-through mechanisms for corrugated and board inputs to protect margins against price spikes that remain a prominent near-term risk.
-
Design for recyclability and compliance. Integrate EPR-sensitive design checks into new product approval processes; packaging owners who anticipate compliance costs can avoid last-minute redesigns and reclaim margin.
-
Partner for digital enablement. Engage with equipment OEMs and platform providers to access digital dashboards, predictive maintenance, and quick-change tooling libraries that compress order-to-delivery timelines.
-
Use M&A selectively to buy capabilities. With market concentration low, acquisitions that secure specialized substrates, proprietary tooling, or high-speed digital die-cut lines create disproportionate strategic advantage at modest multiples.
90-day operational playbook for 2026
-
Week 1–4: Run the report’s TCO calculator for current die-cut spend and identify 2–3 supplier candidates for pilot consolidation or co-investment.
-
Week 5–8: Execute material-price stress tests using our model; negotiate at least one dual-source contract with indexed pricing mechanisms.
-
Week 9–12: Commission a pilot line upgrade or toolset consolidation with defined KPIs (changeover time reduction, scrap rate improvement, throughput uplift) and a three-month review window.
Why PW Consulting’s report is decision-useful
-
Operational depth: The study goes beyond high-level forecasts, delivering reproducible models, sourcing frameworks, and capital approval templates you can apply to board-level decisions.
-
Market realism: We integrate recent primary signals — raw-material indices and regulatory timelines — to calibrate downside scenarios and regulatory compliance cost curves.
-
Competitive clarity: Profiles of equipment OEMs, converters, and toolmakers are paired with deal-flow and investment trackers so buyers and strategists can prioritize targets with confidence.
Access and next steps
This briefing intentionally highlights strategic implications while withholding the granular regional and application splits that buyers and investors require for transaction execution. PW Consulting’s full report includes the complete model, regional breakdowns, application-level demand curves, and a ranked list of potential partners and acquisition targets. For procurement teams, investors, and corporate strategists preparing 2026 budgets, the full dataset is designed to plug directly into planning cycles and vendor negotiations.
To obtain the full report, interactive model, and a customized briefing for your company, please visit the report landing page or contact PW Consulting’s industrials practice. The next 12 months will reward organizations that combine disciplined capital allocation with operational agility — this report is engineered to be the operational playbook that helps you make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Die Cutting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com