

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Barrel Compressor Market Valued at USD 5,420.00 Million in 2025, Poised to Reach USD 7,468.95 Million by 2032 at a 4.69% CAGR

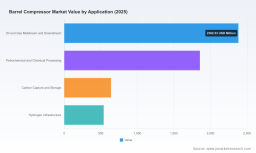
Worldwide Barrel Compressor Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market study on the Worldwide Barrel Compressor Market offers a pragmatic, board‑level toolkit for executives planning capital allocation, supply‑chain design, and technology strategy in 2026. Anchored in five years of historical data and a seven‑year forecast horizon, the report converts industry complexity into executable choices — without overpromising precision where project‑level diligence is required. Below we summarize the high‑value insights that will affect investment pacing, partner selection, and competitive positioning in the year ahead.
Worldwide Barrel Compressor Market
Market trajectory at a glance
After steady expansion through the first half of the decade, the barrel compressor market reached an estimated USD 5.42 billion in our base year (2025). Under a central scenario that reflects current orderbooks, technology adoption rates, and macroeconomic assumptions, PW Consulting projects the market to grow to roughly USD 7.47 billion by 2032 — representing a compound annual growth rate (CAGR) of about 4.7% across the 2026–2032 forecast period.
Worldwide Barrel Compressor Market
This growth is driven by continued demand from energy‑intensive industries (including oil & gas midstream/downstream and petrochemical processing), accelerating deployments in carbon capture and storage (CCS) projects, and nascent but rapidly scaling hydrogen infrastructure programs. Importantly, the market’s expansion is neither uniform nor frictionless: lead‑time pressures, alloy cost volatility and regulatory compliance requirements are shaping buyer preferences toward modular, serviceable barrel designs and supplier ecosystems that can offer integrated lifecycle outcomes.
Worldwide Barrel Compressor Market
Why this report matters for 2026 decision cycles
-
Pacing capital deployments. The quantified market outlook helps you time capex for new-build compressors versus retrofit or service contracts. Our scenario models show where near‑term procurement will most likely yield overcapacity risk versus where immediate investment is necessary to capture project windows (especially in CCS and offshore FPSO projects).
-
Supplier selection and negotiation. With a moderately concentrated supplier base (CR3 ≈ 41.5%; CR5 ≈ 64.9%), buyers can and should pursue differentiated commercial strategies — from long‑term framework agreements to performance‑based contracting — to reduce exposure to single‑vendor lead times and alloy price swings.
-
Aftermarket and service economics. Our margin and lifecycle models show that aftermarket services (maintenance, rebundling, field upgrades) are high‑leverage profit pools. For OEMs, expanding service footprints and digital condition‑monitoring offerings will be decisive. For operators, locking in transparent SLA terms and spares availability reduces unplanned downtime and total cost of ownership.
-
Regulatory and technical compliance. API standards and evolving national requirements are changing spec sheets. Engineering choices made in 2026 — for materials, sealing solutions, and monitoring platforms — will determine compliance costs and retrofit complexity throughout asset life.
Competitive landscape — what to watch in 2026
The barrel compressor value chain is anchored by established turbomachinery OEMs and a growing set of regional suppliers that specialize in large, project‑scale machines. PW Consulting’s supplier benchmarking assesses technical depth, project execution risk, aftermarket reach, and alignment to low‑carbon use cases.
-
Everllence (formerly MAN Energy Solutions). Strong in vertically split RB barrel designs and modular skid solutions, the company’s award for offshore CCS compression in early 2026 highlights its position in CO2 service and offshore project execution. Operators evaluating CCS or offshore compression packages should treat Everllence as a contender for high‑complexity, modular scope.
-
Baker Hughes. With established BCL barrel compressor lines and recent involvement in large FPSO electrification projects, Baker Hughes is a prime choice for integrated rotating equipment scopes tied to major EPCs. Their competitive advantage lies in project systems integration and experience with corrosive and CO2‑rich services.
-
Siemens Energy, Hitachi, Mitsubishi Heavy Industries. These players bring deep engineering and global project experience for high‑pressure process applications. Recent M&A and service expansions (notably Mitsubishi’s acquisition to strengthen rotating equipment maintenance capabilities) underscore a trend: OEMs are consolidating service channels to secure long‑tail revenues.
-
Specialists and regional champions. Companies such as Kobelco, Atlas Copco Gas & Process, ShenGu Group, and Elliott provide differentiated capabilities—ranging from integrally geared solutions to very large reformer compressors and hydrogen‑ready designs. Their presence increases choice but also fragments aftermarket dynamics; careful supplier rationalization is necessary to optimize spares and service networks.
Recent deals and signals relevant to 2026 planning
-
March 2026 — Everllence secured a contract to supply RB barrel compressor skids for a major offshore CCS project in Southeast Asia. The project timeframe and delivery profile signal near‑term demand for modular, offshore‑rated compression packaged with CO2‑service metallurgy and compliance documentation.
-
February 2026 — Mitsubishi Heavy Industries’ acquisition of a Swiss rotating equipment maintenance specialist indicates an industry shift: OEMs are actively integrating maintenance capabilities to reduce aftermarket friction and capture recurring revenues.
-
October 2025 — Baker Hughes’ award for compressor lines serving an all‑electric FPSO demonstrates continued demand for high‑pressure, CO2‑resilient barrel configurations in offshore electrification and gas processing projects.
Technology, standards and supply‑chain dynamics
Three structural dynamics will be decisive in 2026 and beyond:
-
Materials and lead times. Barrel compressors rely on specialized steels and alloys for casings and impellers. Price volatility and allocation risk for these inputs increases project cost uncertainty and extends delivery schedules. Procurement teams should be using hedging strategies and multi‑source qualification to manage this risk.
-
Standards and certification. API 617 remains the critical reference for centrifugal and barrel designs. With a new edition in development, technical and regulatory teams must factor potential changes into equipment specifications and test protocols to avoid costly retrofits.
-
Decarbonization‑driven technical requirements. Energy efficiency, CO2 compatibility, and hydrogen readiness are moving from “nice to have” to specification musts on major projects. Buyers should insist on demonstrable materials compliance for CO2/hydrogen service, modular designs for spoolable maintenance, and digital condition monitoring to enable predictive maintenance.
What the full PW Consulting report delivers (practical components)
This study is designed as an operational playbook for procurement, engineering and strategy teams. Key deliverables include:
-
Forward‑looking demand scenarios and sensitivity analyses that map how timing of CCS, hydrogen and petrochemical investments alters total market demand through 2032.
-
Supplier scorecards assessing execution risk, delivery lead times, aftermarket strength and technology readiness — enabling rapid shortlisting during RFPs.
-
Capex versus Opex trade models for new‑build versus retrofit choices, including net present value sensitivity to alloy price movements and extended delivery risk.
-
Regulatory risk matrices, including anticipated implications from evolving API editions and regional code updates, plus recommended compliance templates for procurement and testing clauses.
-
Commercial playbooks for long‑term service agreements, performance incentives, and spare parts pooling to reduce total lifecycle cost.
-
Target lists and M&A screening criteria for buyers seeking inorganic routes into aftermarket services or specialist metallurgy capabilities.
Recommended actions for executives in 2026
-
Immediate (0–6 months): Run supplier stress tests against alloy supply scenarios; lock in conditional framework agreements for critical skids; prioritize specification clauses for CO2 and hydrogen compatibility.
-
Near term (6–18 months): Rebalance capex spend toward modular/skid solutions where lead times are manageable; pilot digital condition monitoring contracts to reduce unplanned downtime risk.
-
Medium term (18–36 months): Consider acquisitions or strategic partnerships to secure aftermarket capacity; establish multi‑tiered spares pooling in regions where supplier concentration elevates delivery risk.
Methodology, transparency and the “preview” purpose
PW Consulting’s analysis synthesizes proprietary primary interviews, OEM and EPC orderbook tracking, and an audited dataset of historical market flows (2020–2025). Forecasts are driven by scenario‑based modelling that incorporates project pipelines, expected technology adoption curves and macroeconomic assumptions. The purpose of this release is to present senior leaders with the strategic implications they need to act in 2026 while preserving project‑level detail for clients who require transaction‑grade data.
Readers should note that this briefing purposefully omits certain granular segmentation figures and deal‑level valuations; those are included in the full report and accompanying datasheets available through PW Consulting. The full dataset contains region and application splits, detailed supplier revenue shares, and project‑level timelines that are essential for procurement RFPs, M&A diligence and vendor negotiations.
Next steps
For executive teams preparing 2026 budgets and three‑year strategic plans: PW Consulting recommends securing access to the full report and workbook. That package will enable you to perform supplier shortlisting, run bespoke sensitivity tests against your project pipeline, and operationalize the aftermarket and procurement playbooks we outline.
To obtain the complete Worldwide Barrel Compressor Market report, including downloadable datasets and the supplier scorecard workbook, please visit PW Consulting’s publications page or contact your client representative for an enterprise delivery and workshop tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Worldwide Barrel Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com