

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hydrochar Market Poised for Robust Expansion with 8.5% CAGR Through 2032

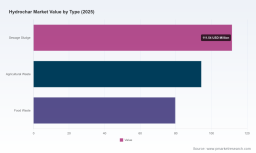
Worldwide Hydrochar Market — Strategic Outlook 2026: Actionable Intelligence for Decision-Makers
PW Consulting’s latest market study, Worldwide Hydrochar Market (base year 2025; historical coverage 2020–2025; forecast period 2026–2032), delivers a focused, decision-ready intelligence pack for executives, investors and policy teams planning ahead for 2026. The sector is entering a formative phase: hydrochar is moving beyond pilots and niche projects into industrial-scale deployments, with the market expanding at a compound annual growth rate (CAGR) of 8.5% through 2032. Our briefing synthesizes market trajectory, competitive pressures, regulatory levers and practical commercial pathways — while preserving the granular, proprietary splits that underlie our models to encourage direct engagement with the full report.
Worldwide Hydrochar Market
Market snapshot: trajectory and commercial inflection
Hydrochar has transitioned from demonstration technologies to economically material supply chains. By 2025 the market had reached a midpoint in its maturation curve, and our base-case forecast sees continued acceleration across 2026–2032 driven by industrial co-firing, soil amendment applications, and increased valorisation of wet biomass residues. The combination of technology advances, circular-economy policy hardening, and carbon-accounting levers supports an 8.5% CAGR to 2032, creating an expanded addressable market for technology licensors, plant OEMs, feedstock consolidators and offtakers.
Worldwide Hydrochar Market
- Industrialization window: multiple modular HTC/HTC-like platforms are now proven at multi-thousand tonnes per year scale, reducing per-tonne capex risk for first movers.
- Commercial value stacking: energy densification, long-term carbon retention and soil fertility services create layered revenue opportunities beyond simple fuel substitution.
- Policy tailwinds: evolving waste-management directives, renewable-energy targets and emissions trading schemes materially improve project IRRs when accounted for in multi-service business models.
Why this report matters for 2026 strategic decisions
For leaders preparing capital allocation, partnerships or regulatory advocacy in 2026, the report functions as a playbook to prioritize scarce resources and reduce execution risk. Key strategic uses include:
Worldwide Hydrochar Market
- Capital deployment: scenario-based valuation frameworks that stress-test feedstock availability, co-firing premiums and carbon-credit uplifts to isolate high-return plant configurations.
- M&A and JV screening: an acquisition scorecard that identifies targets offering immediate scale-up potential versus those requiring heavy retrofit investment.
- Policy and permitting strategy: regulatory impact maps that show which policy changes generate outsized value for hydrochar projects and where lobbying efforts should be concentrated.
- Offtake and commercialization: commercial negotiation playbooks for securing long-term offtake agreements across energy, soil and activated-carbon markets.
Report contents — practical, hands-on, and transaction-focused
The Worldwide Hydrochar Market report goes beyond high-level narrative. It is purpose-built for deployment teams and investment committees, including:
- Proprietary market model (USD Million base) with transparent assumptions and sensitivity tables for carbon price, gate fees and energy prices.
- Technology and CAPEX benchmarking across HTC variants, ERC and HTCycle-like platforms, including scale curves and operating cost envelopes.
- Feedstock mapping and logistics matrices that capture availability, seasonality and wet-residue handling costs in key sourcing basins.
- Commercial use-case playbooks for energy co-firing, soil amendment productization and activated-carbon route-to-market, with contract templates and margin drivers.
- Risk register and mitigation measures addressing quality variability, permitting timelines, and feedstock consents — each rated by impact and likelihood.
To maintain a high-value executive experience and protect the proprietary work that underpins our recommendations, detailed regional and application splits are reserved for report subscribers; summary-level insights are included herein to guide strategic choices without disclosing the underlying segment numbers.
Competitive landscape: who to watch
The market is populated by technology developers, plant operators and specialized feedstock integrators. Our competitive review synthesizes capabilities, recent commercial moves and likely strategic paths for the following firms (representative, not exhaustive):
- Ingelia (Barcelona, Spain): Commercialized hydrochar plants focused on sewage sludge and urban biowaste. Their operational experience in Europe provides early learning on permitting, solids handling and product compliance.
- TerraNova Energy GmbH (Münster, Germany): Developer of HTCycle-style industrial plants; active in partnering for large-scale municipal and industrial residue projects, highlighting the importance of EPC and local integration capabilities.
- BlackCarbon GmbH (St. Pölten, Austria): Focus on premium hydrochar from woody and agricultural residues as a drop-in coal alternative — signaling a premium product strategy targeting industrial boilers.
- Arbaflame A/S (Aarhus, Denmark): Pelletized hydrochar for co-firing applications; demonstrates the role of downstream product engineering in securing utility offtake.
- Haffner Energy (Vitry-le-François, France): ERC-based SynChar pilot and certification experience; emphasizes the interplay between certification, quality assurance and market acceptance.
- Antaco (Santiago, Chile): Regional pure-play leveraging forestry residues and sewage feedstocks in South America, illustrating geographic strategies for feedstock arbitrage and proximity to customers.
Recent corporate developments underscore the ramping commercial momentum: European commercial plant launches, capacity expansions and certified pilots have moved developers from validation to scale. For corporate strategists, the important signals are not just which company has the largest footprint today, but which can control feedstock logistics, guarantee product quality and secure multi-faceted revenue streams (energy + carbon + soil services).
Regulatory and macro drivers shaping 2026 outcomes
- Waste policy: Mandatory separate collection of biowaste and tighter waste hierarchy rules in major markets accelerate feedstock availability for hydrothermal carbonization (HTC) pathways.
- Carbon accounting: Eligibility for emissions trading and recognized carbon crediting routes materially improves project economics where co-firing or long-term carbon storage is demonstrable.
- Resource scale: Wet biomass residues in Europe and other regions represent a large latent feedstock pool; unlocking them efficiently will determine who wins the low-cost supply positions.
- Material performance: Hydrochar’s typical carbon yields and energy densification properties create compelling fuel-substitution economics and long-term soil carbon benefits when verified to standards.
Executives must monitor three regulatory fault lines into 2026: feedstock classification updates, thermal-processing emission limits, and carbon-credit recognition frameworks. Each can swing project IRRs and alter the optimal product focus between energy and soil markets.
Risk profile and mitigation — an operator’s checklist
Hydrochar project success is contingent on aligning technical, commercial and regulatory variables. Our report provides an operator’s checklist, but the highest-priority mitigations include:
- Feedstock contracts with volume and quality clauses to reduce variability risk;
- Modular plant designs that permit phased capex deployment and technology upgrades;
- Multi-revenue product design to capture gate fees, energy value and carbon credits; and
- Third-party certification protocols for product acceptance in fertilizers and co-firing markets.
Investment and partnership playbook for 2026
For investors and corporate development teams, 2026 will be a year to shift from exploration to execution. Recommended near-term actions include:
- Prioritise one or two commercial pathways (e.g., industrial co-firing vs. soil amendment) and design pilot-to-scale transition plans that secure offtake before major capex.
- Structure deals with staged earn-outs and performance milestones to bridge technology risk and commercial acceptance.
- Build local feedstock alliances — municipal contracts, forestry residue agreements or food-waste aggregators — to insulate plants from spot-price swings.
- Engage early with regulators and carbon standard bodies to solidify crediting pathways ahead of project commissioning.
Conclusion — positioning for 2026
Hydrochar is no longer an experimental novelty; it is an investable class with diversified commercial pathways and policy-backed upside. The market is on a clear growth trajectory through 2032 at an 8.5% CAGR, transforming opportunities for technology vendors, fuel markets and agronomic-product suppliers. That said, the winners in 2026 will be those who combine disciplined feedstock strategies, modular project economics and proactive regulatory engagement.
PW Consulting’s Worldwide Hydrochar Market report equips decision-makers with the practical modelling, competitive intelligence and transaction-ready templates required to execute in 2026. For the full proprietary segmentation, regional scenario matrices, and downloadable model files, visit our publication page to access the complete report and accompanying data pack.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com