

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Copper Hollow Conductors Market to Reach USD 403.9 Million by 2032

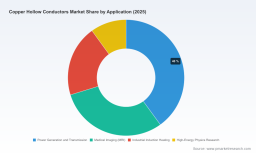
Worldwide Copper Hollow Conductors Market: Strategic Insights for 2026 Decision‑Makers
As global electrification projects scale and high‑performance applications place ever‑greater demands on conductor geometry and thermal management, copper hollow conductors have moved from a niche engineering component to a strategic procurement category. PW Consulting’s latest market study—anchored to a 2025 base year and spanning historical analysis (2020–2025) with a 2026–2032 forecast—delivers the actionable intelligence executives need to make procurement, manufacturing, and M&A decisions in 2026. The market is projected to grow at a compound annual growth rate (CAGR) of 5.49% through the forecast window, moving from an estimated market size of USD 277.65 Million in 2025 toward the high‑hundreds by 2032 under our baseline scenario.
Worldwide Copper Hollow Conductors Market
Why 2026 Is a Turning Point
-
Demand vectors are multiplying. Beyond traditional power‑generation uses, demand from advanced medical imaging, induction heating for industrial processes, and infrastructure projects supporting AI data centers and EV electrification are changing the product and supplier requirements for hollow conductors. These applications prioritize complex cross‑section geometries, internal cooling channels, and metallurgical consistency.
Worldwide Copper Hollow Conductors Market -
Raw‑material volatility is intensifying procurement risk. Copper prices experienced historic peaks in early 2026 before moderating; forward projections from major banks and commodity desks show elevated price ranges through the year. At the same time, treatment and refining charge dynamics are pressuring midstream economics—creating a squeeze between raw‑material cost spikes and downstream margin compression.
Worldwide Copper Hollow Conductors Market -
Industry concentration and capability thresholds matter. The market exhibits a meaningful level of concentration among the top suppliers, with CR3 and CR5 metrics that point to supplier influence over lead times and technical differentiation. For buyers, this implies that strategic relationships and detailed supplier performance assessment are now critical levers to manage both continuity of supply and technical risk.
What This Report Delivers (Practical, Executable Content)
-
Comprehensive market sizing: historical (2020–2025) reconciliation and a granular 2026–2032 forecast model that executives can plug into corporate planning. The report provides top‑line revenue trajectories and scenario variants anchored to a 5.49% baseline CAGR.
-
Pricing and margin playbook: a transparent pass‑through model for raw‑material inputs, pricing sensitivity analyses, and recommended hedging approaches to insulate procurement from short‑term spikes.
-
Supplier landscape and scorecards: operational, technical and commercial diagnostics for incumbent and emerging producers—covering manufacturing footprint, tooling flexibility, metallurgical capability, lead‑time profiles, and certification readiness.
-
Go‑to‑market and product strategy templates: recommendations for product differentiation by conductor profile, cooling integration, and machining friendliness that accelerate time‑to‑value for OEMs.
-
M&A and strategic sourcing screens: a prioritized shortlist of acquisition and alliance targets, plus a transaction preparedness checklist focused on integration risks unique to hollow conductor producers.
-
Scenario stress tests: upside, base, and downside cases reflecting commodity price paths, demand shocks (e.g., delayed hospital procurement cycles or slower EV rollout), and policy changes affecting trade and recycling.
Competitive Landscape: Who Matters and Why
Our primary research and facility evaluations surfaced a differentiated supplier set. Leading vendors combine specialized tooling, metallurgy, and application know‑how; smaller producers compete on cost, niche geometries, or proximity to local buyers. Selected strategic profiles included in the report:
-
Luvata (Pori, Finland) — recognized for custom designs and an exceptionally broad tool library enabling short lead times and tight tolerances. Their strength in high‑field MRI coils and EV stator direct‑cooling solutions makes them an anchor supplier for OEMs focused on performance.
-
KME (Germany) — a multi‑plant European group with broad copper and alloy capabilities. Recent research initiatives on digital traceability along the production chain illustrate the firm’s emphasis on process transparency—a rising procurement requirement among major buyers.
-
Proterial Metals (Japan) — offers metallurgical depth using tough‑pitch copper variants optimized for magnetic coils and high‑current applications; their established heritage in precision formed bars and hollow profiles is a competitive advantage for critical, certified applications.
-
cunova, Fabmann, Oriental Copper, Extube, S&W Wire, Channel Metal — each brings a mix of regional footprint, tooling sophistication, and niche process benefits (e.g., oxygen‑free copper, seamless tubing, extrusion/drawing surface quality, or complex profile forming). Buyers must weigh these operational strengths against long‑term reliability and certification pathways.
While we map capabilities and commercial posture across a broad vendor set, the report deliberately refrains from publishing sensitive segmentation figures in this public summary—access to full scorecards and ranking methodologies is provided to subscribers and clients.
Strategic Imperatives for 2026
-
Institutionalize a raw‑material risk framework. Given historic copper price gyrations and evolving TC/RC dynamics, buyers should adopt layered defense strategies: short‑term hedges, multi‑year supply agreements with indexed pricing, and selective vertical integration where feasible.
-
Prioritize supplier qualification by capability, not price. For high‑value applications, marginal quality differences translate into lifecycle savings. Our supplier scorecards quantify this trade‑off and provide procurement triggers for escalated qualification.
-
Invest in design‑for‑manufacturing (DFM) partnerships. Early collaboration with tool‑rich suppliers reduces tooling cost amortization and accelerates qualification—crucial when time‑to‑market affects competitive positioning in MRI or EV subassemblies.
-
Use scenario planning to inform capital allocation. Under our baseline CAGR, selective capacity expansion and tooling modernization have attractive payback profiles; however, downside commodity scenarios warrant stepped investments and contractual safeguards.
-
Explore product and supply diversification. Where concentration risk is material, implement dual‑sourcing and regional supplier development programs to mitigate geopolitical and logistical shocks.
Scenario Analysis: Translating Markets into Decisions
Our models run three practical scenarios for boardrooms: a conservative downside (commodity shock + demand lag), a baseline (5.49% CAGR), and an upside (accelerated electrification and AI‑driven infrastructure spending). Each scenario is tied to recommended tactical responses—ranging from renegotiating take‑or‑pay contracts and deferring capital projects, to advancing M&A talks for rapid capability acquisition when demand tightens. Notably, low TC/RC metrics in the refining space create asymmetric exposure for midstream players; companies with integrated procurement and commercial hedging capabilities are best placed to capture value across cycles.
How PW Consulting Supports 2026 Execution
-
Bespoke advisory for supplier selection and contract structuring, leveraging our scorecards and negotiation playbooks.
-
M&A due diligence focused on metallurgical IP, tool libraries, and production repeatability—areas where hidden liabilities often appear.
-
Operational improvement programs to shorten lead times and optimize cost‑to‑serve for hollow conductor lines.
-
Custom scenario models and an interactive Excel toolkit that allow your planning teams to test price, demand, and sourcing assumptions in real time.
Executives preparing 2026 strategies need more than high‑level signals; they need validated supplier capabilities, pass‑through economics, and transaction roadmaps. PW Consulting’s report synthesizes these elements while preserving the competitive confidentiality of detailed segment allocations and supplier rankings—elements we deliver directly to clients and subscribers through secure access.
To obtain the full dataset, vendor scorecards, and the interactive forecast model that powerboardroom decisions in 2026, visit the report page or contact our advisory team for a briefing. The path from commodity volatility to resilient supply and profitable growth runs through disciplined procurement, targeted partnerships, and scenario‑driven capital allocation—areas where this study provides immediate, executable value.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Hollow Conductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com