

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Brake Force Sensors Market to Jump from USD 485.32 Million in 2025 to USD 897.84 Million by 2032 on a 9.2% CAGR

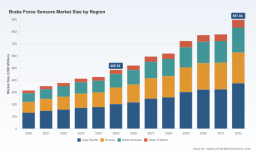
Worldwide Brake Force Sensors Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market study on Worldwide Brake Force Sensors delivers a focused, decision-grade perspective designed to guide executive teams through the inflection point arriving in 2026. Built on a robust historical base (2020–2025) and a detailed projection horizon (2026–2032), the report quantifies a market expanding at a compound annual growth rate (CAGR) of 9.2%. After rising from approximately USD 315.4 Million in 2020 to USD 485.32 Million in 2025, the market is projected to exceed USD 520.51 Million in 2026, and continue its trajectory toward nearly USD 897.84 Million by 2032. These headline metrics frame a market that is maturing rapidly while simultaneously being reshaped by technology, regulation, and new vehicle architectures.
Worldwide Brake Force Sensors Market
Why 2026 Is a Strategic Inflection Year
-
Regulatory momentum and safety mandates are compressing adoption timelines. New rule sets that expand requirements for automated emergency braking and other active safety functions are increasing both OEM demand and supplier obligations for validated, functionally safe force-sensing solutions.
Worldwide Brake Force Sensors Market -
Vehicle architecture transitions — most notably the shift toward electromechanical and brake-by-wire subsystems in passenger and commercial applications — convert passive measurement points into control nodes, elevating sensors from test instrumentation to critical control elements.
Worldwide Brake Force Sensors Market -
Economic scale and technology roadmaps are aligning in favor of suppliers that can pair high-integrity measurement with robust functional safety (FuSa) practices, validated calibration chains, and supply assurance for automotive-grade volumes.
Market Dynamics and Technology Evolution
-
Sensor functionality is migrating from singular measurement to system-level control enablement. For vehicle manufacturers, the ability to close the loop on clamping or pedal force provides tangible benefits: shorter stopping distances under automated regimes, more predictable regenerative braking behavior in electrified powertrains, and improved fail-operational strategies for ADAS.
-
Technology differentiation remains a competitive lever. While multiple sensing modalities coexist — each with clear pros and cons on accuracy, bandwidth, cost, and integration complexity — the strategic winners will be those that marry high fidelity sensing with scalable manufacturing and automotive-grade qualification processes.
-
Testing and validation complexity is increasing. As sensors assume control responsibilities, test cycles extend to cover ASIL-aligned verification, environmental endurance, electromagnetic compatibility, and system integration testing — increasing the time and cost to production readiness.
-
Supply-chain resilience is now table stakes. The shift to higher-volume, safety-critical sensor content requires suppliers to demonstrate multi-site manufacturing strategies, traceable material provenance, and end-to-end quality systems compatible with OEM production assurance programs.
Regulatory & Standards Drivers
-
New regulatory mandates for active braking systems are accelerating demand for force sensing that can interface with AEB and related control systems. These mandates are not only increasing unit content per vehicle but also elevating system validation requirements.
-
ISO 26262 and Automotive Safety Integrity Level (ASIL) obligations mean that functional safety compliance is no longer optional for suppliers targeting embedded brake-force sensing; it is a minimum market entry requirement for mainstream volume applications.
-
Performance and test standards for larger vehicles continue to rely on validated force measurement during type-approval and in-service surveillance, reinforcing the role of high-accuracy sensors across a broader set of transportation markets.
Competitive Landscape — Who Matters and Why
The market exhibits moderate concentration: the top three players capture a meaningful portion of industry revenue while the top five represent a clear leadership tier. This structure produces room for specialized innovators to coexist with larger multi-domain suppliers that can bundle sensing into broader vehicle electronics portfolios.
-
Sensata Technologies (Attleboro, Massachusetts, USA) — Positioned as a technology integrator, Sensata’s Micro Strain Gauge (MSG) implementations are being adopted into next-generation electromechanical brake (EMB) calipers and drums. Their production nominations for EMB integrations underscore an ability to move from qualification to production in partnership with tier-1 OEM brake manufacturers.
-
Methode Electronics (Chicago, Illinois, USA) — Aktie in magnetoelastic pedal-force measurement for safety-critical booster applications highlights a niche strategy: non-contact sensing approaches tailored to emergency and backup systems where redundancy and fail-safe behavior are paramount.
-
TE Connectivity (Schaffhausen, Switzerland) — Leveraging a broad portfolio of force, pressure, and position sensors, TE is advantaged where customers prefer integrated solutions that address multiple vehicle subsystems, supported by strong functional safety engineering capabilities.
-
FUTEK Advanced Sensor Technology (Irvine, California, USA) — Known for precision load-cell products for pedal and test applications, FUTEK is a supplier of choice for R&D and validation programs where measurement fidelity drives development cycles.
-
Strainsert (West Conshohocken, Pennsylvania, USA) — Offers customizable sensing solutions for OEM and test-bed needs, representing a class of suppliers that convert bespoke engineering into production-intent components for validation and endurance testing.
-
Althen Sensors (Leiden, Netherlands) — Focused on specialized automotive sensors for pedal and hand-brake measurements, Althen demonstrates how focused product portfolios can capture share in validation and field-testing channels.
Notably, Sensata’s 2023 production nomination for EMB integration signals the first wave of mainstream transitions from pilot programs to high-volume production readiness — a validation event with outsized implications for supplier selection, tier-1 partnerships, and OEM sourcing strategies ahead of 2026.
What the PW Consulting Report Provides (Practical, Executable Deliverables)
-
Proprietary market model: a validated forecasting engine with scenario toggles to test assumptions around adoption curves, price erosion, and technology substitution under multiple regulatory scenarios.
-
Decision frameworks: go-to-market matrices that help suppliers choose between direct OEM engagement, tier-1 partnerships, or licensing strategies based on cost to qualify and time-to-production metrics.
-
Functional safety and validation playbook: a step-by-step roadmap to achieve ASIL alignment, including test plan templates, recommended toolchains, and worst-case latency analysis for control loops that include force feedback.
-
Supply-chain and capacity assessment tools: an audit checklist and contingency playbook to translate forecast growth into manufacturing investments, multi-sourcing plans, and inventory strategies that minimize qualification friction.
-
Competitive heatmaps and capability matrices: granular company profiles and capability comparisons that reveal partner fit, technology gaps, and acquisition targets without disclosing confidential contract-level economics.
-
Validation and test-lab benchmarking: recommended performance tests, durability cycles, and environmental stress regimes tailored to brake-force sensor applications in passenger, commercial, and off-highway vehicles.
Strategic Priorities for 2026 — A Checklist for Decision-Makers
-
Lock in FuSa capability now: invest in ISO 26262-compliant processes, toolchains, and third-party auditors in 2025 to be bid-ready for 2026 programs.
-
Prioritize closed-loop use cases: position sensing products not just as measurement devices but as enablers of braking control strategies — OEMs increasingly buy systemic capability, not components.
-
Demonstrate capacity and traceability: create multi-site qualification templates and supplier scorecards that address OEM concerns about single-source risk and material provenance.
-
Design for validation: adopt standardized interface and calibration protocols that reduce program friction and shorten engineering validation timelines on production ramps.
-
Prepare M&A and partnership options: use the 2026 window to selectively acquire niche capability (e.g., specialized sensing modalities or calibration IP) or to anchor long-term commitments with tier-1 integrators.
Timing & Tactical Roadmap
-
Immediate (now–Q2 2026): Complete FuSa gap assessments, finalize pilot supply agreements, and complete environmental qualification suites that mirror OEM test cycles.
-
Near term (H2 2026–2027): Scale manufacturing capacity for targeted programs, secure long-lead semiconductor and raw-material commitments, and validate in-vehicle system behavior under automated braking regimes.
-
Medium term (2028 onwards): Convert validated pilots into multi-platform content by leveraging field data to cost-engineer solutions for broader vehicle lineups and adjacent markets.
Concluding Perspective
The brake force sensor market sits at an important crossroads: regulatory pressure, new vehicle electrical architectures, and the operational needs of automated braking systems are creating a growth runway that is both attractive and demanding. The headline CAGR of 9.2% and the projected near-term expansion — from roughly USD 485.32 Million in 2025 to more than USD 520.51 Million in 2026, and toward USD 897.84 Million by 2032 — capture the scale of opportunity. Yet unlocking that opportunity requires disciplined investments in functional safety, validation capacity, supply-chain resiliency, and algorithms that convert measurement into reliable control.
PW Consulting’s Worldwide Brake Force Sensors report condenses these imperatives into a pragmatic playbook and an executable market model. For teams deciding capital allocation, product roadmaps, or M&A targets in 2026, this study provides the operational templates and scenario analytics needed to move from insight to action. For a complete set of granular regional and application-level forecasts, segmentation data, downloadable models, and full company profiles, please consult the full report on our publication page.
For detailed analysis of this topic, please visit the official page: Worldwide Brake Force Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com