

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pigment-grade Titanium Dioxide Market Poised to Grow at a 4.52% CAGR, Led by Asia Pacific Demand

Worldwide Pigment-grade Titanium Dioxide Market — Strategic Imperatives for 2026
Executive summary
As companies reset priorities for 2026 investment cycles, pigment-grade titanium dioxide (TiO2) remains a linchpin input across paints & coatings, plastics, paper and printing inks. Our new PW Consulting market study uses 2025 as a base year and a 2026–2032 forecast horizon to quantify opportunity and risk. The global market grew from a roughly USD 19.3 billion base in 2020 to approximately USD 24.2 billion in 2025 and is projected to exceed USD 25.6 billion in 2026, with a forecast compound annual growth rate (CAGR) of 4.52% through the modelled period. Market concentration at the top shows mid-range consolidation (CR3 ~38.5%; CR5 ~52.1%), signaling both entrenched scale advantages and continued room for regional or capability-driven entrants.
Worldwide Pigment-grade Titanium Dioxide Market
Why this report matters for 2026 decision-makers
- Timing: 2026 is the inflection point for several structural shifts — raw-material tightness, regulatory re-rating in major markets, and a wave of grade innovation for lower-VOC and waterborne systems.
- Actionability: the study translates macro forecasts into executable options — capacity posture, price-setting frameworks, product roadmaps and M&A screens — so executives can move from insight to capital allocation within a single planning cycle.
- Risk-aware scenarios: our modelling explicitly prices supply shocks, tariff regimes and energy-cost variability, enabling stress-tested strategy for procurement, plant utilization and trade policy exposure.
Drivers and headwinds shaping 2026
The industry entering 2026 is operating under five converging dynamics that demand strategic clarity:
Worldwide Pigment-grade Titanium Dioxide Market
- Raw-material pressure: ilmenite ore tightened in late 2024; market-level benchmarks averaged in the low hundreds of USD per metric ton in Q4 2024, reflecting supply-side constraints in Australia and South Africa. Feedstock cost volatility flows directly to cash margins for producers that lack ore diversification or backward integration.
- Energy and emissions controls: electricity surcharges and carbon-related levies in China increased production costs materially in 2024. For energy-intensive chloride-process sites and legacy sulfate-process assets, this shifts the relative cost curve and alters retrofit priorities.
- Regulatory re-pricing: policy moves such as the elimination of backward sulfate-process capacity in China and tightened REACH restrictions on nano-forms in the EU have immediate operational implications (permit timelines, forced idling) and medium-term supply reallocation effects.
- Trade friction: tariffs — notably ongoing Section 301 measures affecting Chinese TiO2 into the US — remain an active constraint on arbitrage and import strategies for buyers and sellers, effectively reshaping go-to-market footprints.
- Product and process innovation: commercialization of grades optimized for waterborne and high-dispersibility systems, alongside chloride-process expansions in lower-cost jurisdictions, are re-segmenting premium demand and margins.
Competitive landscape — where incumbents and challengers stand going into 2026
The market combines large, vertically integrated producers with specialized regional players. Recent company-level developments have tactical and strategic implications for buyers, investors and competitors:
Worldwide Pigment-grade Titanium Dioxide Market
- Large global brands continue to leverage integrated distribution and branded-grade premiumization. For example, a leading US-based producer launched a new waterborne-optimized grade in 2024 that targets the high-growth segment of architectural and industrial waterborne coatings.
- Producers focused on chloride-process scale have moved to expand low-cost capacity; a notable expansion in southern Africa completed in 2024 adds significant exportable tonnage and alters regional supply balances.
- Price discipline is being tested: one major supplier announced a mid-2024 global price increase in response to input-cost inflation — a signal to markets that pass-through viability is returning for several producers.
- Operational disruptions remain real: a Chinese producer declared force majeure during winter restrictions in 2023, underscoring the persistence of seasonal, regulatory and energy-related constraints that can create near-term tightness.
Collectively, these actions matter because the top-tier producers hold a meaningful share of the market but not an overwhelming one; mid-sized incumbents and regional champions retain the ability to influence local pricing and service dynamics.
Strategic levers for 2026 — what leaders should do now
Translate the market picture into a prioritized set of moves designed to protect margin and capture upside:
- Supply-side resilience: secure forward contracts or equity stakes in feedstock sources; evaluate backward-integration options where incremental NPV is positive. Where tariffs or regulatory closures create localized risk, prioritize alternative sourcing lanes.
- Cost-surface optimization: accelerate energy-efficiency and emissions-reduction investments at high-intensity plants. For many producers, projects that reduce specific energy use or enable fuel-switching recover within a medium-term window when modelled against the report’s forecasted price environment.
- Portfolio differentiation: segment customers by value-to-customer (e.g., high-dispersion coatings vs. commodity paper pigment) and price accordingly. Invest selectively in premium grades that command a margin uplift under a waterborne-forward coatings landscape.
- Capacity and plant strategy: run a disciplined utilization and brownfield expansion agenda rather than broad greenfield exposure — our scenario work shows better risk-adjusted returns in capacity optimization and targeted expansions near feedstock or low-cost power sources.
- Regulatory and product stewardship: align product development and labeling to new REACH requirements and emerging EHS norms; maintain certification roadmaps to avoid market exclusion for key customers in the EU.
- M&A and tactical buying: monitor asset sales arising from enforced capacity elimination or from players unable to amortize high-cost plants. The report’s proprietary M&A screen identifies shortlists by geography, capex profile and environmental exposure.
- Commercial and channel plays: deploy concentric bundling with additives and dispersants to defend margins and create switching costs for customers transitioning to low-VOC systems.
What the PW Consulting report delivers — practical components
Our deliverable is designed for fast incorporation into 2026 planning cycles. Highlights include:
- Topline market sizing and historic reconciliation (2020–2025) and a granular forecast by scenario for 2026–2032, expressed in USD (million) with sensitivity bands around the base case CAGR of 4.52%.
- Competitive benchmarking and strategic profiles for the sector’s major producers, mapping plant footprints, primary technologies (chloride vs. sulfate), and recent strategic moves.
- Cost-of-production models and regional cost curves that let you simulate margin impacts under different feedstock, energy and carbon-price trajectories.
- Regulatory matrix and trade-impact dashboard covering EU REACH, China capacity policy, and current US tariff exposure, with mitigation playbooks for each jurisdiction.
- Commercial playbooks: go-to-market options by customer segment, pricing elasticity tests and SKU rationalization templates designed to move procurement and sales teams from insight to action.
- M&A target lists and valuation heuristics that prioritize assets with feedstock access, favorable energy cost buckets and clean permit positions.
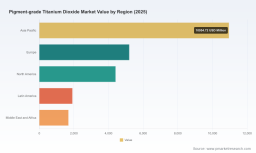
Note: this press release intentionally omits detailed sub-segment tables and regional/application splits to preserve the value of the full dataset. The full report contains those actionable line items and downloadable models.
90-day sprint for executives
To convert insight into results in the first quarter of 2026, we recommend a focused 90-day program:
- Days 1–30: Run the PW Consulting stress tests against your facility and customer book; identify 2–3 highest-impact supply risks and a near-term pricing play.
- Days 31–60: Execute supplier or feedstock contracts to lock material flows; launch a pilot energy-efficiency retrofit at a single high-intensity site and finalize an M&A go/no-go shortlist.
- Days 61–90: Roll out revised commercial pricing tiers for premium grades, and confirm regulatory compliance actions for core export markets.
Closing — where to get the full intelligence
The coming 12–18 months will reward clarity and speed. PW Consulting’s Worldwide Pigment-grade Titanium Dioxide Market report packages market-sizing, competitor intelligence, regulatory mapping and executable playbooks into a single decision-grade deliverable for 2026 planning cycles. For boards, strategy teams, heads of procurement and investors looking to lock in advantage, the full dataset and interactive models are available through our report portal — access will provide the sub-segment detail, regional breakdowns and downloadable financial models omitted here to preserve the report’s commercial value.
Contact PW Consulting to book a briefing and receive the executive dataset, scenario models and a tailored 90-day implementation roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Pigment-grade Titanium Dioxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com