

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide During Production Inspection (DPI) Market Poised to Grow at 6.45% CAGR, New Report Reveals

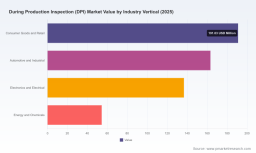
Worldwide During Production Inspection (DPI) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study, Worldwide During Production Inspection (DPI) Market, provides a focused, practitioner-oriented intelligence package designed to inform critical supplier, capital, and operational decisions in 2026. Anchored on a 2025 base year and spanning a robust historical series (2020–2025) with a forward-looking forecast window (2026–2032), the report synthesizes market trajectory, competitive positioning, regulatory implications, and tactical playbooks that matter now. In short: this is not a theoretical desk study — it is a strategic operations and commercial toolkit for the year ahead.
Worldwide During Production Inspection (DPI) Market
Market snapshot: trajectory and scale
The DPI market has demonstrated consistent expansion over the past half-decade, rising from a modest baseline in 2020 to an estimated USD 545.6 million in 2025. Our modeling projects continued growth through the forecast period, reaching approximately USD 845.1 million by 2032 — an implied compound annual growth rate (CAGR) of 6.45% across 2026–2032. These macro dynamics reflect enduring demand for in-line quality assurance as global supply chains face rising regulatory scrutiny, reshoring and nearshoring initiatives, and a shift toward hybrid inspection models that blend physical presence with digital monitoring.
Worldwide During Production Inspection (DPI) Market
Market structure analysis shows a moderately fragmented landscape: the top three firms account for roughly 28% of market revenues, while the top five approach the high 30s percentile. This degree of concentration underscores meaningful opportunities for specialist providers and technology-enabled entrants to carve out scalable niches, while established inspection majors defend share through network breadth and cross-service bundling.
Worldwide During Production Inspection (DPI) Market
Why this matters for 2026 planning
- Procurement and quality assurance leaders must reassess supplier monitoring portfolios. The market’s steady growth and regulatory pressure mean that relying solely on post-shipment checks is increasingly untenable; early intervention through DPI reduces rework, recalls, and supplier remediation costs.
- Service providers face a bifurcated opportunity set: reinforcing traditional on-site DPI capabilities while fast-scaling remote and digital-monitoring offerings to reduce marginal inspection costs and improve sampling intensity.
- Investors and M&A teams should prioritize targets with strong digital tooling, regional execution networks, or sector-specialized competencies that enable cross-selling into adjacent testing, certification, and supply-chain assurance streams.
Report contents: practical tools and what you’ll be able to act on
PW Consulting designed this report with implementable outputs in mind. Highlights include:
- Comprehensive market sizing and trend narratives (2020–2032) in USD Millions, including historical analysis and modelled scenarios under alternative adoption and regulation assumptions.
- Decision frameworks for procurement teams that translate quality objectives into inspection program design — frequency, sampling strategy, and escalation rules — tailored to common manufacturing modalities.
- Service-provider playbooks covering route-to-market tactics: pricing levers for bundled assurance services, resource optimization for inspector networks, and digital productization strategies for remote monitoring and data analytics.
- Risk matrices that map regulatory triggers, supply-chain fragility points, and technology disruption timelines to probable margin and service-demand outcomes.
- Benchmarked competitive profiles and capability maps for leading global players, with suggested partnership and differentiation strategies for regional and specialist firms.
- An operational checklist for deploying hybrid DPI programs combining on-site verification with continuous remote monitoring and exception-driven physical audits.
To preserve the report’s commercial value as a strategic resource, we intentionally withhold granular subsegment revenue breakdowns and proprietary scenario tables in this summary; these items remain detailed in the subscription package and online report portal.
Competitive landscape: what the majors are doing and where gaps remain
The DPI value chain is populated by a set of established global assurance and testing firms whose strengths lie in extensive inspector footprints, certification credentials, and sectoral depth. Key incumbents analyzed in the report include SGS, Bureau Veritas, Intertek, TÜV Rheinland, TÜV SÜD, DNV, DEKRA, Eurofins Scientific, UL Solutions, Kiwa, Cotecna, Applus+, and LRQA. Our firm profiles emphasize capabilities relevant to strategic decision-making:
- SGS leverages a global field-force and cross-sector inspection expertise to offer broad DPI coverage for electronics, automotive, and consumer goods.
- Bureau Veritas and Intertek pair traditional on-site services with supplier-audit portfolios to capture upstream quality-control spend across large supply chains.
- The TÜV network (Rheinland and SÜD) and DNV emphasize industrial-process monitoring and sector-specific process optimization — valuable to manufacturers in automotive, renewables, and heavy industry.
- Eurofins and UL extend DPI into regulated product testing lines (food, pharma, medical devices, and safety-critical appliances), offering integrated testing and inspection value propositions.
- Kiwa, Cotecna, Applus+, and LRQA serve differentiated geographic and vertical niches, often integrating laboratory testing, certification, and inspection services to deepen client relationships.
Across these players, our analysis finds a common strategic rhythm: investments in digital data capture, remote monitoring platforms, and analytics; geographic densification in high-volume production corridors; and selective partnership or bolt-on M&A to broaden service portfolios. Nevertheless, gaps persist around end-to-end digital assurance platforms that can meaningfully reduce on-site deployment costs while preserving the trustworthiness of inspection outcomes.
Market dynamics, regulations and workforce trends
Three structural dynamics will govern DPI market outcomes in 2026:
- Regulatory tightening. Standards such as ISO/IEC 17020:2012 set competency requirements for inspection bodies, and region-specific enforcement — exemplified by the EU Market Surveillance Regulation (EU) 2019/1020 — increases the compliance burden on manufacturers and importers. These frameworks elevate the strategic importance of accredited DPI providers who can demonstrate recognized processes and traceability.
- Automation and workforce transformation. Labor data indicate that median annual wages for quality-control inspectors were approximately USD 44,140 in May 2023, with projected employment declines due to automation over the coming decade. DPI providers and clients must plan for a transition where human inspection expertise is augmented — not instantly replaced — by digital sensing, image analytics, and remote supervision.
- Hybrid inspection models. The adoption of remote digital monitoring alongside targeted on-site verification is accelerating. This hybrid approach can reduce per-audit costs and enable higher-frequency oversight, but it requires robust standardization, secure data flows, and clear protocols for dispute resolution — all areas covered in our operational templates.
Risks and uncertainties
Key downside scenarios include slower-than-expected digital adoption (raising unit costs), geopolitical trade disruptions (altering demand geography), and inconsistent regulatory harmonization (creating compliance fragmentation). Conversely, upside drivers include accelerated reshoring in strategic sectors and increased regulatory enforcement that compels brands to institutionalize DPI as a core procurement practice.
Actionable recommendations for 2026
- For manufacturers and brands: Institute a layered DPI program where remote monitoring scales coverage and on-site DPI is reserved for critical control points. Use our sampling and escalation templates to convert quality objectives into measurable inspection protocols.
- For DPI service providers: Prioritize investment in secure remote capture and analytics, and develop standardized packages that permit faster procurement approvals from multinational buyers. Consider alliances with testing labs to offer one-stop assurance solutions.
- For investors and acquirers: Target assets that combine domain-specific inspection expertise with digital IP (data capture, compliance workflows, analytics) and a defensible inspector network in cost-effective production regions.
- For policymakers and regulators: Leverage accreditation frameworks to raise minimum competence thresholds and encourage interoperable data standards to support remote inspection integrity.
Methodology and call to action
The report’s estimates are denominated in USD (Revenue unit: Million) and derive from a synthesis of primary interviews, proprietary transaction and project databases, and bottom-up modeling of inspection demand by product flow and regulatory scenario. The base year is 2025, with a forecast horizon 2026–2032. Sensitivity testing is presented across conservative, base, and accelerated adoption cases within the full report.
If your 2026 planning requires a granular blueprint — including downloadable inspection-program templates, supplier procurement scorecards, and the proprietary regional and vertical segmentation tables excluded from this summary — access to the full report and the interactive data dashboard are available through our website. PW Consulting’s DPI market package is designed to convert market intelligence into executable decisions: supplier rationalization, technology investment prioritization, and M&A scouting for capability-led growth.
Contact PW Consulting to schedule a briefing and customized scenario run that aligns the report findings with your portfolio or operating footprint. In an environment where early detection and process-level assurance determine margin and reputation outcomes, the right DPI program is no longer an operational luxury — it is a strategic imperative for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide During Production Inspection (DPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com