

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Financial Services App Market to Soar to USD 400.84 Billion by 2032

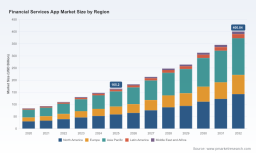
Worldwide Financial Services App Market — 2026 Strategic Preview
PW Consulting’s new market study, Worldwide Financial Services App Market (Base year 2025), reframes how senior executives should approach product strategy, vendor selection, and capital allocation for 2026 and beyond. The market has moved from an early-stage growth trajectory into a structural expansion phase: our topline model shows growth from USD 84.12 Billion in 2020 to USD 165.2 Billion in 2025, with the market projected to reach USD 400.84 Billion by 2032 under a 13.5% compound annual growth rate for the 2026–2032 forecast window. Those macro dynamics create a fertile but complex environment — large opportunity pools, accelerating technology convergence, and a layered regulatory and cost environment that demands disciplined choices.
Worldwide Financial Services App Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a pivot year for many banking and fintech strategies. With commercial pilots of tokenized deposits, stablecoin integrations, and real-time rails gaining traction, leadership teams must choose between first-mover experimentation and scaled, risk-managed rollouts.
Worldwide Financial Services App Market -
Architecture and cost trade-offs: Cloud-native, API-first designs are no longer optional. But the rising cost of infrastructure (including energy-driven data center pressure) alters vendor TCO and implementation sequencing; architecture choices made this year will lock-in multi-year cost exposure.
Worldwide Financial Services App Market -
Regulatory convergence: New rules on operational resilience, consumer-directed data portability, and data localization are reshaping product design and vendor contracts. Compliance is now a strategic capability with product, legal, and engineering implications.
-
Competition & partnerships: The landscape is a mosaic of consumer super apps, payment networks, merchant-focused processors, and core-banking platform vendors. Strategic partnerships and embedded-finance monetization models are turning distribution into a competitive moat.
What the report delivers — practical, actionable content
-
Topline market sizing and forward-looking scenarios to 2032, including upside/downside cases and sensitivity to key variables (real-time rails adoption, tokenization, BNPL penetration).
-
Vendor benchmarking and scorecards covering product functionality, integration friction, pricing models, and platform roadmaps — with an executive-ready shortlist for procurement.
-
Technology maturity maps and recommended reference architectures for three enterprise archetypes (incumbent bank, challenger fintech, and merchant platform), including implementation timelines and risk heatmaps.
-
Regulatory impact simulations for DORA-like resilience requirements, consumer data portability rules, and common data-localization regimes, translating regulation into program-level controls and budget implications.
-
Go-to-market playbooks: customer acquisition choreography, B2B2C partnership templates, pricing experiments for embedded finance, and monetization levers for apps and SDKs.
-
M&A and partnership screening tools: quantified templates to model tuck-in acquisitions, capability buys (fraud analytics, token custody, payments processing), and strategic alliances.
-
Operational toolkits: vendor RFP templates, migration checklists, SRE and incident-response playbooks aligned to new operational resilience rules, and energy-aware capacity planning models.
-
Proprietary regional and segment-level forecasts and datasets — note: the public summary intentionally omits granular segment splits to preserve our proprietary modeling. The full dataset and downloadable models are available on the report landing page.
Competitive landscape — patterns that matter
The competitive architecture of the market is best read as ensembles of capability rather than isolated competitors. Our analysis categorizes market participants into four strategic archetypes and highlights the implications for market players:
-
Consumer super apps and challenger banks (examples): pursuing embedded finance and share-of-wallet through broad product bundles. These players excel at engagement, rapid feature rollout, and cross-sell. Their strategic moves compress distribution margins and force incumbents to decide whether to compete, partner, or white-label.
-
Payment processors and merchant platforms (examples): offering SDKs, merchant enablement, and revenue-native integrations that make embedded payments a low-friction option for commerce platforms. These providers act as distribution multipliers and can rapidly convert transaction flow into financial services revenue.
-
Core banking and cloud platform vendors (examples): supplying the plumbing for banks and large institutions. Their focus is on reliability, regulatory alignment, and integration into legacy systems — they are the default choice for risk-averse institutions but must accelerate cloud-native innovation to defend against challenger velocity.
-
Networks and rails (examples): payment networks and clearinghouses that shape settlement economics and enable new product constructs like tokenized deposits and programmable payments. Adoption of these rails is a gating factor for product velocity and margin capture.
Market concentration remains modest: the top three providers account for roughly one-fifth of market value, and the top five for approximately one-third — a structure that favors continued vertical specialization and partnership-led expansion rather than outright domination by a single cluster. That fragmentation creates opportunities for targeted consolidation and capability acquisitions.
Near-term developments reshaping priorities
-
Fraud & risk: Advances in network-level intelligence for app fraud detection are reducing time-to-detection for coordinated attacks. Embedding these capabilities or partnering with specialized vendors should be considered a near-term priority.
-
Digital assets and tokenization: Leading institutions are piloting tokenized deposits and programmable stablecoins. Firms must develop custody, settlement, and compliance playbooks now, even if production rollouts are phased.
-
Real-time payments: Growth in RTP and account-to-account rails is changing settlement behavior and consumer expectations. Product roadmaps should incorporate instant settlement use cases where economics permit.
-
Infrastructure economics: Rising energy and data center costs are non-trivial drivers of TCO. Energy-aware cloud strategies and negotiating data-center rate protections should be part of vendor discussions.
Regulatory and operational headwinds — design principles
Regulation is not a checklist; it is a product constraint that shapes UX, data strategy, and vendor governance. Three regulatory trends to prioritize:
-
Operational resilience regimes (e.g., DORA) require demonstrable third-party governance, incident reporting, and testing cadences. Design for auditability and evidence collection from day one.
-
Consumer data portability rules shift control toward the user and mandate secure API-based data flows. Implement API-first consent frameworks and robust consent revocation mechanics.
-
Data sovereignty rules require localized processing in some jurisdictions — build geo-aware data partitioning and vendor substitution plans into your architecture to prevent costly rework.
Strategic priorities for leadership in 2026
-
Adopt a modular, API-first architecture: reduce time-to-market for new payment rails and tokenized instruments while keeping replacement costs manageable.
-
Prioritize fraud and network intelligence integration as a 90-day sprint; treat this as a business continuity and competitive capability.
-
Run controlled tokenization pilots with clear KPIs (liquidity, settlement times, regulatory readiness) before committing to full-scale deployments.
-
Embed energy and resilience metrics into vendor evaluations — ask for scenario TCOs that include regional data-rate sensitivities.
-
Develop an API partner playbook: map where to partner, where to build, and where to acquire. Use cohort-based experiments to validate the economics of embedded finance features.
-
Prepare a regulatory playbook that ties DORA-like controls, consumer data portability, and localization obligations to product release gates and procurement clauses.
-
Use M&A selectively to close capability gaps (e.g., fraud analytics, custody, SDK distribution) rather than blanket scale acquisitions; smaller, targeted buys can be more accretive in a fragmented market.
How PW Consulting helps — the unique value
This report is built for decision-makers who need executable guidance, not a high-level briefing. We combine an empirically-grounded market model (topline numbers and forecast curves) with vendor scorecards, architecture reference designs, and playbooks that map directly to procurement and product planning cycles. To preserve the integrity of our proprietary modeling, this public summary intentionally omits granular regional and segment splits; the full report includes those tables, downloadable models, and scenario drivers that finance and strategy teams can plug into 2026 planning decks.
For CXOs, heads of digital, and private equity teams evaluating strategic options this year, the core takeaway is simple: the opportunity is large and accelerating, but the path to value requires disciplined architecture decisions, early investment in resilience and fraud, and a pragmatic partner strategy that balances speed with regulatory control.
To access the full dataset, vendor benchmarks, and the downloadable scenario models, visit PW Consulting’s report page. Our analysts are available for bespoke briefings and enterprise workshops to translate the findings into 90/180/360 day action plans tailored to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Financial Services App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com