

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Control Automation Small PLC Market Poised to Grow at a 5.85% CAGR Through 2032

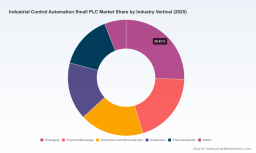
Worldwide Industrial Control Automation Small PLC Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence — the Worldwide Industrial Control Automation Small PLC Market report (base year 2025, forecast 2026–2032) — provides a strategic, actionable lens for executives preparing capital, product, and channel decisions in 2026. This preview outlines why small programmable logic controllers (PLCs) will remain a decisive battleground for manufacturers, systems integrators, and technology investors, and how our analysis translates into practical moves for the year ahead. While we demonstrate the analytical depth behind our conclusions, core segment-level tables and proprietary model outputs are intentionally withheld here to encourage direct access to the full report for competitive-grade data.
Worldwide Industrial Control Automation Small PLC Market
Market at a Glance: Growth Trajectory and Strategic Implications
The small PLC market is firmly in a growth phase. Our model positions 2025 as the reporting baseline and shows a steady compound annual growth rate (CAGR) of 5.85% through the forecast window. This trajectory reflects a market moving from basic machine control to increasingly networked, secure, and intelligent edge-control platforms. For 2026, the market is projected to build on the 2025 base, reinforcing demand for compact, modular, and integrated controllers across a broad set of machine and process automation projects.
Worldwide Industrial Control Automation Small PLC Market
For corporate strategists, this growth profile carries three immediate implications: (1) product roadmaps must shift from feature parity to integrated value (connectivity + cybersecurity + deterministic performance), (2) go‑to‑market channels must blend traditional distribution with software-enabled recurring revenue models, and (3) M&A or partnership activity should target niche technology stacks (motion, safety, EtherCAT/EtherNet/IP toolchains) and software services that unlock lifecycle revenues.
Worldwide Industrial Control Automation Small PLC Market
Why 2026 is a Pivotal Year
- Transition from Hardware to Systems Thinking: Customers increasingly evaluate small PLCs not as isolated controllers but as entry points into broader factory digitization. Decision criteria now prioritize cybersecurity features, built-in motion control, and seamless integration with cloud and edge analytics.
- Supply-chain Resilience and Component Trajectories: The industrial microcontroller supply base is evolving rapidly. Macro investments in semiconductor capacity and a decade-long uplift in industrial MCU demand support resilience, but short-term sourcing constraints and strategic onshoring initiatives mean procurement teams must qualify alternative suppliers and inventory strategies in 2026.
- Regulatory and Security Pressure: Recent advisories and security notifications have elevated firmware integrity, secure boot, and encrypted communications from ‘nice-to-have’ to contractual requirements. Procurement, product management, and services teams will face contracting clauses and compliance milestones in 2026 that directly affect supplier selection and product roadmaps.
What PW Consulting’s Report Delivers — Practical, Executable Content
This report goes beyond forecast charts. It is structured for immediate use by leaders setting 2026 priorities:
- Market Sizing & Scenario Models: A reproducible revenue model that lets teams stress-test outcomes under alternative adoption, pricing, and component-cost scenarios. (Note: our public summary intentionally omits the detailed segment-by-segment tables.)
- Vendor Playbooks: Comparative vendor profiles and go-to-market strategies that map product strengths to buyer personas and channel requirements, enabling rapid supplier short-lists for RFPs.
- Technology Adoption Roadmaps: Timelines and maturity curves for embedded communications, motion-control integration, and cybersecurity feature sets, aligned to buyer readiness and standards adoption.
- TCO and Lifecycle Cost Tools: Benchmarks and a configurable TCO framework for CapEx/OpEx trade-offs — including integration, maintenance, and firmware upgrade costs — designed for procurement and plant-automation owners.
- Risk & Resilience Assessments: Scenario-based risk matrices covering semiconductor supply disruptions, firmware vulnerabilities, and energy-efficiency regulation exposure, with mitigation playbooks tied to supplier capabilities.
- M&A and Partnership Screening: A curated checklist to identify niche entrants and software-enabled partners that accelerate service revenues, plus valuation heuristics based on product, installed base, and recurring software/service potential.
Competitive Landscape — Actionable Insights on Leading Suppliers
The small PLC market shows a healthy centralization: the top-tier vendors collectively control a substantial portion of revenue, with the leading three suppliers accounting for nearly half of market sales and the top five exceeding sixty percent. For 2026 planning, this concentration shapes strategy in two ways: established vendors will continue to leverage brand, channel scale, and ecosystem integrations, while mid‑tier and specialist vendors must compete on specialization, faster feature cycles, and tighter TCO alignment.
Key vendor dynamics captured in our analysis include:
- Siemens AG: Continues to push compact‑PLC performance and integration, with recent product launches and iterations that double logic density and harden security primitives. Siemens’ emphasis on scalable families and developer ecosystems makes it a default choice for customers prioritizing long-term platform continuity.
- Rockwell Automation (Allen‑Bradley): Focused on localized smart machine controllers with strong footprints in certain regional OEM ecosystems. Recent micro‑controller expansions emphasize simplified integration and connectivity, positioning Rockwell for smart machine OEM upgrades.
- Mitsubishi Electric & Schneider Electric: Both vendors have refreshed compact families to emphasize motion control and industry-protocol support, but they now also face intense scrutiny on firmware security postures as advisories and regulatory expectations rise.
- Beckhoff, Omron, ABB, and Niche Players: These vendors differentiate through PC‑based control, EtherCAT and high‑performance motion, or integrated HMI solutions. Their agility makes them preferred partners for specialized OEMs and integration-led projects.
- Smaller OEMs (Delta, WAGO, Unitronics, etc.): Continue to win on price-performance, vertical specialization, and tighter service bundling — particularly where rapid deployment or cost sensitivity is primary.
Our vendor matrices include readiness indices for cybersecurity, edge analytics, motion control, and channel support, allowing clients to map supplier capabilities against their 2026 sourcing criteria.
Market Dynamics: Supply, Security, and Sustainability
- Semiconductor Context: The industrial microcontroller market is expanding rapidly, supporting higher integration of compute and connectivity into small PLCs. Global chip investments are underpinning supply resilience over the medium term, but executives should budget for episodic price and lead‑time volatility in 2026.
- Cybersecurity Requirements: Recent advisories affecting multiple PLC families have forced a re‑calibration of product specifications. Secure boot, firmware verification, and encrypted telemetry are fast becoming procurement gatekeepers. For 2026, buyers should require demonstrable patching cadences and supply-chain transparency when qualifying controllers.
- Labor & Productivity Pressures: Labor shortages and the drive for human-centric automation continue to push adoption of compact automation solutions. This trend favors controllers that simplify integration with predictive maintenance and energy-optimization suites.
- Energy and Sustainability Mandates: Regulatory focus on factory-level energy efficiency is accelerating demand for controllers with integrated power-management and motor-control features. Product roadmaps that embed energy metering and closed-loop efficiency controls will capture premium opportunities.
How to Use This Report in 2026 Decision Cycles
Companies who will extract the most value from the report are those that integrate its outputs directly into 2026 decision cycles:
- Procurement & Sourcing: Use the TCO tools and vendor readiness indices to structure multi-year contracts, negotiate service-level agreements for firmware security, and design alternative sourcing strategies for critical MCUs.
- R&D & Product Management: Align product investment to the highlighted feature roadmaps — prioritize secure boot, embedded motion, and industrial communications stacks that reduce integration time for OEM customers.
- Corporate Development: Apply our M&A screening criteria to identify tuck-in targets that expand installed base or software capabilities, accelerating transition from one‑time hardware sales to recurring software/service revenues.
- System Integrators & Channel Partners: Tailor service portfolios to include managed firmware updates, cybersecurity health checks, and retrofit pathways that lower barriers to adoption for legacy systems.
Why PW Consulting’s Analysis Matters
PW Consulting blends quantitative market modeling with vendor and technology diligence to generate recommendations that are both strategic and executable. Our multi‑scenario market model captures baseline growth (the market’s mid-single-digit CAGR through the forecast), while our qualitative analysis connects macro drivers — semiconductor investments, regulatory shifts, and labor trends — to supplier strategies and buyer needs. This synthesis produces playbooks that procurement, product, and corporate development teams can operationalize in 2026.
Next Steps — Accessing the Full Intelligence
This preview demonstrates the analytical pillars and strategic takeaways that underlie our full Worldwide Industrial Control Automation Small PLC Market report. To access the complete dataset, segmentation tables, vendor scorecards, scenario models, and interactive decision tools — all necessary for high-stakes 2026 planning — please visit the report landing page for PW Consulting. The full report contains the granular data, regional and end‑use splits, and downloadable modeling assets that we have intentionally withheld from this public summary to protect proprietary methodologies and client value.
For bespoke briefings, model extracts, or tailored workshops that adapt the report’s outputs to your specific 2026 use cases (procurement RFx support, M&A diligence, product-roadmap prioritization), PW Consulting’s strategy team is available to partner on an accelerated engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Control Automation Small PLC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com