

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Vorinostat Market Highly Concentrated — Top 3 Firms Command 82.4% Share, New Report Reveals

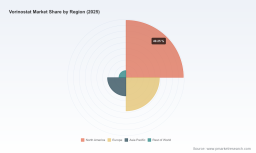
Worldwide Vorinostat Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting is pleased to announce the release of our latest market research briefing: Worldwide Vorinostat Market. Built on a rigorous historical audit (2020–2025) and a forward-looking model covering 2026–2032, this study translates complex therapeutic, regulatory, and commercial dynamics into actionable recommendations for executives, investors, and policy-makers planning for 2026 and beyond.
Worldwide Vorinostat Market
Executive snapshot
Our top-line forecast identifies sustained, moderate growth in the global vorinostat market. The addressable market expanded from the early-2020s baseline and reached an estimated USD 216.2 Million (base year 2025); PW Consulting’s proprietary scenario modelling projects expansion to roughly USD 312.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.4% across the 2026–2032 forecast horizon.
Worldwide Vorinostat Market
Two structural characteristics are immediately material to strategic planning: a high degree of market concentration and a mature originator-to-generic lifecycle. Our concentration analysis shows that the top three players control the lion’s share of commercial activity (CR3 approximately 82.4%), and the top five command an even larger portion (CR5 approximately 88.5%). These metrics shape bargaining power across the value chain — from procurement and tendering to reimbursement and pricing negotiations.
Worldwide Vorinostat Market
Why this report matters for 2026 decisions
- Timing and prioritization of market entry: The market’s trajectory is defined less by explosive demand and more by regulatory access, formulary positioning, and generic competition. For companies evaluating manufacturing scale-up, licensing, or geographic expansion in 2026, understanding the nuanced timing of opportunity windows (e.g., tenders, guideline updates, and payer formulary cycles) is essential.
- Lifecycle and portfolio strategy: Vorinostat’s transition from originator exclusivity to a generics-dominated environment is instructive for portfolio managers. Decisions around indication expansion, combination-development, and patent strategy should be informed by the expected deceleration of price-led growth and the relative resilience of niche clinical usage.
- Regulatory and safety constraints: The drug’s safety profile and labelled monitoring requirements materially influence utilization patterns. Reimbursement strategies and hospital adoption will hinge on clear protocols for risk mitigation and real-world evidence that demonstrates manageable safety outcomes.
- Value capture for suppliers and service providers: Given the market’s concentration, suppliers that can guarantee quality, supply continuity, and cost-optimized manufacturing will secure privileged access to tenders and long-term contracts.
What’s inside the report — practical intelligence, not platitudes
PW Consulting’s Worldwide Vorinostat Market report is designed to be operationally useful. Highlights include:
- Proprietary market model: Monthly and annual demand and revenue modeling through 2032, sensitivity-tested against regulatory, pricing, and adoption scenarios.
- Historical audit (2020–2025): Volume and revenue backcast that reconciles disparate public and private sources, enabling robust baseline assumptions for forecasting.
- Regulatory and guideline mapping: Chronology and impact assessment of pivotal approvals, guideline inclusions, and post-marketing safety advisories that shape clinical adoption.
- Competitive playbook: Strategic profiles and capability assessments for originator and major generic players, covering manufacturing footprint, registration strategy, pricing behavior, and commercial reach.
- Commercial levers and payer intelligence: Reimbursement levers, formulary risk scenarios, tender dynamics, and recommendations for market access teams to protect and grow revenue.
- Scenario and sensitivity analysis: Three distinct demand scenarios (baseline, conservative downside, strategic upside) with clear triggers and contingency actions for each.
- M&A and partnership opportunities: Identification of target archetypes, valuation heuristics, and integration risks for buyers considering inorganic expansion.
- Data annexes and methodology: Source-by-source reconciliation tables, modelling assumptions, and an interactive model available upon request for licensed subscribers.
To preserve competitive value for our subscribers, the public briefing intentionally omits granular regional, type, and application-level tables. The full report contains those detailed splits and downloadable datasets — access information is summarized at the end of this release.
Competitive landscape — concentrated, with defined strategic trajectories
Vorinostat’s commercial history is shaped by a classic originator-to-generic transition. The originator established clinical precedence and guideline presence, while generic entrants expanded access and put pricing pressure on market rates.
- Originator dynamics: The original developer established the therapeutic benchmark and continues to shape guideline-based utilization through legacy relationships with centers of excellence. Their role now emphasizes lifecycle management, indication defense, and evidence generation in subpopulations to preserve premium segments.
- Generics and global supply: Generic manufacturers have become the primary route to broaden geographic access and cost-effective supply. These firms pursue parallel strategies: regulatory-first expansion into large tender markets, cost-optimized manufacturing footprint consolidation, and aggressive pricing aligned with public procurement frameworks.
- Recent commercial catalysts: Notable market events in recent years — such as generic launches in major European markets and regulatory approvals enabling substitution in large healthcare systems — have compressed margins but expanded overall patient access. Such milestones materially influence near-term tender dynamics and forecasted uptake rates.
For executives considering partnerships or competitive responses, the report provides a playbook for three common strategic postures: defend (originator-focused), scale (large-volume generics), and differentiate (niche formulations or service-enabled offerings). Each posture includes stepwise actions, estimated investment horizons, and break-even sensitivities.
Regulatory and clinical context: constraints and enablers
Regulatory history and clinical guideline positioning remain critical. The therapy’s initial accelerated approval established a clinical foothold many years ago; subsequent patent expirations opened the market to multiple manufacturers. Continued inclusion in clinical guidelines for certain patient populations sustains baseline demand, while labeled safety warnings necessitate structured monitoring — both factors that buyers, payers, and hospital pharmacy directors weigh when making formulary and procurement decisions.
Strategic implications and recommended actions for 2026
- For pharmaceutical originators: Prioritize evidence generation that defends premium clinical niches (e.g., combination therapy studies, biomarker-directed subgroups) and structure differentiated services (e.g., patient monitoring support) that justify a price premium.
- For generic manufacturers: Invest in supply reliability, quality certifications, and strategic regulatory filings in high-volume public procurement markets. Use targeted commercial partnerships to accelerate uptake where tender rules favor local or prequalified suppliers.
- For investors and M&A teams: Valuation should reflect the interplay of concentration and commoditization. Targets with validated manufacturing capacity, regulatory dossiers in priority markets, and existing tender relationships present the most defensible value.
- For payers and health systems: Implement protocols that balance cost containment with patient safety — structured monitor-and-treat pathways reduce adverse events and can improve total cost-of-care metrics.
- For clinical leaders: Prioritize standardized monitoring and thrombosis prophylaxis protocols to mitigate safety risks and enable broader, guideline-concordant use where clinically appropriate.
How PW Consulting supports your 2026 planning
Clients who license the full Worldwide Vorinostat Market report gain:
- Access to the complete regional, type, and application splits behind our headline numbers (downloadable tables and pivot-enabled spreadsheets).
- Customizable model instances for bespoke scenario work and M&A valuation support.
- Workshops with our analysts to translate report findings into a 90-day commercial action plan aligned to your organization’s strategic posture.
Next steps — obtaining the full intelligence
This briefing is intentionally selective: it demonstrates the analytical depth and strategic framing PW Consulting applies, while preserving the detailed segmentation and datasets for licensed subscribers. To obtain the complete report package — including granular regional and application-level tables, the full competitive database, and an interactive model — please visit our report page or contact our commercial team. The full dataset is essential for precise budgeting, tender bidding, and M&A valuation work in 2026.
PW Consulting’s analysts remain available to brief executive teams and to run tailored scenario sessions that translate these insights into executable plans. Our market modelling and practitioner-focused recommendations are designed to shorten decision cycles and reduce execution risk as organizations position themselves in a market characterized by moderate growth, high concentration, and ongoing therapeutic and regulatory complexity.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com