

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Rail Components Market to Surge to USD 99.6 Billion by 2032

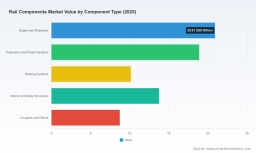
Worldwide Rail Components Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an executive preview of our forthcoming Worldwide Rail Components Market report (base year 2025, forecast 2026–2032). As transport operators, component manufacturers, investors and procurement leaders set priorities for 2026, this analysis synthesizes an extensive quantitative model and primary research to translate market momentum into actionable choices. The global market reached approximately USD 72.45 billion in 2025 and is projected to expand to roughly USD 79.5 billion in 2026, continuing along a medium-term trajectory that averages a 4.65% compound annual growth rate over the forecast window. Behind this headline trajectory lie material short-term oscillations and structural inflections that will define winners and laggards in the coming 18–36 months.
Worldwide Rail Components Market
Why this report matters for 2026 decision‑makers
- Capital allocation: prioritize capex across electrification, signaling, and aftermarket components based on near-term demand peaks and medium‑term secular growth.
- Procurement & supply‑chain resilience: quantify exposure to raw material volatility and policy-driven tariff risk, and design hedging and dual-sourcing playbooks.
- M&A and partnership strategy: identify capability gaps (e.g., automation, traction electronics, premium rails) where acquisitions or joint ventures accelerate time‑to‑market.
- Product & technology roadmaps: align R&D and product launches to regulatory inflections (signaling baselines, PTC/CBAM) and operator modernization cycles.
- Commercial models: evolve from product sales to outcome-based contracts and digital services to capture aftermarket growth and margin expansion.
What’s inside the report (practical deliverables)
- Top‑down and bottom‑up market sizing (historical 2020–2025 and forward 2026–2032), with scenario envelopes and sensitivity tables that let you stress-test assumptions at +/- key variables.
- Component and train‑type segmentation frameworks and a decision matrix for prioritizing investments by strategic impact (note: this preview intentionally withholds detailed segment-level figures to preserve the full report’s value).
- Supply‑chain heatmaps and raw‑material cost‑to‑value models for steel, copper, and electronics subsegments, including contingency actions for price shocks.
- Regulatory impact assessment (E.U., U.S., and select emerging markets) with implementation timelines and compliance cost estimates.
- Competitive benchmark scorecards covering manufacturing footprint, product breadth, digital capabilities, M&A posture and service monetization potential.
- Deal database and strategic options for acquirers, investors and OEMs, with valuation frameworks tailored to rail‑component cash flows.
- Actionable procurement playbooks and negotiation levers for 2026 contracts, including suggested contract clauses for volatility sharing and lifecycle pricing.
Market dynamics: what the headline numbers conceal
The aggregate market path from 2020 through 2025 shows recovery and expansion following pandemic disruption, culminating at about USD 72.45 billion in 2025. Our model anticipates a step up to approximately USD 79.5 billion in 2026, driven by a mix of fleet renewals, signaling upgrades and renewed freight investments. The 4.65% CAGR that underlies the 2026–2032 forecast is a useful compass, but beneath it are demand pulses tied to regulatory implementation, project-by-project spending and raw-material cycles. Notably, short-term dips and rebounds are visible in our year-by-year scenario set; these reflect common real-world dynamics where project phasing and regional policy shifts create lumpy procurement calendars.
Worldwide Rail Components Market
Supply‑side constraints and raw‑material pressures
Manufacturers and buyers should treat raw‑material and energy costs as first‑order risks. Recent industry intelligence shows significant upward pressure on rail-grade steels and related inputs driven by energy prices and capacity tightness. In Europe, premium rail‑steel pricing and energy cost pass-throughs have already pressured margins. Compounding this, the European Carbon Border Adjustment Mechanism (CBAM) introduces additional tariff exposure on embedded carbon from 2026, reshaping sourcing economics for imported steel products. Bainitic and other advanced metallurgy segments are seeing faster growth in demand for high‑speed and heavy‑haul applications, further tightening specialized supply. Our report provides procurement hedging templates and supplier segmentation that let buyers quantify landed cost impacts under multiple tariff and price scenarios.
Worldwide Rail Components Market
Regulation and technology inflection points
Regulatory timelines are compressing modernization windows. In Europe, recent TSI updates mandate upgraded signaling baselines for new deployments, while in the U.S. interoperability requirements for Positive Train Control are moving to a higher standard. These mandates create near-term replacement cycles for wayside and onboard signaling equipment and accelerate demand for compatible subsystems. On the technology front, autonomous operation platforms, real‑time fleet optimization and predictive maintenance software are shifting value away from purely mechanical components toward software-enabled subsystems and lifecycle services. Leaders who pair hardware roadmaps with clearly monetized digital offers will capture outsized aftermarket value.
Competitive landscape: strategic positioning of core firms
The rail components market is moderately concentrated: the top three firms account for a substantial share of the industry value pool, with the top five controlling a majority. Within that competitive set, corporate strategies diverge across three vectors — system integrators expanding services and signaling, traditional mechanical suppliers consolidating scale and materials expertise, and regional OEMs protecting local content and price competitiveness.
- Alstom (Saint‑Ouen, France) — Strengths: broad bogie and braking portfolio and deep operator relationships. Strategic focus: local partnerships and indigenization efforts in large growth markets.
- Siemens Mobility (Munich, Germany) — Strengths: electrification, signaling and automation. Strategic focus: automation platforms; recent GoA4 product introductions underscore a push into driverless systems.
- Wabtec Corporation (Pittsburgh, USA) — Strengths: freight locomotives, braking, and digital fleet solutions. Strategic focus: digital optimization contracts and long‑term service agreements.
- Knorr‑Bremse (Munich, Germany) — Strengths: braking and HVAC systems. Strategic focus: bolt‑on acquisitions to expand compact brake technologies.
- voestalpine Railway Systems (Zeltweg, Austria) — Strengths: rails and fastening systems. Strategic focus: premium rail certifications and heavy‑haul specifications.
- Thales (Meudon, France) — Strengths: signaling and security. Strategic focus: integrated onboard/wayside systems for urban and mainline networks.
- CRRC (Beijing, China) — Strengths: scale in wheels, axles and propulsion. Strategic focus: high‑speed and heavy freight platforms with competitive pricing.
- Hitachi Rail (London, UK) — Strengths: traction and digital signaling. Strategic focus: integrated traction-to-service solutions for regional and high‑speed markets.
- Additional players (Lucchini RS, Greenbrier, Trinity, Titagarh Rail Systems, Stadler Rail, Nippon Steel, ArcelorMittal Rails & Accessories) act as critical suppliers and regional challengers—each brings differentiators in metallurgy, freight car assemblies, or localized manufacturing footprints.
Recent corporate developments illustrate strategic tilts: product launches in automation, selective acquisitions to fill product gaps, certifications that unlock regional heavy‑haul contracts, and large fleet software agreements. These moves foreshadow intensified competition around systems integration and aftermarket services.
Strategic implications and recommended 2026 actions
- Operationalize scenario planning now: embed tariff, steel‑price and regulatory scenarios into your 12–24 month procurement cycle models; update contract templates to include pass‑through and force‑majeure clauses tied to material cost indices.
- Prioritize aftermarket and software monetization: invest in telematics, predictive maintenance and outcome‑based contracting pilots to convert hardware sales into recurring revenue.
- Targeted M&A and partnerships: focus acquisitions on digital fleet management, compact braking technologies and localized manufacturing to mitigate CBAM/tariff exposure.
- Segment supplier base by strategic importance: secure long‑lead items (specialty steels, wheelsets) with multi-year agreements while maintaining tactical flexibility for commoditized procurements.
- Accelerate regulatory compliance roadmaps: certify products to the newest signaling baselines and PTC standards ahead of mandatory deadlines to capture retrofit and replacement opportunities.
How PW Consulting’s report delivers decision advantage
Our full report translates the headline growth story into executable workstreams with templates, vendor scorecards and a prioritized 90‑day agenda for executives preparing 2026 budgets and bids. It is designed not as an academic exercise but as a practitioner’s toolkit: detailed forecast tables, sensitivity models, supplier risk heatmaps and M&A playbooks that can be immediately deployed in commercial planning cycles.
This preview intentionally omits the granular segment and regional tables that are essential for transaction diligence and procurement negotiation. Those detailed splits, unit‑price models and supplier scorecards are available in the complete publication and accompanying advisory packages.
For access to the full Worldwide Rail Components Market report, the supplier benchmarking database and PW Consulting’s tailored advisory engagements to translate insights into 2026 action plans, visit our official report page or contact PW Consulting’s Rail Practice. Equip your team with the scenario‑tested intelligence needed to convert the next wave of rail modernization into sustainable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com