

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Machine Tool Control Transformer Market Reaches USD 896.84 Million in 2025, Poised for 4.6% CAGR from 2026–2032

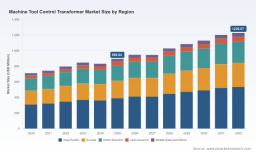
Worldwide Machine Tool Control Transformer Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Machine Tool Control Transformer market provides decision-grade intelligence for executives planning capital allocation, procurement, and M&A activity in 2026. Built on a 2020–2025 historical series and a 2026–2032 forecast horizon, the report quantifies the addressable market in USD Million, projects a steady recovery and expansion trajectory through 2032, and distills the commercial and technical dynamics that will determine winners in the next strategic cycle.
Worldwide Machine Tool Control Transformer Market
Market trajectory and headline metrics
After a recovery from mid-decade headwinds, the market size in our base year (2025) stands at an estimated USD Million-level figure reflecting the cumulative activity across machine-tool OEMs, captive machine shops, and aftermarket service providers. PW Consulting’s forecast models indicate a compound annual growth rate (CAGR) of 4.6% across the 2026–2032 forecast window, driving the market to materially higher levels by 2032 driven by steady electrification, incremental automation retrofits, and replacement demand for dry-type control transformers in industrial controls.
Worldwide Machine Tool Control Transformer Market
Two structural observations underpin the numbers: first, demand is driven by a combination of greenfield machine-tool production and a larger-than-commonly-appreciated aftermarket replacement cycle; second, profitability and investment calculus for suppliers are being reshaped by input-cost volatility and concentrated pockets of demand that favor nimble, vertically integrated players.
Worldwide Machine Tool Control Transformer Market
Key dynamics shaping procurement and investment decisions in 2026
- Raw-material cost shock and implications:
Supply-side shocks through late 2025 and into 2026 have materially increased the price volatility profile for copper and electrical steel—two cost drivers that dominate transformer bill-of-materials. Copper experienced an intraday peak in January 2026 that exceeded USD 14,500 per tonne, and consensus pricing for 2026 is elevated relative to historical averages. Electrical steel prices have also risen significantly since 2020, roughly doubling in many supply chains, creating upward production-cost pressure. These movements alter quoting discipline, working-capital requirements, and the feasibility of thin-margin product segments.
- Regulatory context and product scope:
Regulatory nuance matters. Recent U.S. Department of Energy (DOE) rulemaking explicitly leaves machine-tool (control) transformers outside the scope of new distribution-transformer energy-efficiency standards, and some regional codes mirror similar exemptions. For example, specific state-level codes have carved out machine-tool control transformers from low-voltage dry-type certification requirements. This creates a tactical advantage for suppliers that can optimize designs for factory-floor robustness without being constrained by distribution-transformer efficiency labeling—but it also raises reputational and procurement considerations for OEMs pursuing broader sustainability commitments.
- Demand composition—OEM vs aftermarket:
Replacement and aftermarket service remains a meaningful and growing part of the market. Longer machine lifecycles and increasing installed-base intelligence create differentiated opportunities for suppliers that pair hardware with aftermarket services, warranty extensions, and retrofit engineering.
- Concentration and competitive structure:
The market demonstrates moderate concentration: our competitive analysis shows that the top three suppliers account for roughly one-third of market revenues (CR3 ~32.45%), while the top five reach under half (CR5 ~46.12%). This structure enables both regional champions and specialist vendors to coexist, but it also implies that scale advantages in supply chain management and certification footprint become critical for meaningful growth beyond niche segments.
Competitive landscape — what we learned from supplier profiles
PW Consulting’s company-level review focuses on the practical differentiators that matter to procurement and product strategy leaders: inrush-handling capability, custom-engineering depth, compliance with international standards, lead-time resilience, and aftermarket service models.
- Hammond Power Solutions (HPS)
HPS is a North American dry-type leader with a portfolio optimized for high-inrush environments typical of machine tools, conveyors, and robotics. Their molded Imperator series and legacy molded styles remain relevant where installations require compact footprints and sustained inrush performance.
- MCI Transformer Corporation
MCI’s strength is a catalog-plus-custom model aimed at regulated industrial applications that require strict adherence to control-voltage safety norms. For buyers with compliance-driven sourcing, MCI’s track record in delivering custom variants is a notable mitigant to project execution risk.
- Controlled Magnetics
Positioned as a custom-engineering specialist, Controlled Magnetics spans a wide VA range and emphasizes ANSI/NEMA and UL/CSA compliance—attributes that appeal to automation integrators and OEMs specifying robust isolation and inrush handling.
- SNC Manufacturing (Allient)
Under Allient ownership, SNC’s single- and three-phase control transformer business signals consolidation trends among U.S. boutique manufacturers. Buyers should monitor integration outcomes for indications of improved scale and distribution reach.
- North American and European specialists (Micron, PowerVolt, Murrelektronik, Boardman, SolaHD)
These suppliers combine certified, UL/CSA-listed products with targeted offerings for machine-tool panels and special-mount applications. Their value sits at the intersection of catalog availability and dependable safety certification.
- Asia-based manufacturers (Lushan, ZHENGXI, CNC Electric Group)
Chinese producers expand global sourcing options with competitive pricing and local engineering support in key export markets. Their technology lineage and product series designed for CNC and automation panels present both opportunity and procurement risk depending on supply-chain transparency and compliance documentation.
Report deliverables — what’s inside (practical, execution-focused)
The study is built to be directly actionable for C-suite and business-unit leaders. Core deliverables include:
- Market sizing and validated forecast model (2020–2032) with scenario toggles for raw-material trajectories and demand shocks;
- Supplier scorecards and comparator matrices focused on lead times, certification footprint, inrush-handling performance, and aftermarket capabilities;
- Procurement playbook with supplier segmentation, sourcing decision trees, and a recommended hedging approach for copper and electrical steel exposure;
- M&A and partnership diligence templates emphasizing integration levers (manufacturing footprint, customs compliance, and digital service layers);
- Product roadmaps and engineering trade-off sheets that help R&D prioritize lower-copper designs, higher-efficiency cores, and modular offerings for retrofits;
- Regulatory matrix summarizing global exemptions, regional certification pathways, and compliance-related competitiveness implications;
- Scenario-based P&L sensitivity analysis showing margin impacts under multiple input-cost and pricing pathways.
Strategic implications for 2026 — recommended actions
For executives making strategic choices in 2026, the combination of steady market growth and elevated input-cost risk demands a balanced set of initiatives across procurement, product engineering, and commercial strategy:
- Implement a layered raw-material hedging and supplier diversification strategy. Blend long-term contracts with strategic spot purchases and consider vertical partnerships with coil and copper suppliers to stabilize input costs.
- Prioritize supplier scorecards that explicitly weight inrush performance, customization lead time, and documentation readiness for cross-border compliance; these factors now drive time-to-market more than unit price alone.
- Invest in modular, lower-copper designs and alternative core technologies where lifecycle economics favor slightly higher upfront R&D in exchange for lower commodity exposure through the product life.
- Monetize aftermarket service and retrofit offerings. Warranty-extension bundles, predictive maintenance, and rapid-replacement programs increase lifetime value and help blunt cyclical new-equipment slumps.
- Use M&A selectively to fill capability gaps—especially in regional manufacturing or certification expertise—rather than to chase scale alone. Integration must prioritize supply-chain resilience and engineering IP consolidation.
- Monitor regulatory developments; the current exclusion of machine-tool control transformers from certain distribution-transformer efficiency mandates offers operational flexibility, but reputational and voluntary-efficiency requirements may change buyer expectations.
Risk scenarios and monitoring checklist
- Commodity price shock: sustained copper and electrical steel price spikes could compress supplier margins and force industry-wide price resets—monitor forward curves and producer inventory levels.
- Trade and tariff shifts: evolving trade policies could make regional sourcing advantages swing quickly—run alternate supply scenarios for near-shoring and multi-sourcing.
- Standards evolution: accelerated voluntary efficiency labeling from major OEMs or procurement coalitions could create a de facto standard even where regulatory scope remains narrow.
- Consolidation outcomes: successful integration of small specialized players under larger groups could accelerate professionalized aftermarket services and OEM partnerships, altering bargaining dynamics.
Why this preview — and next steps
This article provides a strategic preview: it surfaces the market trajectory, competitive contours, and practical decision levers executives must consider in 2026. To preserve the tactical value for active sourcing, procurement negotiations, and M&A diligence, PW Consulting intentionally excludes detailed regional and application-level split tables from this preview. The full report contains the complete segmented datasets, supplier-by-supplier scorecards, and interactive forecast models that allow executives to run custom scenarios against their own cost-of-capital and commodity assumptions.
For operational teams preparing 2026 budgets or for investors assessing targets in the machine-tool control transformer value chain, accessing the full PW Consulting report is the recommended next step: it converts the directional intelligence in this preview into executable plans, procurement clauses, and integration checklists tailored to your company’s risk appetite.
Access and contact
PW Consulting’s Worldwide Machine Tool Control Transformer Market report is available now. For licensing, bespoke scenario runs, or to commission a tailored supplier due-diligence package, contact PW Consulting’s Industry Advisory Services. The full dataset and supplier appendices are available to licensed subscribers and will materially shorten decision cycles for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Machine Tool Control Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com