

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Environmentally Friendly Gas‑Insulated Switchgear Market Poised to Expand at an 8.15% CAGR, Powering a Cleaner Grid

Worldwide Environmentally Friendly Gas Insulated Switchgear Market — Strategic Outlook for 2026 Decision-Makers
As energy systems accelerate decarbonization and grid operators confront tightened greenhouse gas rules, environmentally friendly gas insulated switchgear (GIS) has moved from niche innovation to boardroom imperative. PW Consulting’s latest market intelligence briefing synthesizes commercial deployments, regulatory inflection points, supplier strategies and technology economics to equip corporate leaders with a clear, actionable view of the opportunity and risk window opening in 2026.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Market Trajectory at a Glance
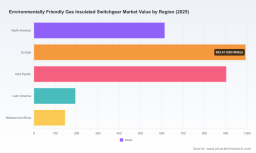
Our macro analysis positions the worldwide environmentally friendly GIS market on a robust growth trajectory. The market expanded steadily in the early 2020s and reached an estimated USD 2,850 Million in the base year 2025. Looking forward, PW Consulting’s conservative-leaning forecast projects continued expansion through the 2026–2032 horizon, with a compound annual growth rate of approximately 8.15% and a multi-year market value approaching USD 4.9 billion by 2032 under the central scenario.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
These headline figures capture the transition dynamics in both transmission and distribution networks: accelerated replacement of SF6-based assets, rising public-sector pilot funding, and increasing commercial traction for SF6-free alternatives across voltage classes. The topline growth conceals meaningful heterogeneity by geography, voltage class and technology choice — nuances that are central to execution but intentionally summarized here to preserve the strategic value of the full report.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Why 2026 Is a Strategic Inflection Point
- Regulatory deadlines compress procurement timelines. The implementation schedule of major regulatory actions — notably the EU’s updated F-Gas rules that restrict SF6 use in new medium-voltage switchgear from 2026 — creates a hard stop for legacy procurement strategies in many jurisdictions. Parallel actions, such as the US HFC phasedown under the AIM Act, reshape the availability and economics of gas alternatives.
- Commercial deployments are maturing. Large-scale, high-voltage projects that were pilots through 2023–2024 are moving into commissioning and mainstream production, validating certain alternatives at scale. This alters risk assessments for utilities and transmission developers moving into multi-year CapEx cycles.
- Policy and funding are accelerating technology adoption. Public funding programs targeting SF6-free grid technologies lower the effective cost of early deployments and de-risk supplier selection for progressive utilities, creating pockets of accelerated demand.
Competitive Landscape — Leaders, Strategies and Momentum
The market exhibits moderate concentration: a small set of incumbents command a significant share of commercial deployments and intellectual property, but competitive pressure is increasing from traditional OEMs and regional players. PW Consulting’s assessment of the competitive field finds that three- to five-firm groups control a material portion of global supply chains and manufacturing capacity, which has direct implications for pricing, lead times and strategic partnerships.
- GE Vernova (USA) — Pushing g3 (3M Novec 4710 + CO2) at transmission voltage levels, including high-voltage installations up to 550 kV. Recent commissioning of large-scale 420 kV g3 projects signals commercial maturity and supply-chain readiness for high-capacity deployments.
- Siemens Energy (Germany) — Advancing a Clean Air / Blue GIS portfolio that leverages fluorine-free synthetic air solutions for substations up to medium-high transmission voltages. The company’s order wins in Europe underscore both performance acceptance and competitive pricing dynamics.
- Hitachi Energy (Switzerland) — Scaling its EconiQ lineup with fluoroketone-based AirPlus solutions across a broad voltage range; successful grid connections in European systems demonstrate interoperability and commissioning experience.
- ABB (Switzerland) — Updating its Eco-efficient GIS catalog with certified AirPlus modules for higher voltage ratings, signaling continued investment in modular product stacks to meet tightened environmental standards.
- Schneider Electric (France) , Mitsubishi Electric (Japan) and Toshiba Energy Systems & Solutions (Japan) — Each maintains differentiated routes to SF6-reduction via vacuum interrupters, solid insulation, or natural-origin gas mixes, often focused on distribution-level and regional grid projects.
Recent vendor milestones — largest high-voltage g3 commissioning, major Blue GIS orders for grid interconnection projects, and field connections of EconiQ systems to national transmission operators — confirm that multiple technology pathways can achieve commercial scale. However, that does not eliminate variation in cost, supply-chain resilience, and engineering integration effort across vendors and technologies.
Economic & Supply Considerations That Will Drive Sourcing Choices
- Component and gas economics matter. Alternative dielectric gases used in SF6-free solutions have different cost profiles and supply dynamics. For example, fluoronitrile compounds used in some g3 mixes have non-trivial unit prices in industrial bulk supply; volatile raw-material markets can therefore transmit materially into project level CapEx. PW Consulting models include sensitivity scenarios for raw material prices and availability.
- Installation and lifecycle cost differentials are real. Eco-friendly GIS units commonly carry a modest premium relative to SF6 equivalents, due to gas technology, sealing and conversion engineering. That premium may be offset over asset life by regulatory compliance value, future retrofit avoidance costs, insurance and lower environmental liabilities — effects that need quantified scenario analysis for each procurement decision.
- Concentration and manufacturing lead times require advanced planning. A moderately concentrated supplier landscape for specialized high-voltage GIS means lead times and contractual terms become a gating factor for major projects. Early supplier engagement and contract features to manage delivery risk will be central to execution readiness in 2026.
Practical Strategic Recommendations for 2026
- Adopt a dual-track procurement strategy. Separate immediate compliance-driven replacements from long-lead strategic projects. For near-term necessities, prefer commercially proven solutions with field-validated interoperability. For long-lead investments, negotiate options that allow technology migration as standards solidify.
- Run three-tier scenario modeling. Use base, accelerated-adoption and constrained-supply scenarios to stress-test capital plans. Factor in regulatory shocks and gas-price swings to identify break-even points for SF6-free adoption vs. retrofit deferral.
- Embed supplier scorecards in RFPs. Evaluate vendors not only on technical specs but on manufacturing capacity, raw-material sourcing transparency, warranty and end-of-life management. Scorecards should include commissioning track record, field performance data and IP dependencies.
- Prioritize interoperability and modularity. Where possible, specify interface standards and modular replacement paths to reduce lifecycle risk and avoid vendor lock-in in a rapidly evolving technology landscape.
- Pursue public funding and pilot aggregation. Leverage available grant programs and pooled procurement structures to reduce unit costs for early adopter projects, while using pilots to generate local performance data that supports wider rollouts.
What the PW Consulting Report Delivers — Practical Tools, Not Just Projections
PW Consulting’s full report is structured as an execution-focused intelligence product tailored for CFOs, procurement leads, and grid modernization program managers. Key deliverables include:
- Detailed global market sizing and forecast models (base year 2025; forward view 2026–2032) with scenario toggles for regulation and raw-material shocks.
- Segment frameworks by geography, voltage class and technology pathway, each paired with risk matrices and deployment playbooks. (Note: granular segment-level financials and regional shares are presented in the full report to preserve commercial value.)
- Competitive benchmarking and supplier scorecards covering engineering capabilities, manufacturing footprint, recent project references and commercialization roadmaps.
- CapEx/Opex modeling templates and procurement checklists to support business-case development and board-level approval packages.
- A regulatory tracker and policy impact assessment that maps timing, compliance thresholds and strategic mitigation options by major jurisdiction.
- M&A and partnership opportunity mapping, including valuation sensitivities under different adoption curves.
Final Assessment: From Compliance Cost to Strategic Asset
Transitioning to environmentally friendly GIS is no longer solely an environmental compliance exercise. For those able to navigate supplier selection, timing and lifecycle economics, SF6-free solutions can reduce long-term regulatory exposure, open funding windows, and support system resilience objectives. But the path is nuanced: technology choices, supplier capacity, and gas supply economics will materially influence outcomes.
PW Consulting’s report equips decision-makers with the integrated insights required to turn uncertainty into competitive advantage in 2026. For executives preparing capital budgets, negotiating supplier agreements, or evaluating acquisition targets in the GIS ecosystem, a data-driven, scenario-based approach is the difference between reactive compliance and proactive market leadership.
Next Steps
For complete access to the market models, segment breakdowns, vendor scorecards and downloadable CapEx/Opex templates that underpin this briefing, please consult the full report and its companion datasets on our website. PW Consulting’s analyst team is available for tailored briefings and custom scenario runs to support board-level decision timelines in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com